

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Retail Analytics Market to Hit USD 21.5B by 2032 at 14.8% CAGR

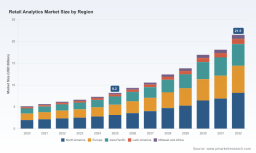
Retail Analytics Market 2026: Strategic Imperatives for Decision-Makers
Between the structural shifts in consumer behavior and the rapid maturation of AI-driven tooling, retail analytics is evolving from a supporting capability into a core strategic asset. PW Consulting’s latest Retail Analytics Market study—rooted in a 2025 base year and a historical review covering 2020–2025—maps that transition in actionable detail. The market has expanded at a compounded annual growth rate (CAGR) of 14.8% and is expected to more than double from its 2025 baseline to reach roughly USD 21.5 Billion by 2032. For executives planning 2026 capital allocations, vendor selection, or transformation roadmaps, this study reframes analytics as an investment that dictates competitiveness across assortment, pricing, supply chain resilience, and customer lifetime value.
Retail Analytics Market
Why this research matters for 2026 decision cycles
-
Timing and scale: The market’s sustained near-15% CAGR signals that analytics capability is not experimental overhead but strategic infrastructure. Decisions made in 2026—whether to accelerate cloud adoption, rationalize point solutions, or consolidate vendors—will determine which retailers capture disproportionate upside as the market matures.
Retail Analytics Market -
From insight to automated decisioning: The shift from descriptive dashboards to agentic, decision-making AI has accelerated. Our research documents how maturity in forecasting, replenishment, and merchandising automation materially reduces working capital and shrink when deployed with governance guards—making 2026 the year to pilot end-to-end automation at scale.
Retail Analytics Market -
Strategic sourcing and partnering: The vendor ecosystem is diversifying—global cloud platforms, specialized image-recognition incumbents, and regional customer-engagement providers all compete for wallet share. Our study helps buyers translate market momentum into procurement strategies that balance innovation access, total cost of ownership, and regulatory compliance.
What the report delivers: pragmatic tools, not just charts
We intentionally designed this research as a practitioner’s guide. Beyond market sizing and trend narratives, the report contains:
-
Actionable adoption frameworks that map expected benefits to organizational maturity stages, enabling CFOs and CIOs to sequence investments for the fastest ROI.
-
Deployment playbooks (cloud-first and hybrid scenarios) with milestone-based KPIs, runbooks for model governance, and integration checklists for POS, ERP, and CDP systems.
-
Vendor assessment tools: comparative scorecards, RFP templates, and a vendor short-list methodology calibrated to typical retailer priorities—availability, margin protection, and customer experience.
-
Commercial models and TCO calculators that capture software, services, data costs, and change management—designed to make the business case in Board-level terms.
-
Case studies and implementation retrospectives highlighting practical obstacles (data lineage, organizational friction, and model drift) and the mitigations that worked.
Market trajectory: what the numbers tell us (and what they hide)
The headline growth rate and the multi-year projection indicate a rapidly expanding opportunity pool across software, services, cloud, and specialized applications. Our base-year analysis (2025) captures the market’s scale and momentum; the forecast through 2032 shows acceleration driven by investment in AI-native platforms, cloud migration, and automation of supply chain and merchandising decisions.
We deliberately do not disclose the granular segment-level figures here. The value of segment-by-segment splits—by region, deployment mode, application, and buyer type—lies in tailoring vendor strategies and investment cases. Those segmented insights, included in the full report, are the precise data executives will want when defining procurement strategies or planning M&A activity.
Competitive landscape: positioning and implications
Market concentration remains modest: the top three vendors account for roughly a quarter of market revenues, and the top five approach the low‑to‑mid 30s percentage range. This dispersion creates room for large cloud incumbents, specialized platform vendors, and regional champions to co-exist—and for clients to pursue composable architectures.
-
RELEX Solutions (Finland) —an AI-native planning platform focused on integrated forecasting, inventory optimization and waste reduction. RELEX exemplifies the specialist vendor that converts vertical depth into measurable inventory and service-level gains. For retail leaders prioritizing availability and loss reduction, specialist platforms remain attractive integration targets.
-
Microsoft (United States) —a cloud and AI heavyweight delivering agentic retail capabilities for merchandising, operations, and supply chain automation. The company’s recent introduction of agentic features raises the bar for automation-ready platforms and positions cloud providers as primary partners for large-scale transformation.
-
IBM (United States) —focusing on Watson-driven analytics for customer behavior and operations. IBM’s strengths lie in enterprise-grade tooling and services for complex, regulated deployments.
-
Oracle and SAP —both offer retail-focused analytics embedded with ERP and merchandising suites; they appeal to customers seeking integration depth and pre-built operational dashboards.
-
Salesforce —leveraging CRM and Einstein AI to close the loop between customer analytics and merchandising/execution.
-
Capillary Technologies and Trax —examples of regional and specialist vendors (customer engagement and shelf intelligence, respectively) that bring differentiated data and use-case focus to omnichannel execution.
Recent developments underline two patterns. First, hyperscalers are embedding higher levels of automation into retail product suites—Microsoft’s early-2026 agentic AI launch is emblematic. Second, strategic partnerships between large retailers and cloud providers (for example, alliances formed in early 2026) show that retailers prefer co-engineering relationships to off-the-shelf deployments when disruptions to supply chain and store operations are at stake.
Regulatory and operational headwinds
Regulation is now a material element of any 2026 analytics strategy. The landscape includes enhanced US state-level privacy rules, the EU GDPR’s high fines and transparency demands, and the EU AI Act’s classification of many retail analytics applications as high-risk—each increasing compliance complexity and operational costs. In California, recent regulatory updates expand cybersecurity audits and requirements for automated decision-making disclosures—practical impacts that must be built into procurement contracts and model governance frameworks.
Operationally, three recurring risks demand mitigation: data quality and lineage failures, model governance and drift, and a shortage of analytics talent capable of translating model outputs into commercial action. Our report maps mitigations—data contracts, shadow-bureau testing, and capability accelerators—into a stage-gated roadmap to reduce implementation risk.
Recommendations: what to prioritize in 2026
-
Start with use cases that link to cash: prioritize inventory and demand-sensing pilots that directly release working capital or reduce stockouts. Use clear KPI guardrails (OOS rate, days of inventory, margin impact) and require vendor pilots to deliver measurable P&L outcomes.
-
Adopt a composable architecture: balance best-of-breed analytics with enterprise-level data governance. Favor open data contracts and API-first vendors to avoid lock-in while enabling rapid substitution as capabilities evolve.
-
Embed compliance into procurement: demand vendor evidence on privacy-by-design, model explainability, and regulatory certifications. Budget for incremental compliance costs—especially in jurisdictions covered by GDPR, the EU AI Act, and enhanced state privacy regimes.
-
Negotiate for co-development and outcome pricing: where feasible, structure contracts that share implementation risk and tie fees to realized business outcomes rather than pure consumption.
-
Invest in people and process: coupling algorithms with frontline operations is where value is realized. Prioritize cross-functional squads that pair data scientists with category managers and supply chain planners.
Implementation roadmap and KPIs
Our practical roadmap breaks a 12–24 month program into three phases: stabilize (data and baseline metrics), scale (automation pilots and integration), and sustain (governance, cost optimization, and continuous improvement). Each phase comes with defined KPIs—data completeness, forecast accuracy lift, inventory turns improvement, and operational outage reduction—enabling Boards and executive sponsors to track value realization.
Conclusion: the strategic choice for 2026
Retail analytics is no longer a departmental initiative; it is a strategic competency that shapes assortment, pricing, operations, and customer experience. The market’s structural growth and the acceleration of agentic AI capabilities create a window in 2026 for retailers to capture outsized returns—if they combine pragmatic pilots, disciplined procurement, and robust governance. PW Consulting’s Retail Analytics Market report supplies the maps, tools, and vendor context leaders need to make those choices with confidence.
To access the full segmented analysis, vendor profiles, and downloadable implementation toolkits that support these strategic recommendations, please consult the complete report on our website.
For detailed analysis of this topic, please visit the official page: Retail Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com