

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicon Carbide Ceramics Market to Reach USD 160 Million by 2032 at 5.5% CAGR

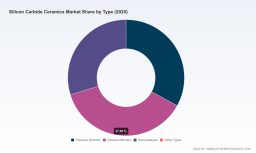
Silicon Carbide Ceramics Market: Strategic Primer for 2026 Decision-Making
Executive Snapshot
As enterprises prepare capital plans and product roadmaps for 2026, silicon carbide (SiC) ceramics occupy a strategic intersection of materials science, industrial electrification, and high-temperature manufacturing. Our market model shows a base-year value of roughly USD 110 Million in 2025 and a trajectory to approximately USD 160 Million by 2032 — an implied compound annual growth rate (CAGR) of about 5.5% across the 2026–2032 forecast window. Historical performance between 2020 and 2025 reflects modest growth punctuated by episodic softness, underlining the importance of tactical timing across sourcing, capacity investments, and commercial launches.
Silicon Carbide Ceramics Market
Why this research matters to 2026 strategic choices
-
Material substitution and design cycles accelerate: SiC ceramics are moving from niche high-performance use towards broader adoption in electrified industrial systems and semiconductor tooling. Procurement and R&D leaders who act early can lock in technology advantages and supplier terms before demand tightens.
Silicon Carbide Ceramics Market -
Supply-side complexity escalates: Manufacturing routes (pressure sintered, reaction bonded, recrystallized and variants) carry distinct cost structures and scale profiles. Sourcing strategies that ignore process heterogeneity risk higher cycle-time and scrap exposure.
Silicon Carbide Ceramics Market -
Market structure is defensible but not immovable: A handful of incumbent firms account for a meaningful portion of supply, creating an environment where targeted partnerships, tolling arrangements, or bolt-on acquisitions can rapidly shift competitive dynamics.
Market dynamics: growth drivers and structural headwinds
Over the forecast period the market is expected to grow at a steady mid-single-digit CAGR. This expansion is driven by three converging forces: (1) increasing demand from electrification and power-dense industrial equipment, (2) continued substitution of metallic parts where corrosion, wear, and thermal stability matter, and (3) growing adoption in semiconductor processing and specialty tooling. At the same time, supply-side constraints — including capital intensity of advanced sintering lines, quality control for high-purity grades, and periodic raw-material cost volatility — create windows of tightness that can amplify price and lead-time risk.
Technology and manufacturing implications
-
Process selection dictates economics: Reaction-bonded and pressure-sintered routes trade off density, achievable tolerances, and cost-per-unit. That trade-off cascades into product positioning: high-volume, lower-tolerance components favor different platforms than low-volume, ultra-high-performance parts.
-
Upstream integration is a leverage point: Firms that invest selectively in preform or precursor control can compress variability and improve yields. For corporate strategy, the question is where to internalize capability versus secure long-term supply agreements.
-
Advanced shaping methods and additive techniques are nascent but strategic: Early adopters of precision near-net shaping and hybrid manufacturing can reduce secondary machining needs — a critical margin lever for high-value geometries.
Competitive landscape — who matters and why
The competitive fabric of the SiC ceramics industry blends global incumbents, engineering-focused specialists, and regional manufacturers with cost-competitive scale. Market concentration is meaningful: the top few players together account for a sizeable share of total revenue, creating both opportunity and risk for challengers and buyers alike. Below we profile the strategic positioning of the core suppliers covered in our study, focusing on the capabilities that matter to corporate buyers.
-
CoorsTek (Golden, CO, USA) — Strengths in sintered and reaction-bonded SiC position CoorsTek as a go-to for industrial and semiconductor applications requiring consistent batch performance. Their global footprint and diversified product set make them a preferred partner for companies seeking reliability over low-cost sourcing.
-
Kyocera Corporation (Kyoto, Japan) — Kyocera’s advanced component capabilities and presence in semiconductor equipment ecosystems give them strategic proximity to high-value downstream customers. Recent trade show activity underscores their intent to push technical ceramics as a core growth axis.
-
Saint-Gobain (Courbevoie, France) — With a broad structural ceramics portfolio, Saint-Gobain competes on systems-level material integration and engineering services, an advantage for OEMs looking to co-develop solutions rather than buy commoditized parts.
-
CeramTec (Lauingen, Germany) — Known for performance in chemically aggressive and mechanically demanding environments, CeramTec is a natural supplier for process-intensive industries where long service life and certification matter.
-
Morgan Advanced Materials (Windsor, UK) — Morgan brings deep sector expertise in specialty technical ceramics, making them a frequent partner where application-specific performance and regulatory traceability are priority decision criteria.
-
NGK Insulators & 3M — Both companies leverage broader materials and components ecosystems to supply SiC-based products integrated within larger assemblies, offering customers simplified vendor management and engineered warranties.
-
Specialists & regional players (IPS Ceramics, Schunk, Blasch, Ortech, Advanced Ceramic Materials; select Chinese manufacturers) — These firms provide agility: custom shapes, short lead times for prototyping, and competitive pricing on volume. They also represent potential partners for OEMs seeking near-market supply or supplementary capacity.
Recent signals to watch (and leverage)
Trade shows, product announcements, and capacity investments often presage commercial shifts. For example, Kyocera’s public emphasis on technical ceramics at a major industry event in early 2026 is consistent with a broader push by equipment suppliers to vertically integrate specialized ceramic components. Such public signals can be used to anticipate supplier pricing posture, likely partnership offers, and potential capacity expansions that affect mid- to long-term procurement planning.
Strategic playbook for corporate decision-makers in 2026
Based on our granular analysis and scenario modeling, we recommend five priority actions for senior leaders finalizing 2026 plans.
-
Revisit sourcing architecture: Segment spend by process type and criticality. For high-impact supply items, negotiate multi-year agreements with capacity reservation clauses; for opportunistic parts, build a dual-sourcing shortlist that balances technical fidelity with geographic redundancy.
-
Align R&D roadmaps to manufacturable variants: Ensure product engineers specify part geometries and tolerances that reflect realistic yield curves for the chosen SiC manufacturing route. Small design concessions can materially reduce cost and time-to-market.
-
Build a supplier intelligence sentinel: Monitor leading suppliers for capacity announcements, trade-show positioning, and shifts in product focus. Early detection of supplier strategic moves allows procurement and strategy teams to preemptively model scenarios rather than react under time pressure.
-
Evaluate selective vertical moves: For firms with high exposure to SiC-specific components, the business case for captive preform production or long-term joint ventures improves materially in scenarios where lead times and quality premium underpin customer contracts.
-
Prioritize sustainability and compliance: Environmental permitting and higher-grade raw-material sourcing are increasingly relevant to procurement. Vendors with traceable supply chains and lower process emissions will carry a commercial premium that is rapidly becoming non-negotiable for many industrial end-users.
What our full report delivers — practical, transaction-ready tools
This research is designed as a hands-on decision support dossier for 2026. Highlights include:
-
A validated market model (2020–2032) with scenario adjustments for demand shocks and supply constraints that finance and strategy teams can integrate into capital planning spreadsheets.
-
Supplier capability matrices and an operational scorecard that let procurement rate vendors across process, quality, lead time, and innovation metrics.
-
Playbooks for manufacturing footprint decisions, including make-or-buy thresholds, tolling options, and nearshoring templates tailored to SiC process economics.
-
Commercial templates: term-sheet language for capacity reservation, quality-acceptance criteria, and IP-sharing clauses for co-development projects.
-
M&A and partnership heatmaps identifying bolt-on targets and JV structures based on technical fit and geographic complementarity.
-
Price and margin sensitivity tools that demonstrate the impact of yield improvements, scale-up learning curves, and raw-material swings on unit economics.
Why the “trailer” approach matters
The intent of this briefing is to expose the strategic contours and decision levers without disclosing the granular segmentation data that drive tactical moves. The full report contains detailed regional and application splits, process-level cost models, and vendor-specific benchmarking that companies routinely use to negotiate supplier contracts, size capacity investments, and execute M&A. If your 2026 plan depends on timing, supplier choice, or a manufacturability advantage, those granular inputs are the difference between a defensible strategy and an expensive misstep.
Next steps
-
For procurement teams: request the supplier scorecard annex to begin triage of existing contracts in light of our scenarios.
-
For product and R&D leaders: obtain the manufacturability playbook to align tolerancing and material choices with realistic yield curves.
-
For strategy and corporate development: consult the M&A heatmap and concentration analysis before initiating transaction-level diligence.
PW Consulting’s full Silicon Carbide Ceramics Market report consolidates the models, vendor assessments, and implementation tools needed to turn 2026 uncertainty into a structured program of action. For access to the comprehensive datasets, granular regional and application splits, and the tactical annexes referenced above, please visit our research portal.
For detailed analysis of this topic, please visit the official page: Silicon Carbide Ceramics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com