

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Recirculating Chillers Market to Reach USD 1,191.9M by 2032 at 5.2% CAGR

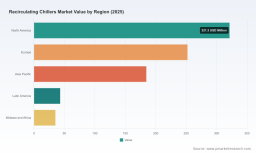
Recirculating Chillers Market 2026: A Strategic Preview for Decision-Makers
As organizations finalize 2026 budgets and strategic roadmaps, the recirculating chillers sector presents a distinct combination of steady growth, tightening regulatory pressure, and rapid product-level innovation. PW Consulting’s latest market study — anchored to a 2025 base year with a 2026–2032 forecast window — shows the market accelerating from a mid‑hundreds million USD scale in 2025 to a materially larger opportunity by 2032, tracking a compound annual growth rate of 5.2% across the forecast horizon. For executive teams evaluating R&D allocation, channel investments, M&A targets, or product portfolio rationalization, the choices made this year will determine whether organizations capture premium product segments or become relegated to low-margin competition.
Recirculating Chillers Market
Why 2026 is an inflection point
-
Regulatory convergence: New and updated efficiency standards in major markets are converging on energy performance and ecodesign requirements. China’s updated heat pump and chiller standard (GB 19577‑2024) and the continuing reach of EU ecodesign rules — now contextualized by the Sustainable Products Regulation — create a near-term compliance cliff that will influence procurement, product design, and market access.
Recirculating Chillers Market -
Energy and sustainability priorities: End users across laboratory, medical, semiconductor and industrial segments are shifting procurement criteria from first‑cost to total cost of ownership (TCO), with energy efficiency and lifecycle emissions rising as decisive factors.
Recirculating Chillers Market -
Technological step‑changes: Product launches through 2024–2025 have emphasized compact form factors, low‑noise operation, speed‑controlled compressors, and Ethernet/IoT connectivity — features that change buyer expectations and create retrofit/service opportunities.
-
Market structure dynamics: The market shows meaningful market share held by leading vendors but remains sufficiently fragmented to allow tactical consolidation, strategic partnerships, and regional specialization strategies.
Market trajectory and implications for investment choices
From 2020 through 2025 the sector recorded steady expansion, reflecting resilience of laboratory, medical and semiconductor demand even amid broader macro volatility. The market moves into 2026 at an elevated base and is projected to continue expanding through 2032 under a moderate compound growth profile (5.2% CAGR across the forecast period). That trajectory implies that manufacturers and channel partners who act now — aligning product roadmaps to efficiency regulations and embedding digital monitoring — can capture higher‑margin installed base upgrades and recurring service revenue. Conversely, delaying investments in energy‑efficient platforms or service capabilities will increase the risk of margin erosion as competition bifurcates toward premium, compliant offerings and cost‑focused imports.
What the PW Consulting report delivers — practical, decision‑grade content
This research goes beyond high‑level trend description. It includes a suite of operational tools designed to support boardroom and commercial execution in 2026:
-
Segment‑level demand projections and scenario stress tests, with clear assumptions you can adapt to your market footprint.
-
Go‑to‑market playbooks for OEMs, distributors and service providers — including channel segmentation, margin models and sales incentives calibrated to energy‑efficiency premiums.
-
CapEx vs. OpEx decision matrices for product upgrades and retrofits, with TCO calculators reflecting energy pricing sensitivities and regulatory compliance costs.
-
Procurement and supplier due‑diligence checklists (quality, warranty, compliance documentation) tailored to lab, medical and industrial buyers.
-
Technical benchmarking templates that compare thermal performance, footprint, noise, connectivity and maintainability — structured to support RFPs and vendor selection without exposing sensitive segment tables here.
-
Service transformation roadmaps to convert field service into recurring revenue (remote monitoring, predictive maintenance, retrofit kits, spare parts planning).
Competitive landscape — positioning and strategic moves
The sector combines global instrument and distribution heavyweights with specialized engineering firms and agile regional manufacturers. Market concentration metrics indicate that top players account for a meaningful share of revenue while a long tail of niche and regional suppliers continues to service bespoke needs; this mix creates both consolidation opportunities and disruption risks for incumbents.
-
Large instrument and lab OEMs (e.g., multinational scientific groups) leverage integrated systems and brand trust to sell premium, instrument‑matched chillers — their strategic strengths are product integration, channel reach and cross‑sell potential into existing instrument install bases.
-
Industrial automation and components players focus on ruggedness, uptime and scale; they compete on reliability and OEM relationships with process customers rather than lab branding.
-
Precision manufacturer specialists (European and North American firms) differentiate on accuracy, temperature stability and low‑noise footprints — attributes that command premium pricing in laboratory and semiconductor contexts.
-
Custom engineering houses and regionally focused manufacturers compete on lead times, adaptability for extreme temperature ranges, and low cost for non‑regulated markets; they represent fast followers and strategic acquisition targets for larger players seeking manufacturing scale.
Recent product activity reinforces these dynamics. New unit designs emphasize compact under‑counter formats for lab workflows, speed‑controlled compressors that deliver substantial energy savings in real operating cycles, and Ethernet/IoT connectivity that enables remote service and usage‑based business models. These features are no longer experimental — they are increasingly baseline expectations in many buyer segments.
Regulatory landscape: near-term threats and long‑run enablers
Regulations are shaping product roadmaps and supplier viability. Major markets have tightened energy performance expectations and clarified ecodesign rules for chillers and high‑temperature process equipment. Comparative benchmarking studies also show variation in how aggressivly metrics are applied across regions, which affects how manufacturers prioritize compliance testing and documentation. For market participants, the immediate priorities are to audit product compliance, map certification conversion timelines, and quantify the engineering and documentation effort required for market access in regulated jurisdictions. Where compliance costs are non‑trivial, there is a direct rationale for premiumization (energy‑efficient SKUs) and for monetizing retrofit and certification services.
Recommended strategic plays for 2026 decision‑makers
-
Prioritize energy‑efficient core platforms: invest in compressor control, heat exchanger optimization and variable‑speed drives to defend margins as TCO replaces first‑cost in procurement decisions.
-
Modularize product families: create shared platforms with configurable cooling capacities and accessory ecosystems to accelerate time‑to‑market for compliant SKUs.
-
Monetize installed base: deploy IoT monitoring and predictive maintenance to convert one‑time sales into recurring service revenue and to offer retrofit compliance kits.
-
Target bolt‑on M&A: identify regional manufacturers with manufacturing scale or specific technical competencies to shorten certification and distribution cycles.
-
Strengthen channel alignment: invest in distributor training, energy‑based sales incentives and lab procurement tooling to capture specification momentum.
-
Embed compliance into product development: make regulatory timelines a gating factor in R&D roadmaps to avoid market access delays and surprise reworks.
How PW Consulting’s full report helps you act
This article outlines the strategic stakes and high‑impact plays for 2026 but deliberately omits granular segment tables and certain competitive splits to preserve the value of the full analysis. The comprehensive report contains the detailed segmentation, regional and application forecasts, vendor scorecards, pricing benchmarks, and primary interview excerpts that decision‑makers need to finalize sourcing strategies, investment cases and M&A screening. It also includes ready‑to‑use templates — from procurement RFPs to retrofit ROI calculators — that accelerate execution.
In short, 2026 will reward organizations that treat the recirculating chillers market as a technology‑and‑regulation driven sector: invest in efficiency and connectivity, monetize the installed base, and use regulatory timelines to create product differentiation rather than compliance cost. PW Consulting’s study provides the data, tools and playbooks you need to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Recirculating Chillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com