

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: UHD TV Market to Hit USD 480.65 Million by 2032 at 12.2% CAGR

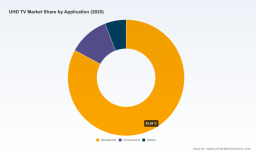
UHD TV Market: A Strategic Preview for 2026 Decision-Makers
Executive snapshot
The UHD TV market has entered a new growth inflection driven by faster display innovation, software-enabled differentiation, and renewed consumer upgrade cycles. Our base-year assessment for 2025 values the global market at approximately USD 215 million (revenue unit: Million USD), with an expected continuation of robust expansion through the forecast window. PW Consulting’s model projects a multi-year compound annual growth rate of 12.2% for the forecast period, bringing total market scale to roughly USD 481 million by 2032 under the central case. For leaders who must make capital allocation, product roadmapping, or M&A decisions in 2026, this trendline is not an academic curiosity — it defines addressable opportunity, supply chain stress points, and the competitive stakes for the coming decade.
UHD TV Market
Why this preview matters to 2026 strategy
- Timing of investment: The market’s trajectory signals a window for capturing disproportionate share if supply, channel, and software bets are placed by mid‑2026.
- Capital discipline: With rapid technology cycles (Mini LED, Micro RGB, OLED variants, advanced upscaling and platform software), 2026 is when R&D and capex must be rebalanced toward modular designs and software/IP that extend product lifecycles.
- Supply chain positioning: Tariff volatility and raw-material pressures are reshaping sourcing economics. Decisions about localization, long‑term panel contracts, and buffer inventories will materially affect 2026 P&Ls.
- M&A and partnerships: Platform plays (OS, AI upscaling, content partnerships) are becoming as valuable as panel performance. Executives should prioritize bolt-on targets that accelerate software differentiation and post‑purchase engagement.
Market dynamics — what the data reveals (high level)
Our historical and forward-looking model (base year 2025; historical 2020–2025; forecast 2026–2032) shows an industry recovering and accelerating from a decade of commoditization into a phase where feature-led and software-enabled differentiation command premium pricing. The mid-2020s mix shift toward advanced backlighting (Mini LED, Neo QLED variants), improved AI upscaling, and platform-level value has expanded realized ASPs even as unit volumes recover. The result: a market that roughly doubles in monetary terms over the forecast horizon under the central scenario, led by technology adoption and aftersales/platform monetization.
UHD TV Market
Competitive landscape — profiles and strategic implications
The UHD TV market remains competitive and relatively fragmented compared with other consumer electronics categories — top supplier concentration is modest, which preserves opportunities for disruption and share gains by fast-moving players. Key incumbents we monitor closely include:
UHD TV Market
- LG Electronics (Seoul): Continuing to push premium OLED and thin-form-factor differentiation, LG’s 4K Nano UHD line and recent ultra-thin wallpaper OLED announcements demonstrate a dual strategy — premium industrial design plus color/contrast innovations (Nano Detail Enhancer) that support higher ASPs and brand equity.
- Samsung Electronics (Suwon): Samsung’s product roadmap centers on Neo QLED and Mini LED variants, coupled with ecosystem-level features such as AI upscaling, HDR10+ ADVANCED optimization, and a widening Vision AI portfolio. These strengths support both high-volume and premium segments.
- Sony Group (Tokyo): Sony’s Bravia series emphasizes cognitive processing and XR Backlight technologies that enhance perceived 4K fidelity; their positioning targets premium buyers and content partnerships.
- TCL Electronics (Huizhou): TCL is executing an aggressive value-and-performance play with ULED and Mini LED models and a strong cost‑to‑performance narrative, including Super Quantum Dot technology targeted at price-sensitive growth markets.
- Hisense Group (Qingdao): Hisense focuses on competitive ULED offerings with Quantum Dot enhancements, blending aggressive channel expansion with targeted feature differentiation.
- VIZIO, Inc. (Irvine): VIZIO emphasizes software-led value through its VIZIO OS and competitive hardware at mainstream price points, extracting higher lifetime value via platform services.
Notably, the first months of 2026 saw major product rollouts that further crystallize vendor strategies: Samsung’s full AI TV lineup (with HDR10+ ADVANCED and cross-technology support), LG’s ultra-thin OLED and Micro RGB evo announcements, and TCL’s refreshed Mini LED and Super Quantum Dot models. These launches underscore a bifurcation: a premium, design- and processing-led cluster, and a volume cluster optimized around cost-efficient Mini LED / Quantum Dot innovation and software aggregation.
Supply chain and policy headwinds
Two structural themes are central for 2026 planning:
- Trade and tariff risk: Recent increases in U.S. tariffs on TV-related components have elevated landed costs and forced manufacturers to reconsider cross-border sourcing and assembly footprints. These policy moves alter short‑term cost stacks and can change relative competitiveness across vendors depending on localization and hedging strategies.
- Raw material and component dynamics: Panel supply constraints, backlight module availability, and semiconductor lead times continue to create episodic price spikes and NPI delays. Companies that secure multi-year agreements or local assembly options improve resilience and margin predictability.
What the PW Consulting report delivers (practical detail without revealing core splits)
We designed the full UHD TV Market study as a decision-support toolkit for executives. Highlights include:
- Proprietary market model: Historical tracking (2020–2025) and a transparent forecasting engine (2026–2032) with scenario toggles for demand elasticity, tariff shocks, and technology adoption curves. The executive preview provides headline growth and CAGR; the full model includes interactive inputs and sensitivity outputs for board-level stress testing.
- Go-to-market playbooks: Actionable strategies for product portfolio optimization, channel mix shifts (retailer, e‑commerce, B2B), and subscription/aftercare initiatives — each tied to ROI assumptions and implementation milestones.
- Supply chain diagnostics: A mapped supplier matrix for panels, backlights, SoC suppliers, and firmware platforms, with recommended mitigation levers for tariff and raw-material scenarios.
- Competitive benchmarking: Deep vendor profiles, feature-comparison scoring, and strategic positioning maps that identify white spaces and near-term encroachment risks from both incumbents and emerging players.
- Transaction support: M&A screening criteria for technology and platform targets, valuation frameworks, and a shortlist of inorganic plays to accelerate software and content capabilities.
- Implementation KPIs: A recommended dashboard (go-to-market metrics, supply chain lead indicators, warranty and retrofit economics) to drive 90‑, 180‑, and 360‑day execution cycles.
- Primary research appendix: Interview summaries with OEMs, panel suppliers, and leading retailers, plus an annotated bibliography of industry sources and regulatory inputs.
High-level strategic recommendations (teaser)
- Pivot to software-enabled differentiation: Prioritize investments in AI upscaling, content partnerships, and OS experience to extend ASP and aftersales revenue streams. Hardware parity narrows quickly; software lock-in lengthens customer lifetime value.
- Insulate gross margins via supply architecture: Dual-sourcing panels and localizing assembly in tariff‑sensitive markets are effective mitigants. Negotiate volume-committed agreements with flexible breakpoints to preserve agility.
- Segment portfolio for margin capture: Deploy distinct product ladders — a premium, R&D-intensive line that signals brand leadership and a cost-optimized mainstream line that protects volume share. Use standardized modules to reduce NPI cycles and cost.
- Operationalize scenario planning: Build tariff and raw‑material shock scenarios into the rolling forecast and capital planning process; predefine trigger actions (e.g., temporary price adjustments, buy‑forward volumes, deferred launches).
- Evaluate targeted acquisitions: Look for deals that buy software/IP, platform distribution, or critical component supply (backlighting, mini-LED fabs) rather than broadscale manufacturing assets that carry high capex and integration risk.
Next steps — how to use this preview
This introduction is a strategic “trailer” designed to set priorities for 2026. It demonstrates the rigor of our approach—combining a published CAGR and headline market scale with vendor-level intelligence and scenario-ready tools—while preserving the detailed, proprietary segment tables and revenue splits for the full report package. For organizations preparing board materials, capital plans, or M&A mandates, the full PW Consulting UHD TV Market study provides the executable templates, the editable financial model, and the vendor scorecards required to translate strategy into measurable actions.
Contact and access
To request the full report, the interactive forecast model, and vendor scorecards (including granular regional, type, and application breakdowns), contact PW Consulting’s industry research desk. The full deliverable includes the confidential annexes and a 90-minute briefing with our senior analysts to walk through scenarios and recommended next steps tailored to your position in the value chain.
For detailed analysis of this topic, please visit the official page: UHD TV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com