

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Residential Zoning Systems poised for USD 1,338.45M in 2025

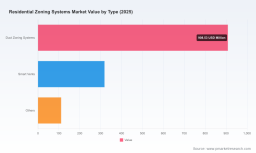
Residential Zoning Systems Market — Strategic Primer for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a concise yet strategically rich preview of our new market research on Residential Zoning Systems. This primer is designed for executives, corporate strategists, and product leaders who must set priorities for 2026 with clarity and conviction. It demonstrates the analytic depth of our full study while intentionally withholding granular segment tables and proprietary benchmarks — a deliberate “trailer” to guide decision-makers to the full report for transaction-grade detail.
Residential Zoning Systems Market
Why this market matters in 2026
Residential zoning systems occupy a pivotal intersection of energy efficiency, occupant comfort, and the rapid digitization of home HVAC controls. Coming off a sustained period of expansion, the market’s macro trajectory remains constructive: our model benchmarks the overall market at roughly USD 1.34 billion (Million, base year 2025), and projects a compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast window. By late-decade, the market approaches the low‑billion dollar range, reflecting durable demand from both new-build and retrofit segments.
Residential Zoning Systems Market
For 2026 decision calendars, that trajectory translates into three practical imperatives for incumbents and new entrants alike: move from product to solution (controls + services), invest in connectivity and user experience, and align commercialization to the twin engines of regulation and measurable energy savings.
Residential Zoning Systems Market
Macro drivers shaping strategy
-
Energy efficiency mandates and standards: Ongoing updates to industry design guidance (notably ACCA’s Manual ZR program and its recent public-review activity) are increasing the technical expectations for zoned comfort design. For executives, the implication is simple: products and installation protocols that map to recognized standards will reduce friction in specification and improve acceptance among professional contractors and architects.
-
Measurable energy economics: Government and independent studies indicate that zoning can deliver substantial energy savings when correctly designed and operated. With publicized figures suggesting energy uplifts that can reach mid‑double digits in favorable cases, zoning becomes not only a comfort feature but a sellable energy conservation measure — a narrative that supports incentive-backed installations and helps justify premium pricing or retrofit investment.
-
Technology convergence: The transition from electromechanical and pneumatic solutions to digitally native zone controllers and smart vents is accelerating. This is enabling finer-grain control, over-the-air firmware updates, predictive maintenance, and integration with home energy management systems (HEMS). For product and R&D leaders, the window to embed software-enabled differentiation and to establish recurring revenue models is now.
-
Channel and installation dynamics: Zoning systems remain closely tied to the HVAC contracting channel. System complexity and labor time are determinants of adoption. Solutions that simplify retrofit installs, reduce on-job complexity, and include robust contractor enablement (training, diagnostic tools, pricing calculators) will command market share and decrease churn.
Report scope — the practical outputs you can act on
The full PW Consulting study is constructed as an operator’s playbook. It goes beyond market sizing and trend narration to provide transaction-useful assets and go‑to‑market tools, including:
- Interactive market model (base year 2025, historical series 2020–2025, forecast 2026–2032) that supports scenario toggles for technology adoption, retrofit penetration, and incentive uptake.
- Segment-focused TAM-SAM-SOM frameworks and channel economics (note: detailed segment tables are reserved for the full report).
- Commercialization playbooks for product managers: pricing levers, bundling strategies (hardware + installation + subscription), and reseller incentive structures.
- Contractor and installer decision maps: typical installation paths, time/cost drivers, and objections management scripts.
- M&A and partnership screening matrix keyed to strategic objectives (scale, tech, channel), accompanied by a shortlist of capability targets and integration risk diagnostics.
- Regulatory and incentive tracker that maps evolving standards and national/local incentive programs to deployment economics for zoned systems.
- Competitive scorecards and product feature matrices covering control strategies, interoperability, and serviceability.
Competitive landscape — positioning and implications
The market exhibits moderate concentration: our analysis shows that the top three firms control a meaningful majority of commercial mindshare, and the top five extend that dominance further (CR3 ≈ 55%, CR5 ≈ 65%). This structure has three strategic consequences: margins for category leaders are defendable via integrated solutions; niches remain for specialized vendors; and M&A remains an effective route for capability acquisition.
-
Carrier Corporation — with offerings such as an advanced zoning product line that supports multiple zones and humidity/temperature targeting, Carrier plays to scale and integrated-system advantages. Their strength is product breadth and dealer networks; the strategic question for competitors is whether to compete on integration or on modular, lower-friction retrofit offerings that undercut total installed cost.
-
Arzel Zoning Technology — historically focused on pneumatic and hybrid controls, Arzel is positioned where reliability and retrofit compatibility matter most. Their value proposition is durability and installer familiarity — an asset in markets where labor cost and simplicity dictate solutions.
-
EWC Controls — electromechanical control specialists remain relevant for straightforward residential applications and for contractor segments that prefer field‑serviceable hardware over cloud-dependent systems. Their tactical advantage is lower complexity and proven lifecycle performance.
-
Research Products Corporation (Aprilaire) — augmenting zoning with indoor-air-quality (IAQ) messaging gives Aprilaire a differentiated narrative: comfort married to health. For product teams, coupling IAQ sensors and zoning controls is an escape hatch from purely price-based competition.
-
iO Systems, Zoning Supply, Zonefirst — these firms represent agile, contractor-focused players offering modular panels, dampers, and retrofit-friendly systems. Their go‑to‑market is channel-led and highly serviceable, making them natural acquirers or partnership candidates for larger OEMs seeking rapid field adoption.
-
Lennox and Honeywell — OEMs with deep HVAC and controls portfolios respectively, both are leveraging brand trust, existing distribution, and enterprise-grade control platforms. Their strategic playbooks focus on integrated systems, warranty-driven assurance, and cross-sell into existing service contracts.
Strategic playbook — what to do in 2026
For leaders preparing 2026 budgets and roadmaps, the following actions translate market intelligence into immediate strategic moves:
-
Prioritize retrofit-friendly innovation. Retrofit remains a large, high-opportunity pool. Reduce installer time through mechanical design choices, pre-programmed control panels, and plug‑and‑play dampers. Tooling that shortens the install cycle is a direct multiplier on adoption.
-
Embed connectivity and service revenue. Design products with secure remote diagnostics, over-the-air updates, and an opt‑in subscription for enhanced analytics. Even modest attachment rates materially improve unit economics over time.
-
Align product specs to ACCA and energy program guidance. Systems that simplify compliance with evolving design manuals and that map to incentive program eligibility lower the procurement barrier for contractors and consumers.
-
Invest in contractor economics: training, financing, and sales enablement. Contractors are the primary conversion channel — provide them with instant profit calculators, financing options for homeowners, and short certification programs to reduce installation anxiety.
-
Seek targeted partnerships. Look for partners in smart-thermostat ecosystems, IAQ providers, and home energy management platforms to expand reach. For incumbents, acquiring modular zoning specialists can accelerate entry into the retrofit space with limited channel disruption.
-
Prepare for regulatory momentum. Monitor Manual ZR revisions and local incentive rollouts closely. Early alignment will create specification advantages and first‑mover opportunities in incentive-funded retrofit pools.
Risks and watchpoints
-
Installer resistance to complexity: systems that increase install time without clear value capture will face pushback. Mitigation: co-design with contractors and pilot simplified installation kits.
-
Commoditization pressure: as connectivity and sensors become cheaper, differentiation can erode. Mitigation: secure differentiation through service bundles, warranty, and integration partnerships.
-
Standards and compliance shift risk: evolving guidance from industry bodies can render older design assumptions obsolete. Mitigation: keep R&D roadmaps flexible and maintain standing relationships with standards organizations.
How PW Consulting’s full research supports deal and product decision-making
The full report is engineered to support immediate decisions in 2026: M&A screening, go‑to‑market investment allocation, product roadmap prioritization, and channel redesign. It contains the market model, segment-level demand drivers, contractor economics, and competitive scorecards that boards and corporate development teams require to underwrite investments and to craft defensible growth plans. If you are evaluating a product pivot, acquisition target, or a major channel shift in 2026, the full study provides the quantitative and qualitative scaffolding to make that call with confidence.
In this primer we have surfaced the strategic contours: steady market growth (CAGR 5.8%), a mid‑billion‑dollar base, concentrated competitive dynamics, and a policy-and-technology environment that favors connected, retrofit-friendly solutions. The next step is to move from this strategic outline to executable plans informed by the granular segmentation, pricing bands, and scenario outputs contained in our full deliverable.
Next steps
-
For product leaders: request the product feature matrix and contractor install-time benchmarks to prioritize your 2026 R&D sprints.
-
For corporate development teams: obtain the M&A screening appendix and the target shortlist to accelerate diligence on strategic bolt-ons.
-
For commercial teams: secure the channel playbook and pricing sensitivity analysis to rework distributor incentives and sales comp for 2026.
PW Consulting’s full Residential Zoning Systems Market report contains the detailed data, models, and executable playbooks referenced here. Contact our research team to access the complete study and tailored advisory support to convert 2026 market opportunity into measurable growth.
For detailed analysis of this topic, please visit the official page: Residential Zoning Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com