

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Packaging Vacuum Coating Machine Market Set to Hit USD 344.8 Million by 2032; 6.98% CAGR

Packaging Vacuum Coating Machine Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused industry briefing designed to translate market intelligence into immediate 2026 decision levers for equipment manufacturers, packaging converters, private equity sponsors, and strategic procurement teams. This note synthesizes the core macro trajectory, competitive dynamics, regulatory shocks, and practical tools embedded in our full Packaging Vacuum Coating Machine Market research—showing why this capability will move from niche differentiation to strategic necessity over the next planning cycle.
Packaging Vacuum Coating Machine Market
Market trajectory at a glance (what the numbers tell you)
Using 2025 as the analytical base year, our market model shows the global packaging vacuum coating machine market at a robust inflection point. The market is projected to grow from a 2025 base through a 2026–2032 forecast window at a compound annual growth rate of roughly 6.98%, delivering material expansion by the end of the forecast horizon. This pace reflects a combination of retrofit activity, new line installations to meet barrier and aesthetic requirements, and incremental adoption of higher‑speed, roll‑to‑roll technologies in mature and emerging production hubs.
Packaging Vacuum Coating Machine Market
For executives setting capital plans in 2026, two takeaways are immediate: (1) growth is steady, not hyper‑cyclical—enabling staged investment approaches—and (2) the window for securing lead‑time‑sensitive equipment and first‑mover product differentiation is narrow thanks to supply‑side fragmentation and capacity constraints identified in our vendor analysis.
Packaging Vacuum Coating Machine Market
Why 2026 is a strategic pivot year
- Regulatory inflection: Extended Producer Responsibility (EPR) regimes in several North American jurisdictions enter full compliance in mid‑2026, reallocating end‑of‑life financial responsibility and accelerating demand for packaging solutions that balance barrier performance with recyclability. Our scenarios show EPR driving urgent specification changes among brand owners and converters.
- Material volatility: Macro indicators for plastics and resin show mixed signals—index movements and quarter‑to‑quarter price pressure are creating procurement uncertainty. That volatility increases the value of coating solutions that can enable material substitution or downgauging while retaining barrier properties.
- Technology convergence: Process innovations (higher‑speed PVD/PVC variants, PECVD hybrids, and inline quality metrology) are lowering cost per square meter of coated film while expanding the technical use cases for vacuum coating beyond decorative metallization to functional barrier and oxygen/moisture control layers.
Competitive landscape: not dominated—opportunity for differentiated plays
The competitive scene is characterized by a modestly concentrated supplier base at the top and a long tail of regional specialists. Our concentration metrics highlight that the market is far from monopolized—top competitors capture meaningful but not overwhelming shares—creating room for strategic moves by both incumbents and fast followers.
- HCVAC (Dongguan, China) — A leading Chinese PVD machine maker with strong capabilities in decorative and functional coatings. Recent exhibitions (Kitchen & Bath China, May 2025; Canton Fair, February 2026) underline active product marketing aimed at converging decorative systems with flexible packaging applications.
- Shandong Baofeng Metallizer Co., Ltd. (Qingzhou, China) — Specialist in vacuum metallizers and roll‑to‑roll equipment; strong play for converters prioritizing unit‑throughput and retrofit projects.
- Bobst Group SA (Lausanne, Switzerland) — Offers integrated production lines combining metallizing and coating within broader packaging systems; attractive for converters seeking single‑vendor integration and total line performance guarantees.
- Applied Materials Inc. (Santa Clara, USA) — While known for semiconductor tooling, Applied’s vacuum coating expertise transfers to barrier coating and film applications, especially where precision and thin‑film control are critical.
- Bühler Leybold Optics GmbH (Alzenau, Germany), ULVAC Technologies, Inc. (Flanders, USA), Von Ardenne GmbH (Dresden, Germany), Evatec AG (Pfäffikon, Switzerland) — These vendors collectively advance high‑performance PVD/CVD, PECVD, and high‑speed vacuum deposition platforms for premium packaging film segments.
Strategic implication: the fragmented structure creates acquisition targets, partnership opportunities (OEM + converter alliances), and service revenue upside for players who can bundle equipment with coatings expertise and lifecycle service agreements.
What the full report delivers (practical, immediately usable content)
This study is structured to be executable—beyond descriptive market sizing—so commercial teams can move from insight to action in 60–120 days. Key deliverables include:
- Scenario‑based demand model (2026–2032) that ties adoption curves to regulatory trajectories, resin price scenarios, and converter investment profiles.
- Total cost of ownership (TCO) and payback calculators with configurable inputs (line speed, yield improvements, energy, labor, coating material costs) to evaluate retrofit versus new line investments.
- Supplier benchmarking and capability matrix (throughput, line integration, energy consumption, footprint, after‑sales coverage) to fast‑track RFP short‑listing.
- Policy impact playbook that maps EPR and recycled content mandates to likely technical specifications, procurement RFP language, and certification pathways.
- Commercial playbooks: channel strategies for equipment makers, aftermarket service monetization templates for converters, and a private equity diligence checklist for buy‑side sponsors.
- Risk heatmap and mitigation tactics for raw‑material volatility, supply chain lead times, and regulatory timeline slippage.
Each toolkit is paired with worksheets and decision trees designed for boardroom use—so senior teams can quantify options during 2026 budgeting cycles without re‑engineering models from scratch.
Actionable strategic recommendations for 2026
- Prioritize retrofit pilots now. For converters under EPR pressure, low‑disruption retrofits that add barrier functionality or decorative value can preserve asset utilization while meeting near‑term compliance—use our TCO templates to select candidate lines.
- Lock critical OEM capacity and components. Lead times for high‑spec vacuum coaters and key subassemblies are material—negotiate early options or supplier agreements to avoid 9–12 month slippage in ramp plans.
- Design service‑led commercial models. Equipment vendors should embed remote diagnostics, uptime SLAs, and spare parts subscriptions to convert installation projects into recurring revenue streams.
- Invest in barrier R&D aligned to recycling pathways. Coating chemistries and layer architectures that enable mono‑material recycling, or that simplify delamination during reprocessing, will command preference from brands managing EPR liabilities.
- Hedge raw‑material exposure with contractual mechanisms. Given divergent indicators in resin indices and spot price pressure, buyers should employ indexed pricing, multi‑supplier sourcing, and inventory strategies calibrated to projected run‑rates.
- Explore bolt‑on acquisitions and strategic partnerships. OEMs and converters can quickly expand capability sets by acquiring niche metallizer makers or striking co‑development agreements with applied‑materials and specialty equipment suppliers.
Timing and implementation roadmap for 2026
- Immediate (Q2–Q3 2026): Run our quick‑scan TCO on top three candidate lines; issue conditional purchase orders or pilot contracts tied to performance milestones.
- Medium term (late‑2026 into 2027): Scale modular installations in prioritized facilities; implement workforce upskilling and digital metrology tools; shift purchasing to multi‑year capacity contracts.
- Longer term (2028+): Consolidate technology roadmaps—evaluate newer PECVD/PVD hybrids and in‑line monitoring to reduce scrap and improve first‑pass yield; consider inorganic growth options once unit economics are proven.
Why PW Consulting’s report is mission‑critical for 2026 decision cycles
Our research blends a sectoral quantitative model (historical 2020–2025 base, 2026–2032 forecast) with operational playbooks and vendor analyses that are directly actionable. The combination of a steady sub‑7% CAGR, regulatory urgency from EPR implementation, and uneven supplier capacity makes 2026 a year where methodical, data‑driven moves will secure competitive advantage across the entire packaging value chain.
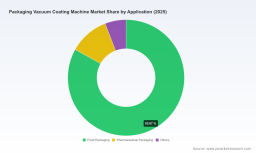
We intentionally present strategic insights and operational tools here while reserving detailed segmentation tables and granular regional & application revenue slices for the full report. Those sub‑segment breakdowns—along with downloadable financial models, supplier scorecards, and step‑by‑step procurement templates—are available through our comprehensive market study.
Next steps
For a tailored briefing or to license the complete dataset and playbooks, contact PW Consulting. Our team can run a focused workshop to map this market’s dynamics directly onto your cost base, product roadmap, and M&A agenda—so the 2026 budget you approve today converts into measurable, risk‑adjusted returns.
For detailed analysis of this topic, please visit the official page: Packaging Vacuum Coating Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com