

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CDR Market to Expand at 16.5% CAGR, Reaching $1,144M by 2032

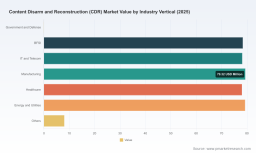
Content Disarm and Reconstruction (CDR) Market 2026 Strategic Primer — Why PW Consulting’s Study Is Essential for Enterprise Decision-Makers
Executive snapshot
As enterprises accelerate digital collaboration and open new file channels, Content Disarm and Reconstruction (CDR) has moved from niche curiosity to core security control. Our PW Consulting market model projects the global CDR market—from a 2025 base—growing from a mid‑hundreds million-dollar market to more than one billion by the end of the 2026–2032 forecast window, at a compound annual growth rate of 16.5% (USD, Million). This trajectory reflects the twin forces of escalating file-based attack sophistication and the broadening endorsement of CDR by authoritative controls frameworks and agencies.
Content Disarm and Reconstruction (CDR) Market
Why this matters for 2026 decisions
For boards, CISOs, procurement teams and security architects planning 2026 budgets and transformation waves, the question is no longer whether to consider CDR but how and where to operationalize it. Our report is designed as a strategic compass: it translates macro momentum into concrete options for technology selection, procurement timing, integration sequencing and compliance mapping. With market concentration indicating meaningful vendor scale yet room for differentiated specialists (CR3 ~45%, CR5 ~65%), decision-makers must balance the stability of established vendors with the innovation edge of focused CDR players.
Content Disarm and Reconstruction (CDR) Market
Context: policy, standards and market drivers
CDR adoption is being accelerated by an ecosystem of policy and guidance. Prominent security authorities and analysts now list CDR as a recommended control; government and national guidance has increasingly aligned on the role that sanitization technologies play in a zero‑trust posture. Notably, NIST finalized Release 5.2.0 of SP 800-53 in August 2025, updating control requirements that affect data handling and inspection choices. In parallel, defense procurement traces—such as DoD APL certification activity and STIG testing—have begun to validate CDR capabilities for high-assurance environments. These endorsements reduce procurement friction for security teams and raise expectations for vendor proof points.
Content Disarm and Reconstruction (CDR) Market
What PW Consulting’s report delivers (practical, procurement-ready content)
- Actionable buyer’s guide: prioritization frameworks that translate use‑case risk into purchase and deployment sequencing for email, web gateways, file transfers and endpoint channels.
- Deployment playbooks: step‑by‑step orchestration patterns for cloud-first, hybrid and air‑gapped environments, including integration notes for mail proxies, secure web gateways, DLP and CASB fabrics.
- Proof‑of‑Concept (PoC) templates and test plans: measurable acceptance criteria and malware/format test-cases to accelerate vendor evaluation cycles.
- ROI and TCO models: configurable spreadsheets calibrated to industry threat profiles and channel volumes to support budget requests and business‑case narratives.
- Compliance and control mapping: direct crosswalks to NIST SP 800‑53, NSA/ISG guidance and analyst best practices, including notes on federal certification pathways.
- Vendor due diligence checklist: legal, technical, operational and M&O (management & operations) questions tailored for strategic sourcing and long‑term partnerships.
- Integration matrix and architecture patterns: concise guidance on inline vs. out-of-band deployment, latency management, file fidelity expectations and telemetry requirements.
- M&A and go‑to‑market implications: for security vendors and service providers evaluating entry strategies—product bundling, channel playbooks and managed‑service accelerants.
The report intentionally abstracts detailed segment outputs in this primer to protect the competitive intelligence that will be available in the full market package. Think of this article as the trailer: it surfaces the strategic signals and operational levers, while the full dataset, regional breakdowns and vendor scorecards are available in the source study.
Competitive landscape — vendor positioning and strategic implications
The CDR competitive set includes platform incumbents, focused pure‑plays and security giants integrating CDR into broader suites. Our analysis emphasizes functional differentiation (sanitization method, channel coverage, throughput and enterprise integration) rather than vendor rhetoric.
- OPSWAT (MetaDefender, Deep CDR™): OPSWAT’s technology emphasizes deep file sanitization within an established multi‑tool hygiene platform. Their value proposition centers on critical‑infrastructure workflows and multi‑engine inspection, making them a frequent contender where layered defense and legacy ecosystem compatibility matter.
- ReSec Technologies (ReSecure): ReSec positions itself with an intelligent file firewall and real‑time CDR for zero‑trust gateways. The strength here is in low-latency filtering and an appliance-to-cloud portfolio that suits organizations focused on inline gateway sanitation without large user‑experience tradeoffs.
- Menlo Security (Positive Selection® CDR, post‑Votiro): Menlo’s browser and enterprise workspace focus, combined with Positive Selection® CDR, targets organizations prioritizing web isolation and workspace file hygiene—particularly those migrating to remote or hybrid endpoint models.
- SASA Software (GateScanner): SASA’s GateScanner is tailored for multi‑channel sanitization and secure cross‑domain transfers. Its strengths are in environments where strict domain separation and secure file transfer are non‑negotiable—think industrial, government and high‑assurance enterprises.
- Glasswall (Halo CDR Platform): Glasswall markets defense‑grade file protection and curated zero‑trust filtering capabilities. Their approach aligns closely to inspection and sanitization guidance from national agencies, making them attractive for organizations with rigorous compliance needs.
- Everfox (Zero Trust Threat Removal CDR): Rebranded from established government‑oriented units, Everfox focuses on threat removal in high‑assurance contexts. Their heritage provides credibility for federal and regulated buyers seeking long‑term support pathways.
- Fortinet (FortiGuard CDR integrated into FortiProxy, FortiGate, FortiMail): Fortinet’s integration story is compelling for customers already entrenched in its security fabric. With certification activity that includes DoD APL/STIG testing trails, Fortinet offers a pragmatic route to CDR via consolidated vendor management and unified policy controls.
Across vendors, differentiation clusters around: sanitization fidelity vs. file utility preservation; inline latency and UX; channel breadth (email, web, FTP, removable media); and enterprise integration (SIEM, XDR, DLP). Buyers must weigh whether their primary objective is maximal threat removal (highest sanitization rigor) or minimal business friction (file fidelity and user experience).
Strategic recommendations for enterprise stakeholders
- CISOs: Map CDR to your highest‑risk data ingress/egress channels and prioritize pilots where regulatory expectations and threat likelihood overlap. Use the report’s compliance crosswalks to accelerate audits and certification conversations.
- Security architects: Start with architecture patterns in the playbook—evaluate inline vs. out‑of‑band choices against latency SLAs and telemetry needs. Plan for logging and forensic visibility so sanitized files remain actionable in investigations.
- Procurement & sourcing: Use our PoC templates and vendor due diligence checklists to shorten RFP cycles and reduce negotiation friction. Consider managed service models for operational maturity bottlenecks.
- Line‑of‑business leaders: Factor in user experience: where possible, pilot on low‑friction channels first to build organizational momentum and reduce resistance to stricter channels later.
- Service providers and MSSPs: Position CDR as a managed capability bundle—customers increasingly prefer outcome guarantees (reduced breach risk, compliance evidence) over stand‑alone licensing.
Timing and procurement cadence for 2026
Given the projected CAGR and policy alignment, 2026 is a window of rapid adoption. Early adopters that finalize architecture and procurement in the first half of 2026 can capture vendor attention for favorable commercial terms and influence roadmap priorities. Conversely, late movers should expect a more consolidated vendor landscape and accelerated feature standardization—raising the bar for differentiation but simplifying long‑term support considerations.
Conclusion — the strategic signal
CDR is no longer an experimental control; it is part of the mainstream defensive toolkit recommended by analysts and standards bodies. PW Consulting’s market model and playbooks convert that macro signal into operational decisions—what to pilot, how to integrate, and which vendor archetypes to prefer given your risk posture and operational constraints. This primer outlines the strategic framing; the full report provides the granular segmentation, vendor scorecards, pricing artifacts and regional market data that procurement, architecture and compliance teams need to execute with confidence.
Next steps
For enterprise teams ready to move from strategy to execution, download the complete PW Consulting Content Disarm and Reconstruction Market study for detailed segmentation, prioritized vendor shortlists and the suite of operational templates that accelerate procurement and deployment.
For detailed analysis of this topic, please visit the official page: Content Disarm and Reconstruction (CDR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com