

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Suspension Spring Market to Reach USD 18,480.7M by 2032, 4.8% CAGR

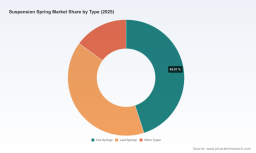
Suspension Spring Market — Strategic Preview for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a strategic preview of our forthcoming Suspension Spring Market research — a must-read for executives, corporate development teams, and product leaders preparing decisions in 2026. This preview synthesizes the report’s most consequential, decision-ready insights while deliberately reserving detailed subsegment tables and regional/application splits for the full report. The aim: demonstrate analytical depth and practical value while guiding you to the complete study for the granular inputs required to execute with confidence.
Suspension Spring Market
Macro frame: What the numbers tell us
The suspension spring market has entered a steady expansion phase. Using 2025 as the base year, our historical series (2020–2025) shows a clear recovery and structural growth, with overall market value rising from the lower end of the last decade to USD 13,352.55 Million in 2025. Under our central forecast, the market grows at a compound annual growth rate (CAGR) of 4.8% through the 2026–2032 forecast window, reaching an estimated USD 18,480.69 Million by 2032. These macro dynamics underline a business environment in which incremental demand, material and technology shifts, and aftermarket opportunities cumulatively create a multi-year runway for both OEM and supplier strategic initiatives.
Suspension Spring Market
Why this matters for 2026 strategic planning
- Resource allocation and CAPEX planning: A mid-single-digit CAGR over the forecast period signals that capital deployed now — for capacity upgrades, automation, or new material lines — can expect steady payback windows compared with cyclical segments of the broader automotive value chain.
- Portfolio and product prioritization: Market expansion is not uniform: performance requirements, vehicle electrification, and payload shifts in commercial vehicles are reshaping demand profiles. Suppliers must prioritize R&D and platform investments that align to emerging load cases and NVH (noise, vibration, harshness) expectations.
- Supply-chain resilience: Steel and specialty alloys remain core to most suspension spring solutions. The industry’s sensitivity to raw-material variability and fatigue performance means procurement strategy — long-term contracts, secondary sourcing, and vertical integration — will materially affect margins and service levels.
- Commercial strategy: OEM program wins, aftermarket penetration, and geographic footprint decisions made in 2026 will determine access to the growth implied by our forecast through 2032. Speed-to-market on EV-specific spring designs is particularly critical.
Industry dynamics shaping the next planning cycle
Two technical/macroeconomic currents are defining near-term industry moves:
Suspension Spring Market
- Fatigue and metallurgical engineering constraints: PatSnap and recent patent literature indicate that surface-initiated fatigue is the dominant failure mode for high-strength steel coil springs operating above tensile strengths of ~1800 N/mm². This elevates the importance of surface engineering (shot peening, coatings, micro-geometry control) and OEM qualification processes. Suppliers that can demonstrate superior fatigue life through validated test methods will command pricing power and program preference.
- Lightweighting and materials migration: Industry data from 2025 show lightweight materials (advanced high-strength steels, microalloyed steels, and selective aluminum/composite hybrids) are enabling suspension architectures that reduce vehicle mass and emissions. This creates two parallel opportunities: (a) premium engineering and development revenue streams for materials transition, and (b) a cost-and-capex challenge for producers that must retool or add capabilities to process new material classes.
What our full report contains — a practical roadmap
The complete Suspension Spring Market report is structured to be immediately actionable for corporate strategy and business-unit teams. Highlights include:
- Validated market sizing and forecasting model: Historical (2020–2025) reconciliation and scenario-based forecasts (2026–2032) with demand drivers mapped to vehicle production forecasts, EV penetration scenarios, and aftermarket replacement cycles.
- Supply-chain and cost sensitivity analysis: End-to-end input-cost modeling for steel and specialty materials, labor and energy inputs, and an analysis of pass-through mechanisms under different pricing regimes.
- Technology and product roadmap: Comparative assessment of coil, leaf and parabolic spring technologies, plus emerging hybrid-material concepts, with R&D investment benchmarks and time-to-OEM-certification expectations.
- Factory footprint optimization tool: A decision framework for capacity location, transfer pricing, and localized sourcing vs. centralized manufacturing including labor productivity indices and freight-cost break-even maps.
- Commercial playbooks: Go-to-market templates for OEM program capture, aftermarket channel expansion, and tier-1/tier-2 supplier partnership structuring.
- M&A and partnership screen: A curated list of acquisition targets and JV partners matched to capability gaps (materials processing, surface-treatment, digital test capabilities) and prioritized by synergy potential and integration risk.
- Risk scenarios and mitigation options: Stress-testing for raw-material shocks, trade-policy shifts, and EV adoption inflection points, with prescriptive mitigation roadmaps.
Note: This preview intentionally omits the granular regional and application splits contained in the full report. Those subsegment tables and the underlying assumptions are critical inputs for program-level decisions and are available only in the complete study.
Competitive landscape — actionable implications
The suspension spring supplier universe is characterized by a mix of global specialists, regional leaders, and high-performance niche players. Market concentration remains modest: the top three firms account for under one-quarter of market value and the top five capture a little more than a quarter, indicating a fragmented market with room for consolidation and value creation through scale and capability differentiation.
- Global OEM-focused leaders: Companies with deep OEM relationships and global engineering footprints (e.g., NHK Spring, GKN Automotive, Mubea) are positioned to win platform-level specifications, especially where integrated spring systems or assembly-level supply is required. Their strengths lie in engineering pipelines, ISO-grade testing labs, and program-management discipline.
- Full-line and specialty manufacturers: Firms such as Sogefi and Lesjöfors combine breadth across passenger and commercial applications with the ability to serve specialty segments (motorsports, aftermarket). They often compete on integrated service levels and product customization.
- Heavy-duty and regional specialists: Producers focused on heavy-truck and commercial vehicle springs (Hendrickson, Rassini, Betts) benefit from higher part-value and longer program lifecycles. Their strategic playbook emphasizes parabolic and multi-leaf technologies and aftermarket service networks.
- North America-focused precision and aftermarket players: A cluster of precision coil and aftermarket suppliers (e.g., Betts Spring, Draco, R‑R Spring, Coiling Technologies, WCS, FCS Automotive, H&R, Eibach) compete on lead time, custom engineering, and performance tuning — attractive targets for OEMs seeking nimble partners or for larger suppliers seeking bolt-on capabilities.
Strategic implications for 2026:
- OEM program capture will depend on demonstrable fatigue-life improvements and the ability to validate surface-treatment processes under EV-specific load cycles.
- Scale remains a differentiator where global sourcing and logistics complexity matter; however, niche capabilities (e.g., high-performance coatings, parabolic leaf expertise) command premium margins and defensive positions.
- Consolidation opportunities exist for buyers seeking to expand into aftermarket channels or to acquire specialty material-processing capabilities without starting from scratch.
How to use this preview and next steps
PW Consulting’s full report is designed to support the following decision workflows in 2026:
- Board-level capital allocation: Use our forecast scenarios to stress-test capacity investments and to set hurdle rates for greenfield vs. brownfield projects.
- M&A diligence: Leverage our supplier scorecards and synergy metrics to refine target lists and to prioritize integration workstreams.
- Product roadmap prioritization: Align R&D spend to material and fatigue-engineering gaps highlighted in the report; adopt our certification timelines for program-level commitments.
- Sourcing and procurement strategy: Implement hedging and supplier-partner frameworks informed by our raw-material sensitivity and regional sourcing models.
- Commercial and aftermarket expansion: Apply our channel-play templates to secure higher-margin replacement business while protecting OEM program throughput.
Concluding recommendation — where to focus in 2026
For executives planning actions in 2026, priority should be given to three correlated moves: (1) accelerate material- and surface-engineering capabilities to address fatigue-life constraints; (2) rationalize manufacturing footprints to balance cost, service, and EV-specific technical requirements; and (3) pursue targeted acquisitions or partnerships that close capability gaps quickly (e.g., coating technologies, fatigue-testing labs, or aftermarket distribution networks). The market’s steady 4.8% CAGR through 2032 provides a supportive macro backdrop for these investments — but success will hinge on execution discipline around certification timelines and supplier integration.
This preview demonstrates the strategic contours you need to act now. For the complete dataset, granular regional and application splits, supplier scorecards, and our executable playbooks, consult the full Suspension Spring Market report available from PW Consulting.
For detailed analysis of this topic, please visit the official page: Suspension Spring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com