

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Residential Solar Storage to Hit USD 525.8M by 2032

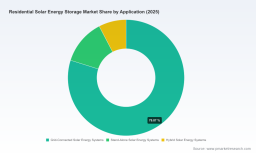
Residential Solar Energy Storage Market 2026: Strategic Imperatives for Corporate Decision‑Makers
PW Consulting’s latest market study on Residential Solar Energy Storage synthesizes five years of historical dynamics (2020–2025) and a forward-looking forecast horizon (2026–2032) to equip executive teams with the actionable intelligence required to make high‑stakes 2026 decisions. The market has scaled meaningfully—from a six‑figure base in 2020 to an estimated USD 161.0 Million in 2025—and, under current trajectories, is forecast to expand to roughly USD 525.8 Million by 2032 at a compound annual growth rate of 18.5%. Those headline numbers frame a capital‑intensive, fast‑growing opportunity space where timing, partner selection, and regulatory positioning will determine competitive advantage.
Residential Solar Energy Storage Market
Why this research matters now
-
Acceleration and optionality: The industry is transitioning from early adopter deployments to mainstream residential programs, with volume-led economics and new revenue streams (virtual power plants, demand response) emerging in parallel. PW’s study decodes where and how that acceleration will be monetized over the next seven years.
Residential Solar Energy Storage Market -
Policy and incentive sensitivity: Recent policy levers—most notably domestic content incentives introduced in 2025—change the calculus for supply‑chain localization and capex planning. The report models multiple policy scenarios so commercial teams can stress‑test propositions against incentive cliffs and bonus adders.
Residential Solar Energy Storage Market -
Operational complexity: Falling component costs, installer labor constraints, and evolving interoperability standards are squeezing traditional margins while creating differentiation pathways for firms that can optimize for installability, warranty economics, and software‑enabled services.
What the report contains: practical, executable modules
This study was structured as a practitioner’s toolkit rather than a purely academic exercise. Key deliverables include:
-
Robust market sizing and forecast engine: Transparent methodology and scenario variants that explain the drivers behind the baseline 18.5% CAGR and the sensitivities that could accelerate or decelerate growth.
-
Go‑to‑market playbooks: Channel segmentation, installer economics, and customer acquisition cost models for different North‑American and international archetypes (high‑solar, high‑outage, or incentive‑driven markets).
-
Technology and product roadmaps: Comparative assessment of battery chemistries, inverter architectures, and battery management systems—highlighting tradeoffs in cost, safety, cycle life, and integration complexity.
-
Supply‑chain and procurement playbook: Component sourcing strategies, BOM optimization levers, and a supplier scorecard to prioritize negotiations and hedging tactics under material‑price volatility.
-
Revenue stacking and VPP modeling: Practitioner templates for stacking resiliency, time‑of‑use arbitrage, demand response, and aggregated resource revenues—incl. sample P&L and cashflow timelines for pilot projects.
-
M&A and partnership blueprint: Valuation comparables, integration checklists, and cultural fit diagnostics for acquiring system integrators, battery OEMs, or software specialists.
-
Implementation checklists and KPI dashboards: Installer training programs, commissioning protocols, and a dashboard framework for monitoring margin, churn, and field reliability.
Competitive landscape — high‑level synthesis and what to watch in 2026
The market is dynamically competitive: global OEMs with strong brand equity coexist alongside nimble regional manufacturers and specialty system integrators. The top firms collectively account for less than one‑third of industry revenue, indicating meaningful fragmentation and room for both consolidation and niche plays.
-
Tesla (Austin, Texas) — Powerwall remains the de facto reference product. Tesla’s strengths are vertical integration, brand recognition, and a software layer that ties storage into vehicle and grid strategies. For incumbents, Tesla sets baseline expectations on warranty, UX and whole‑home backup performance.
-
Enphase Energy (Fremont, California) — Enphase’s microinverter‑centric platform and modular IQ Battery family targets homeowners seeking simple, incremental storage. Its July 2025 product refresh underscores Enphase’s strategy to couple smarter metering and easier integration with existing solar arrays.
-
FranklinWH Energy Storage (U.S.) — FranklinWH’s 2025 RE+ introductions, including retrofit‑friendly solutions and the aPower S hybrid system, highlight an emphasis on retrofit market share and installer convenience—two zones of growth often underserved by larger OEMs.
-
Sigenergy (China) — Recent module expansions unveiled at RE+ 2025 demonstrate an approach that leverages modular stacking for capacity flexibility—appealing to larger homes and small commercial conversions.
-
EG4 Electronics, Fox ESS, Sol‑Ark, Lunar, Bluetti, Duracell Energy — These firms occupy differentiated positions from low‑cost modular offerings and portable systems to AI‑driven whole‑home solutions and trusted consumer brands. Their continued innovation at trade shows and targeted product launches keeps price and feature competition intense.
Recent product introductions at RE+ 2025 and targeted launches during 2025–2026 show the market moving from single‑product shelfplays to portfolios that emphasize retrofit ease, modular scaling, and software integration. Good strategic questions for 2026: do you compete on price, on installer economics, or on software/service monetization?
Supply‑chain and cost dynamics
The structural decline in battery pack prices over the past 24 months has been a powerful tailwind, and deployment volumes are expanding rapidly—residential storage deployments reached multiple gigawatt‑hours in 2025 with annual growth measured in tens of percent year‑over‑year in many markets. At the same time, new domestic content incentives have reweighted supplier selection and capital allocation decisions toward local cell and component sources.
The combined effect: margin compression on commoditized system components, paired with an opportunity to capture premium value through installation efficiency, warranty optimization, and recurring service revenues (maintenance, VPP participation, optional extended warranties).
Strategic plays recommended for 2026
-
Localize selectively: Prioritize component localization in markets where domestic content incentives materially increase net contract value. Use a two‑tier sourcing strategy—localized cells where incentives apply, global suppliers for balance‑of‑system to retain price flexibility.
-
Design for install economics: Reduce field labor time through pre‑assembled racks, simplified wiring, and installer training programs tied to revenue‑sharing incentives. Faster installs materially improve unit economics for both OEMs and installers.
-
Monetize software: Build or partner for energy‑management platforms that enable VPP participation and revenue stacking. Software margins can offset hardware commoditization and improve customer lifetime value.
-
Target retrofit niches: Retrofit‑friendly systems and hybrid inverters unlock large addressable pools of existing solar homes seeking resiliency without full re‑designs. This is a defensible niche against big‑box OEMs focused on new installs.
-
Use M&A tactically: Acquire small integrators or BMS specialists to accelerate field presence, add IP, or secure installer networks—focus on fast integration and clear cross‑sell pathways.
-
Operational resilience: Hedge supplier risk, maintain strategic inventory buffers for key components, and embed scenario planning into procurement cycles to mitigate episodic price volatility.
How PW Consulting can accelerate your 2026 plan
PW Consulting offers a modular engagement model to turn insights into execution: tailored market entry playbooks, end‑to‑end financial models linked to customer lifetime economics, supplier negotiation support, pilot program design for VPP proof‑of‑value, and M&A diligence packages that include technology validation and field reliability tests. For companies preparing board materials, our executive snapshot condenses the investment thesis, downside scenarios, and prioritized next steps into a single two‑page decision memo.
Note: this article intentionally highlights strategic themes and headline market sizing to demonstrate the research’s depth. Core segmented models (regional and application splits, product‑level price decks, installer micro‑economics and granular CRx tables) are reserved for the full report. For access to the detailed tables, segmented forecasts, and downloadable financial templates that support actionable implementation in 2026, please consult the full PW Consulting Residential Solar Energy Storage Market report.
In a market growing at an 18.5% CAGR from a USD 161.0 Million base in 2025 toward a multi‑hundred‑million dollar opportunity by 2032, the right combination of product design, policy positioning, and channel execution will determine who captures the most value. 2026 is not a transition quarter—it is a strategic inflection point. PW Consulting’s study is designed to make those choices faster, clearer, and defensible.
For detailed analysis of this topic, please visit the official page: Residential Solar Energy Storage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com