

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Biostimulants Market to Reach USD 8.02 Billion by 2032 at 10.85% CAGR

Biostimulants Market 2026: Strategic Preview for Executive Decision-Making
Executive snapshot
As the agricultural input landscape shifts from yield-maximization to resilience and input-efficiency, the biostimulants market is entering a decisive growth phase that will re-shape portfolio priorities, channel strategies, and M&A pipelines through the late 2020s. PW Consulting’s upcoming Biostimulants Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market trajectory, regulatory inflection points, competitive capabilities, and field-proven performance signals into a single, execution-focused playbook tailored for leadership teams making 2026 investment and commercialization choices.
Biostimulants Market
Why this matters for 2026 strategic choices
-
Timing of scale. The market is not only expanding but accelerating: a compound annual growth rate (CAGR) of approximately 10.85% projects the global market from roughly USD 3.89 Billion in 2025 to just over USD 8.0 Billion by 2032. That growth window (2026–2032) is precisely the window when product portfolios and channel footprints will either capture durable share or be relegated to niche positions.
Biostimulants Market -
Commercial readiness versus scientific proof. Buyers—particularly large distributors and integrated agri-businesses—are shifting procurement from “novel promise” to “documented ROI.” Certification programs and high-resolution field data are rapidly becoming purchase prerequisites, raising the bar for new entrants and incumbent product upgrades.
Biostimulants Market -
Regulatory consolidation creates both risk and opportunity. Emerging regulation and definitions are re-aligning market access criteria. Companies that act early to harmonize claims, labeling and compliance will face lower friction when scaling internationally; laggards will face market access constraints and higher go-to-market costs.
Market trajectory: data-driven view (what the numbers imply)
Between 2020 and 2025 the market grew from roughly USD 2.55 Billion to approximately USD 3.89 Billion, reflecting steady adoption among commercial row-crop and high-value horticulture producers. Our forecast indicates an inflection point from 2026 onward, with projected acceleration to about USD 8.02 Billion by 2032 at a ~10.85% CAGR. That rate of expansion implies three structural realities for decision-makers:
-
Scale economics will matter faster than in legacy inputs. At this CAGR, absolute market expansion supplies room for specialized, higher-margin technologies, but also favours players capable of rapid distribution scale and consistent quality control.
-
Channel competition will intensify. Distributors, fertilizer players, and crop protection incumbents will increasingly seek exclusive supply or co-branded offerings to secure share of the expanding market—creating consolidation pressure and strategic partnership opportunities.
-
Fragmentation remains meaningful. Despite consolidation among top players, market concentration metrics indicate that the top few players collectively capture under a majority share—creating room for differentiated specialists, regional champions, and technology-driven disruptors.
Competitive landscape — what capabilities win
The competitive map is diverse: coastal and marine innovators, microbial specialists, traditional fertilizer groups extending into biostimulants, and ag-biotech firms combining biologicals with precision agronomy. Our analysis highlights capability clusters that correlate with commercial success:
-
Proprietary raw-material platforms: Companies with secure access to consistent, traceable marine or microbial feedstocks and the biochemical know-how to standardize extracts are advantaged for larger-scale contracts and repeatable efficacy.
-
Field-proven efficacy and agronomic services: Firms that couple products with trial data and agronomic support create stronger adoption curves in enterprise accounts and cooperative networks.
-
Distribution partnerships and integration with input suites: Alliances with major fertilizer and crop protection distributors enable rapid channel penetration while raising competitive barriers for new entrants.
Representative players we profile in the report include seaweed-extract leaders, microbial specialists, and integrated biologicals companies—each with distinct go-to-market models, proprietary inputs, and scaling strategies. For executives evaluating partner or acquisition targets in 2026, our competitive profiles distil strategic fit beyond marketing claims into operational readiness, IP position, manufacturing scale, and channel access.
Regulatory and certification dynamics — near-term implications
-
Regulatory harmonization is underway in major markets. Recent activity in the EU and the U.S. is clarifying definitions, labeling requirements, and the boundary between biostimulants and plant regulators. Firms must allocate resources to compliance documentation and labeling updates to avoid market interruptions.
-
Certification programs are becoming procurement filters. Independent and industry-run certifications now require efficacy documentation that increases upfront development costs but materially reduces buyer friction. This elevates the importance of robust trial design and third-party validation in commercialization strategies.
-
Policy-driven partnerships create distribution leverage. Established agrochemical and fertilizer groups are incorporating biostimulant lines into their biosolutions portfolios through distribution agreements and co-development, altering competitive dynamics in favor of partners with near-term manufacturing capacity and consistent quality systems.
Recent market signals worth strategic attention
-
Field performance matters: Recent field trials released by industry players have reported step-change yield and quality improvements in specific high-value crops—data points that buyers use to justify premium placement in cropping plans.
-
Major product and distribution moves: New product launches and distribution agreements by large ag companies indicate willingness to invest in biostimulants as core elements of future BioSolutions portfolios. These moves accelerate market professionalization and customer expectations around supply assurance.
-
Standardization and certification continue to advance: Industry certifications and regulatory clarifications are tightening the marketplace and favoring vendors who can demonstrate traceability, safety, and repeatable agronomic benefits.
What PW Consulting’s full report delivers (operative content, not just high level)
Our report is structured to be decision-ready for 2026 strategy cycles. Key deliverables include:
-
Actionable market model: A calibrated market-sizing model (historical 2020–2025; forecasts 2026–2032) with scenario levers for adoption speed, channel penetration, and regulatory impact—built to be re-used in internal investment cases.
-
Go-to-market playbooks: Evidence-based channel strategies for seed, foliar and soil approaches, plus distributor segmentation and partner evaluation criteria.
-
Regulatory and certification checklist: Country-specific steps, timelines, and common failure modes for claims, labeling and documentation—designed to reduce time-to-market by eliminating common delays.
-
Product development KPIs: Trial design standards, recommended endpoints for ROI calculations, and benchmark efficacy metrics to support premium pricing and channel placement.
-
M&A and partnership diagnostics: A framework for target screening including manufacturing footprint, raw material security, IP defensibility, and commercial scalability—with red flags and integration templates.
-
Competitive profiles and supplier matrix: Independent assessments of leading and fast-growing players across capability dimensions—useful for supplier selection, co-development scouting, or acquisition prioritization.
How executives should use this research in 2026
-
Portfolio allocation: Re-prioritize R&D and commercial spend toward formulations and service bundles that demonstrably reduce grower risk or input cost—translate the report’s KPI benchmarks into go/no-go gates for pipeline projects.
-
Channel moves: Use our distributor and partner diagnostics to evaluate whether to pursue exclusive regional agreements, co-development with fertilizer majors, or direct-to-farmer models that combine products with agronomy services.
-
M&A and alliances: Apply the M&A diagnostic to shortlist targets that close capability gaps quickly—especially manufacturing scale, raw-material security (marine or microbial), and validated trial data.
-
Compliance and labeling: Accelerate compliance projects to align with evolving definitions and certification expectations; a small early investment in documentation will reduce time-to-revenue in major markets.
Closing — the strategic imperative
By 2026, biostimulants will no longer be a peripheral product category: they will be a core component of resilient, input-efficient cropping systems and a strategic lever for companies seeking differentiated value propositions in a tightening regulatory and buyer environment. The market’s projected growth (from roughly USD 3.89 Billion in 2025 to just over USD 8.0 Billion by 2032 at a ~10.85% CAGR) creates both urgency and opportunity. Companies that pair rigorous field evidence, compliant labeling, and channel scale will capture the disproportionate gains; those that treat biostimulants as an experimental line risk being outmaneuvered.
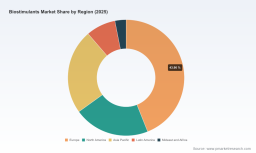
PW Consulting’s full Biostimulants Market report provides the granular subsegment analysis, regional breakdowns, and company-level valuation matrices needed to operationalize the strategic imperatives outlined here. This preview shows where value will be created and where risk is concentrating—reach out to access the complete dataset, scenario models, and prescriptive playbooks tailored for your 2026 decision cycle.
For detailed analysis of this topic, please visit the official page: Biostimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com