

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MS Polymer Hybrid Adhesives & Sealants to reach USD 219.41M by 2032 (8.1% CAGR)

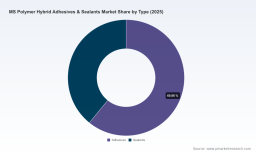
MS Polymer Hybrid Adhesives & Sealants Market — Strategic Outlook for 2026
As PW Consulting’s lead industry analyst, I present a condensed strategic primer on the MS polymer hybrid adhesives & sealants market designed to orient executive decision-making for 2026. This market is moving from a phase of steady recovery into structural acceleration. Our full MS Polymer Hybrid Adhesives & Sealants Market study (base year 2025) quantifies that trajectory and couples it with executable commercial playbooks and risk-mitigation toolkits. Below, we surface the high‑conviction forces and the operational levers that matter most — while preserving the granular segmentation and proprietary analytics locked inside the full report.
MS Polymer Hybrid Adhesives & Sealants Market
Why this study matters for 2026 decisions
Two headline facts set the strategic frame: the global MS polymer hybrid market reached a material commercial scale in our 2025 base year (reported at USD 127.86 Million), and our forecasting framework projects a robust compound annual growth rate of roughly 8.1% through the 2026–2032 horizon. By 2032 the market is expected to be substantially larger than today. That growth cadence is meaningful — it implies expanding addressable demand across construction, transportation, and industrial assembly and creates windows to capture share through differentiated product, localized supply, and commercial innovation.
MS Polymer Hybrid Adhesives & Sealants Market
Executives must therefore treat 2026 as a pivot year: a time to move beyond defensive cost-control toward targeted investment in product differentiation, supply resilience, and commercial models that monetize sustainability and compliance advantages.
MS Polymer Hybrid Adhesives & Sealants Market
What the report delivers — practical, decision-ready assets
- Market sizing and multi-scenario forecasts (base, upside, downside) with financial implications to 2032 — enabling capex and revenue planning.
- Demand-driver analysis that isolates secular trends (e.g., low‑VOC regulation, electrification of transport, modular construction) from cyclical noise.
- Raw-material cost sensitivity models and stress tests showing P&L impact under realistic silane, catalyst and freight scenarios.
- Competitive benchmarking and supplier scorecards for global players and regional specialists — aligned to capability, channel access and innovation pipeline.
- Commercial playbooks: pricing architecture, contract wording for cost pass-through, channel incentive templates and launch playbooks for new formulations.
- M&A and alliance heat maps that identify high-probability bolt‑on targets and strategic partner archetypes.
- A risk register and mitigation roadmap covering geopolitics, input shocks, regulatory shifts and substitution threats.
Each deliverable contains templates and executable steps — not just descriptive analysis. The report is structured to be used in board-level strategy sessions, sales planning workshops and procurement renegotiations.
Market dynamics shaping strategy in 2026
The near-term commercial picture is being rewritten by a few converging dynamics that every strategy, procurement and R&D function must integrate:
- Raw‑material volatility: Key feedstocks such as silanes and precious-metal catalysts have shown elevated price swings and constrained availability. Notably, major suppliers announced multi‑month price uplifts in 2026 in response to cost inflation and supply-chain distortions. These dynamics increase working-capital strain and compress margins where indexation and long-term procurement are weak.
- Regulatory momentum toward low‑emission chemistries: Moisture‑curing MS hybrids emit no VOCs or isocyanates, positioning them advantageously as regulations tighten across construction and transportation. That shift revalues formulations and creates premiumization opportunities if supported by validated compliance claims and certifications.
- Product innovation and specification pulls: Flame‑retardant grades and specialty hybrids for rail and e‑mobility are entering procurement specifications, which elevates the importance of formulation expertise and testing capabilities.
- Geopolitical and logistics friction: Energy market instability and regional conflicts have amplified freight and input-price volatility, creating asymmetric cost shocks across regions — a structural reason to reassess localization and dual‑sourcing strategies.
- Fragmented commercial structure: Market concentration is moderate — the largest three players account for roughly a quarter of supply, leaving ample room for regional champions and specialist entrants to win sustainable niches through service, formulation depth or localized supply.
Competitive landscape — strategic implications for incumbents and challengers
The competitive landscape blends global diversified adhesives majors, specialized polymer producers and regionally focused manufacturers. Strategic positioning differs materially across these groups:
- Global diversified players (e.g., well‑known multinational adhesives brands): They leverage broad channel networks, specification influence with OEMs and the ability to cross‑sell into adjacent construction and industrial portfolios. Their edge is scale, certification footprints and route-to-market depth.
- Polymer and resin producers (vertical suppliers): Firms that produce base resins exert upstream pricing power and can integrate innovation faster; their moves on feedstock pricing cascade through the value chain and directly affect contract negotiation dynamics.
- Regional champions and specialty formulators: These players win on responsiveness, local approvals and tailored formulations for region-specific substrates and climates. They can outcompete on speed-to-spec and localized service models.
- Emerging industrial players and niche innovators: Smaller manufacturers and technology-focused firms often drive formulation breakthroughs (e.g., low‑temperature cure, flame resistance) and can be attractive M&A targets for scale players looking to accelerate capability acquisition.
Recent moves in the market illustrate these dynamics. Some manufacturers have expanded proprietary MS platforms into new end-markets, while upstream producers have announced price adjustments tied to raw-material shortages and increased catalyst costs. These events create both headwinds (margin squeeze) and opportunities (recontracting, premiumization) depending on commercial dexterity.
Actionable strategic plays for 2026
Below are high‑priority plays we recommend for executive teams preparing budgets and strategies for 2026:
- Procurement resilience: Implement layered sourcing (global + regional), negotiate limited-term indexed contracts with clear cost‑pass-through triggers, and establish strategic safety stock for critical feedstocks. Leverage our raw-material sensitivity templates to quantify margin exposure.
- Pricing architecture: Move to value‑based pricing for differentiated, low‑VOC and flame‑resistant formulations. Introduce automated escalation clauses for volatile inputs, and deploy tactical promotions in commoditized grades to defend volumes while protecting margin.
- Product and R&D focus: Prioritize formulations that meet tightening regulatory and specification trends (low‑VOC, non‑isocyanate, flame-retardant, faster cure for cold climates). Fast‑track industrial validation programs with key OEMs to embed products in specs.
- Channel & commercial model evolution: Deepen technical selling capabilities with project‑based commercial teams for construction and OEM accounts. Test subscription or service models (e.g., on-site dispensing, application training) that raise entry barriers for competitors.
- M&A and partnerships: Target bolt‑on formulators in high‑growth niches and strategic partnerships with resin producers for preferential feedstock access. Use carve‑outs or minority equity investments to accelerate access to specialized competencies.
- Manufacturing & footprint: Evaluate near‑market micro‑factories or toll‑manufacturing to reduce freight exposure and lead times. Prioritize investments in flexible lines that can run multiple grades to respond quickly to specification changes.
- Regulatory & sustainability roadmap: Invest in certification campaigns (indoor air quality, fire safety) and embed cradle‑to‑gate LCA claims into commercial collateral to capture premium shelf space in specification processes.
How PW Consulting supports your 2026 plan
Our full MS Polymer Hybrid Adhesives & Sealants Market study comes with plug‑and‑play deliverables for strategy teams: an interactive forecast dashboard, supplier and competitor scorecards, raw‑material stress‑test models, a commercial playbook with contract language, and an M&A heat map tuned to strategic and financial criteria. We also provide tailored 90‑day implementation roadmaps to convert strategic choices into measurable actions.
This primer intentionally surfaces the structural forces and executable plays that matter; the full report contains the granular splits, regional and application breakdowns, and proprietary scenario outputs needed to finalize budgets and P&L projections. If your 2026 plan depends on precise segmentation, supplier scoring or a quantified cost‑pass‑through mechanism, the complete dataset and model access are available via PW Consulting’s report portal.
Next steps
Leaders who want to convert 2026’s market momentum into sustainable advantage should prioritize three diagnostic actions this quarter: run a feedstock stress‑test across your product portfolio; map specification exposure among top OEM and contractor accounts; and vet short‑list manufacturing footprint changes through a quick‑win cost-benefit model. PW Consulting can deploy each diagnostic with templated outputs within two weeks to inform your planning cadence.
For board briefings and leadership workshops, our team offers an executive briefing package that distills the study’s strategic implications and turns insights into a prioritized action plan. Access to the full study and tools is available on our report landing page.
For detailed analysis of this topic, please visit the official page: MS Polymer Hybrid Adhesives & Sealants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com