

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Multi-Vendor IT Support Market to reach USD 70.39 Billion by 2032 at 3.28% CAGR

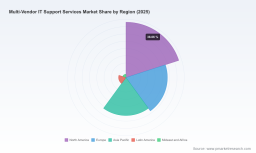
Strategic Preview: Multi‑Vendor IT Support Services Market — What Every Executive Must Know for 2026
As enterprises enter 2026 with renewed focus on resilience, cost control and vendor rationalization, multi‑vendor IT support services have moved from a tactical procurement choice to a strategic capability. PW Consulting’s latest study — using 2025 as its base year and a forecast window through 2032 — synthesizes five years of market behavior (2020–2025) and projects a steady trajectory (3.28% CAGR) toward the end of the forecast period. The market’s scale and growth dynamics make it a material line item for CIO, sourcing and transformation agendas; this preview explains why and how the full report enables better decisions without disclosing the full segmentation payload here.
Multi-Vendor IT Support Services Market
Executive snapshot: market trajectory and structural signal
By 2025 the global multi‑vendor IT support services market had established itself as a multi‑billion dollar sector, rebounding from pandemic‑era shocks and reflecting a mix of digital transformation spending, extended hardware/software lifecycles and growing demand for integrated service delivery models. Our baseline analysis shows the market expanding at a mid‑single digit compound annual growth rate (3.28% CAGR) across the 2026–2032 forecast horizon, with continued upside from service automation, outsourcing of complexity and the increasing cost of in‑house maintenance for heterogeneous environments.
Multi-Vendor IT Support Services Market
Two structural signals stand out: first, the market is meaningfully fragmented — concentration ratios indicate the top three and top five providers account for less than a third of global revenues — creating a fertile landscape for challengers and specialized integrators. Second, regulatory and compliance pressures, particularly in Europe and highly regulated industries, are reshaping vendor selection, contracting and operating models in ways that go beyond price alone.
Multi-Vendor IT Support Services Market
Why this matters for 2026 decision cycles
- Sourcing strategy will determine operational risk. Organizations that commit to single‑vendor lock‑in risk higher support costs and slower remediation across polyglot estates. Multi‑vendor support, when designed correctly, reduces risk but increases contract complexity — a tradeoff that demands a deliberate sourcing playbook.
- Margin and TCO management are shifting. Automation (AIOps, remote diagnostics), outcome‑based SLAs and vendor consolidation exercises are changing the cost base. Procurement teams that ignore service delivery design will lose negotiating leverage.
- Compliance and data residency matter more. GDPR enforcement and sectoral privacy rules (healthcare, banking, life sciences) materially change operational overhead and supplier requirements — particularly for firms operating across European client bases.
- Talent and delivery model choices remain strategic. The balance between onsite, remote and hybrid delivery determines speed, cost and customer experience. The right combination can be a differentiator; the wrong one creates brittle support operations.
What the PW Consulting report delivers (practical, not theoretical)
This study is designed as an execution‑focused toolkit for 2026 planning cycles. Key deliverables include:
- Actionable vendor selection frameworks that align risk appetite, regulatory exposure and total cost of ownership — including procurement scorecards and RFP templates.
- Service delivery trade‑off analyses comparing remote, onsite and hybrid models, with operational KPIs and staffing profiles aligned to each choice.
- TCO and scenario models you can stress‑test against your own asset inventory and contract portfolio; these models are calibrated to the market baseline and forecast trajectory for 2026–2032.
- Contract playbooks for multi‑vendor management: SLA design, escalation ladders, liability carve‑outs and audit/assurance clauses for regulated environments.
- Technology adoption pathways (AIOps, orchestration, remote monitoring) and deployment blueprints that accelerate break‑fix times while reducing repeat site visits.
- Case studies and implementation roadmaps from leading enterprises that demonstrate measurable savings, improved MTTR and compliance outcomes.
We intentionally retain granular regional and segment breakout tables behind the report paywall to preserve proprietary analysis and to drive customized consulting engagements. This preview focuses on the strategic implications you can act on now.
Competitive landscape: who shapes the market and how
The market mix is a blend of global systems integrators, hardware OEMs extending managed services, software/platform incumbents and specialist service providers. Below we summarize the positioning of key players covered in the report; each profile highlights the vendor’s multi‑vendor support proposition and areas of strategic focus.
- IBM Corporation (Armonk, NY — https://www.ibm.com): IBM leverages managed services, cognitive operations and hybrid cloud expertise to offer multi‑vendor support that emphasizes automation and platform interoperability. Strategic M&A has reinforced its mid‑market capabilities.
- Hewlett Packard Enterprise (Houston, TX — https://www.hpe.com): HPE combines hardware lifecycle services with options for third‑party software support partnerships, catering to clients that prioritize integrated infrastructure management across vendor stacks.
- Dell Technologies (Round Rock, TX — https://www.dell.com): Dell’s strength is in device and infrastructure support with global field coverage; its services extend into multi‑vendor orchestration for data center and edge estates.
- Cisco Systems (San Jose, CA — https://www.cisco.com): Cisco focuses on network assurance and multi‑vendor network support, integrating observability with managed remediation for connectivity‑critical environments.
- Oracle Corporation (Austin, TX — https://www.oracle.com): Oracle’s multi‑vendor angle centers on its software stack and cloud services, offering customers alternative support routes that blend proprietary and third‑party capabilities.
- Microsoft Corporation (Redmond, WA — https://www.microsoft.com): Microsoft’s footprint is strongest where cloud and collaboration tooling intersect; its multi‑vendor support often anchors around Azure‑centric estates and hybrid management.
- Fujitsu Ltd. (Tokyo — https://www.fujitsu.com): Fujitsu positions itself as a global integrator with deep systems integration and field services expertise, particularly across manufacturing and public sector clients.
- NEC Corporation (Tokyo — https://www.nec.com): NEC competes on systems integration and telecoms support, offering multi‑vendor services that include strong local/regional delivery meshes.
- Hitachi Vantara (Santa Clara, CA — https://www.hitachivantara.com): Hitachi Vantara ties storage and data platform support to outcome‑based services, appealing to data‑centric organizations seeking vendor‑agnostic management.
- NetApp Inc. (San Jose, CA — https://www.netapp.com): NetApp’s multi‑vendor support emphasizes storage ecosystems and interoperability, combining technical depth with partner networks.
- Atos SE (Bezons, France — https://www.atos.net): Atos is positioned as a European integrator delivering managed services at scale, with a focus on regulated industries and cross‑border delivery.
- DXC Technology (Tysons, VA — https://www.dxc.technology): DXC delivers legacy systems transition and multi‑vendor maintenance services, often working with clients through complex modernization programs.
- Wipro Limited (Bengaluru — https://www.wipro.com): Wipro combines global delivery with remote monitoring and automation to offer flexible multi‑vendor support packages for large IT estates.
- Capgemini SE (Paris — https://www.capgemini.com): Capgemini focuses on transformation‑oriented managed services, marrying consulting and operational delivery for multi‑vendor scenarios.
- Tata Consultancy Services (TCS) (Mumbai — https://www.tcs.com): TCS brings scale and process rigor to multi‑vendor support, emphasizing end‑to‑end orchestration and continuous improvement.
These profiles are complemented in the full report by vendor scorecards, service capability maps and go‑to‑market assessments that support shortlist and proof‑of‑value selection processes.
Recent market moves and regulatory context
Market activity underscores two trends: consolidation/partnerships that expand capabilities, and regulatory friction that increases operating costs for global service providers. Examples we track include corporate transactions and alliances that broaden multi‑vendor portfolios, and public sector and GDPR enforcement that have recalibrated market entry economics in Europe. Notable developments covered in the report include strategic partnerships and acquisitions that reflect vendors’ attempts to close capability gaps in automation, monitoring and third‑party software support.
Additionally, labor market pressures and the hidden costs of managing multiple vendor contracts introduce an operational tax that organizations frequently underestimate. For regulated sectors — healthcare, banking and life sciences — the incremental compliance burden is often the single biggest driver of vendor selection choices.
Strategic playbook for 2026 — immediate actions
- Run a rapid portfolio audit: map support coverage, overlapping contracts and single points of failure. Use our report’s diagnostic checklist to prioritize quick wins.
- Design SLA and assurance standards by risk tier rather than by vendor. Move from transactional to outcome‑based metrics where feasible.
- Pilot automation‑first models for repeatable incidents to reduce onsite costs and validate vendor capabilities before full‑scale rollouts.
- Build a compliance overlay for regulated assets: data handling, residency and audit trails must be contractual obligations, not optional addons.
- Shortlist vendors using a combination of technical depth, local delivery footprint and partnership ecosystems — then test with small PoVs that mirror your most common failure modes.
How to use the full PW Consulting study
This preview is intended to align executive priorities and outline the tangible choices that should land in 2026 sourcing, operating model and transformation plans. The full study contains the proprietary segmentation, regional breakdowns, vendor benchmarking, downloadable TCO models and contract templates that practitioners need to operationalize these insights. For procurement teams, CIOs and transformation leads, the report becomes a practical decision support system that translates market dynamics into contract terms, implementation roadmaps and risk mitigations.
To access the complete data tables, segment‑level analysis and vendor scorecards — including the granular regional and service‑type breakouts not shown here — please visit the PW Consulting report page where the full study and supplemental tools are available.
For detailed analysis of this topic, please visit the official page: Multi-Vendor IT Support Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com