

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ethernet Switches Market Poised for 6.48% CAGR Through 2032 — PW Consulting

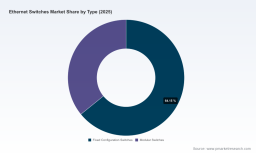
Ethernet Switches Market: Strategic Preview for 2026 Decision-Makers
Executive overview
As enterprises, cloud providers, and industrial operators reassess networking roadmaps in 2026, the Ethernet switches market is both maturing and reconfiguring around a few structural forces: AI-driven data center fabrics, regulatory security baselines, component-level supply fragility, and a new wave of energy- and power-optimized hardware. Our PW Consulting market study — with a base year of 2025, a historical window covering 2020–2025 and forward-looking forecasts to 2032 — quantifies this evolution and translates it into actionable guidance for sourcing, architecture, and M&A decisions.
Ethernet Switches Market
Market trajectory at a glance
The market has expanded steadily from approximately USD 24.3 billion in 2020 to roughly USD 30.8 billion in 2025. Our forecast anticipates continued growth through 2032, reaching an estimated USD 47.5 billion and reflecting a compound annual growth rate (CAGR) of about 6.48% over the forecast period. That growth is not homogeneous — it is concentrated where hyperscale AI, cloud migration, regulatory-driven refresh cycles, and industrial digitalization intersect — creating distinct opportunity pockets and risk clusters for vendors and buyers alike.
Ethernet Switches Market
Why this research matters for 2026 strategy
-
Procurement timing: Lead times and component availability are influencing when to commit to multi-year purchase agreements versus flexible consumption models.
Ethernet Switches Market -
Architecture choices: Decisions between fixed vs. modular platforms, conventional ASIC designs vs. new switch silicon, and open vs. proprietary OS stacks will determine ability to scale and adapt to AI networking demands.
-
Security and compliance: Regulation-driven minimums for managed, segmented, and auditable network infrastructure are turning what were once feature choices into procurement prerequisites.
-
Supplier risk management: Consolidation dynamics and supplier concentration affect bargaining power, warranty exposure, and roadmap transparency.
Key dynamics shaping supplier and buyer behavior
-
AI and hyperscale fabrics: The push to GPU-dense, low-latency fabrics is accelerating demand for ultra-high-performance switching and specialized interconnect topologies. Adoption of new switch silicon and designs purpose-built for AI clustering is a near-term procurement driver for cloud and large enterprise AI initiatives.
-
Regulatory and standards pressure: The EU’s NIS2 directive and IEC 62443 safety/cybersecurity standards have already elevated the procurement bar. Network segmentation, intrusion detection capabilities embedded in Layer 3 managed platforms, and formal firmware-update regimes are moving from “nice-to-have” to RFP minimums.
-
Supply-chain tightness: Concentration in mature-node ASIC supply in 2025–2026 has lengthened lead times for high-throughput switches. Buyers who lock into legacy supply windows without contingency clauses risk delayed deployments; conversely, buyers who design for component flexibility gain negotiating leverage.
-
Energy and power innovation: New power-delivery and semiconductor approaches — including GaN-based PoE++ and more efficient switch power architectures — are creating low-carbon, cost-saving retrofit opportunities for surveillance, transport, and campus networks.
Competitive landscape — what to watch in 2026
The vendor field mixes long-established networking incumbents, silicon-first entrants targeting AI fabrics, and specialist industrial and edge players. Market concentration remains meaningful: the top-three vendors collectively control the majority of supply, while the top-five further increase that share — a dynamic that drives both price discipline and high entry barriers for new, full-stack challengers.
-
Cisco Systems — Continues to leverage a comprehensive portfolio across campus, data center, and industrial segments. For buyers, Cisco remains a safe-bet for integrated security, lifecycle services, and broad channel support, but its roadmaps should be evaluated against alternatives in cost-sensitive and hyperscale AI contexts.
-
Arista Networks — Keeps momentum by focusing on high-performance data center platforms and programmable EOS software. Arista’s strength is its match to cloud-scale and AI fabric needs where deterministic performance and automation matter most.
-
Juniper Networks — Positions itself with high-throughput QFX and EX series platforms and strong support for modern overlay fabrics like EVPN-VXLAN, offering buyers flexible fabric options for campus-to-cloud deployments.
-
NVIDIA — A silicon and systems play that is catalyzing AI-data-center deployments with Spectrum-series products and recent Spectrum‑X traction among mega-cloud customers. For organizations building GPU-heavy clusters, NVIDIA’s ecosystem compatibility may outweigh traditional vendor loyalties.
-
Hewlett Packard Enterprise (Aruba) — Emphasizes cloud-native management and CX-series programmability, appealing to enterprises seeking unified management across campus, branch, and private cloud environments.
-
Huawei — Advances with high-capacity, automated platforms and all‑optical innovations in data-center switching; appropriate for buyers prioritizing high bandwidth and automation in certain markets but requiring due consideration of supply-chain and geopolitical factors.
-
Specialists and industrial vendors — D-Link, Extreme Networks, TRENDnet, Omnitron and others sustain niches: SMB, industrial edge, security-optimized campus fabrics, and power-efficient PoE solutions. Innovations such as GaN PoE++ and compact managed edge switches are lowering barriers to electrification and surveillance-scale deployments.
Recent market signals that change 2026 playbooks
-
Major hyperscalers have adopted next-generation switch platforms designed for AI fabrics, validating the need for high-bandwidth GPU interconnects and programmable telemetry.
-
Vendors and ODMs are launching multi-terabit data center switches and contributing designs to open communities, signaling a trend toward collaborative system design to shorten time-to-market.
-
First-to-market GaN-based Ethernet switches and PoE++ platforms suggest a shift in total cost of ownership calculations where power efficiency and thermal ceilings become procurement differentiators.
-
Regulatory mandates for managed, auditable network platforms are already altering replacement cycles in critical sectors, creating immediate demand for compliant hardware.
What our full report delivers (practical deliverables)
To convert these macro signals into executable 2026 plans, the full PW Consulting study provides:
-
Scenario-driven market sizing and a detailed forecast model (2026–2032) with sensitivity lenses so buyers can stress-test CapEx and OpEx under supply, regulation, and technology adoption shocks.
-
Vendor scorecards that assess product roadmaps, silicon partners, support ecosystems, and risk factors, enabling procurement shortlists aligned with strategy (e.g., AI fabric, industrial resilience, campus consolidation).
-
Procurement playbooks and contract language templates addressing lead-time guarantees, spare-part commitments, firmware-update compliance, and open-hardware clauses (OCP-style engagement paths).
-
Toolsets for TCO modeling that incorporate power, cooling, space, licensing, and lifecycle security maintenance — plus migration blueprints for replacing unmanaged fleets with compliant managed platforms.
-
Supplier diversification matrices and contingency plans to mitigate mature-node ASIC supply constraints, including recommendations for multi-sourcing, staged rollouts, and buffer inventory strategies.
-
Use-case-level architecture guidance (data center vs. campus vs. industrial vs. edge) with technology decision trees to choose fixed vs. modular platforms, and proprietary vs. open OS stacks.
Implications for 2026 decisions — three immediate priorities
-
Design for regulatory permanence: If your network supports critical services, accelerate replacement of unmanaged switches and ensure new purchases meet managed Layer 3 and auditability requirements.
-
Build silicon and supply flexibility into procurement: Include alternative silicon paths, acceptance of ODM partners, and inventory hedges in multi-year contracts to reduce exposure to lead-time spikes.
-
Prioritize power-aware economics: For high-density PoE and surveillance rollouts, evaluate GaN-enabled platforms and power-optimized switch architectures as defensible TCO levers.
How to use this preview
This preview is intended to frame your 2026 decision cycle: it points to where to accelerate, where to hedge, and where to demand more from suppliers. For teams preparing RFPs, budgeting for CapEx/OpEx, or reassessing vendor partnerships, the full PW Consulting Ethernet Switches Market study provides the underlying data tables, segmentation models, and vendor analytics necessary to move from intent to procurement with confidence.
Next steps
PW Consulting’s full report contains the granular segment analyses, supplier-by-feature scorecards, and downloadable models referenced here. If your 2026 network strategy depends on accurate forecasts, validated vendor benchmarking, and executable procurement playbooks, we recommend accessing the full report and scheduling a tailored briefing to align the insights with your specific architecture and timelines.
For detailed analysis of this topic, please visit the official page: Ethernet Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com