

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Personal Flotation Devices Market to Hit USD 344.8 Million by 2032 at 6.98% CAGR — PW Consulting

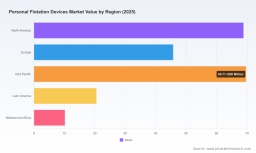
Personal Flotation Devices Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive primer that frames our full Personal Flotation Devices (PFD) Market study and explains why the findings matter for leadership decisions in 2026. This advisory is deliberately tactical: it surfaces the research’s most consequential takeaways—enough to inform board-level debate—while reserving the granular segment-level intelligence that drives execution and transaction diligence for the full report.
Personal Flotation Devices Market
Why PFDs matter in 2026: a market at the intersection of regulation, safety, and technology
The PFD market is no niche firefight. After steady expansion over the early 2020s, the global market base grew from the low hundreds of millions in 2020 to an estimated USD 215.0 Million in our base year of 2025. Under our central forecast (2026–2032), the market compounds at roughly 6.98% annually, reaching an estimated USD 344.8 Million by 2032. That trajectory reflects a confluence of forces: regulatory harmonization, persistent safety gaps in recreational and commercial boating, rising offshore and aquaculture activities in select maritime corridors, and a wave of product innovation—particularly in smart and performance-labeled devices.
Personal Flotation Devices Market
For executives deciding where to allocate capital in 2026, those macro facts translate into three strategic imperatives: accelerate standards-compliant product development, strengthen supply-chain resilience for performance-critical components, and differentiate through service-offset business models that extend beyond the physical lifejacket.
Personal Flotation Devices Market
Regulatory dynamics: both a barrier and an enabler
-
Performance-based labeling and harmonization: Regulatory changes effective since early 2025 have shifted industry yardsticks from Type-based classification to performance-level labeling. This shift—now recognized across key jurisdictions—raises the cost of non-compliance but creates a durable advantage for manufacturers that retrofit approval processes and quality assurance systems early.
-
Cross-border carriage and approvals: Harmonized acceptance in adjacent markets (notably North America) reduces friction for approved product lines, enabling faster commercial rollouts for compliant manufacturers and increasing the value of regulatory-compliant certifications in M&A valuations.
-
Safety statistics as policy levers: Persistently high incident tallies and suboptimal wear rates in recreational boating continue to sustain outreach and carriage rule enforcement programs—conditions that underpin longer-term demand for user-centric, comfortable, and visibly certified PFDs.
Competitive landscape: fragmentation with pockets of specialization
Market concentration remains low: the three- and five-firm concentration ratios are both under 30%, signaling a fragmented landscape where brand reputation, channel relationships, and product differentiation matter more than scale alone. That dynamic produces two playbooks that work in parallel.
-
Specialist-led differentiation: Brands that focus on application-specific performance (professional marine, whitewater, yachting, offshore) continue to capture premium positioning through innovation and channel credibility. Recent new-model catalogs and product launches demonstrate ongoing investment in performance features and targeted approvals.
-
System and service aggregation: Larger suppliers that serve commercial shipping, defense, and offshore operators combine product breadth with certification capabilities and global service footprints—creating bundled propositions (supply + maintenance + certification) that are defensible in tender processes.
Across both plays, recent product and partnership activity in 2026 highlights the market’s direction: performance enhancements (airway protection, higher-turning safety), rescue integration (search-and-locate electronics), youth- and comfort-focused ergonomics, and harness-integrated models optimized for regulatory approvals. These moves are consistent with a market responding to both top-line growth and elevated buyer expectations for functionality and traceable compliance.
Company archetypes and strategic positioning
-
Performance innovators (examples among leading players): companies known for inflatables, hybrid PFDs, and certified Level 50/70/100 products are investing in airway protection systems and advanced buoyancy materials—aimed at professional and rescue markets where performance proofs command higher margins.
-
Recreational specialists: brands with a strong presence in paddling, whitewater, and wake sports are differentiating through fit, mobility, and increasingly through rescue-technology integrations that appeal to organized events and rental fleets.
-
Commercial systems suppliers: manufacturers that serve shipping, offshore, and military customers emphasize certification breadth, lifecycle services, and distribution partnerships to win institutional contracts.
Strategic takeaways for 2026: for market entrants, build early regulatory-compliance competencies; for incumbents, protect higher-margin niches via product certification and service depth; and for investors, prioritize targets with demonstrable product-approval pathways and repeat institutional revenue.
Supply chain and cost dynamics
PFD manufacturing depends on three categories of inputs with asymmetric risk profiles: polymeric buoyancy materials and foam systems, textile shells and closures engineered for UV and saltwater exposure, and life-safety ancillary components (inflation canisters, buckles, electronics). Sourcing concentration and certification requirements raise the switching cost for buyers and keep margins under pressure when raw-material price volatility spikes.
Operationally, manufacturers face two levers in 2026: localized manufacturing to shorten lead times for regulated markets; and selective automation in assembly to reduce labor sensitivity for higher-end, certified models. For many suppliers, the optimal 2026 playbook is hybrid: retain low-volume, high-margin assembly domestically for certified lines, and offshore higher-volume manufacturing for commoditized models—while investing in supplier audits and traceability systems that support cross-border approvals.
Product innovation and services: where premiums are earned
-
Smart integration: locator beacons, remote-status telemetry, and rescue-locator integrations are moving from optional annexes to decision criteria in institutional procurement. Early adopters of integrated rescue electronics are realizing shorter procurement cycles with coast guard and offshore operators.
-
Ergonomics and wearability: comfort-driven design—especially in youth and recreational segments—improves adoption rates, which is a public-safety and marketing win. Product ergonomics tied to demonstrable wear-rate improvements attract both consumers and safety-conscious fleet operators.
-
Service and circularity: maintenance, re-certification, and end-of-life recovery services are emerging as differentiators for commercial buyers seeking predictable lifecycle costs. Pilots in maintenance-as-a-service and certified refurbishment are already influencing RFP outcomes in institutional buying cycles.
What the PW Consulting report delivers (practical, transaction-ready intelligence)
-
Market sizing and a demand matrix built on 2020–2025 history and a 2026–2032 forecast, including scenario sensitivity and upside drivers.
-
Regulatory impact assessment with a step-by-step compliance playbook for Level-based approvals and cross-jurisdiction carriage requirements.
-
Supplier and raw-material risk heatmaps, plus cost-mitigation levers and recommended sourcing strategies for 2026 procurement cycles.
-
Go-to-market templates for targeting commercial tenders, rental fleets, and retail channels—covering pricing, certification bundling, and aftercare propositions.
-
Competitive benchmark and capability matrix across leading vendors, with acquisition targets scored on strategic fit, regulatory readiness, and service potential.
-
Deal playbook: valuation sensitivities, integration checklists, and post-merger operational milestones tailored to PFD companies.
Actionable strategic recommendations for 2026
-
Prioritize certification-led product launches. If you are a manufacturer, allocate 12–18 months of R&D and quality budget to ensure new models are approved under performance-level labeling before major bidding seasons.
-
Invest in rescue-integration partnerships. Integrating locator or telemetry technology into select product lines strengthens propositions for commercial and rescue markets and raises switching costs for customers.
-
Adopt a dual manufacturing footprint. Combine regional certified assembly for regulated markets with cost-efficient offshore production for commoditized SKUs to optimize margins without compromising approval timelines.
-
Pursue service-led differentiation. Launch certified maintenance and refurbishment pilots for institutional customers to create recurring revenue and improve retention.
-
Make M&A decisions based on certification-readiness and service capabilities rather than scale alone. In a fragmented market, bolt-on assets that close capability gaps (compliance labs, telemetry expertise, service networks) often yield the quickest accretion.
Closing perspective: where PW Consulting adds strategic advantage
Our analysis confirms that the PFD market is expanding at a near-7% compound annual rate and is reshaping around regulation, safety adoption, and technology-enabled differentiation. The competitive field remains fragmented—creating windows for focused players to capture premium niches and for acquirers to consolidate capability clusters. But the clock is ticking: regulatory harmonization and evolving buyer expectations make 2026 the inflection year for firms that intend to lead rather than follow.
The attached full PW Consulting report contains the detailed regional, type, and application splits, supplier scorecards, and model-level forecasts needed to operationalize the strategic priorities summarized here. If you are preparing procurement cycles, investment diligence, or a product roadmap for 2026, the full dataset and our recommended tactical templates will shorten your path from decision to execution.
Contact PW Consulting to access the complete Personal Flotation Devices Market study and receive a tailored briefing that maps the report’s findings to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Personal Flotation Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com