

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
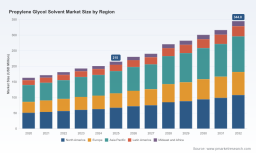
PW Consulting: Propylene Glycol Solvent Market to Hit USD 344.8M by 2032 at 6.98% CAGR

Propylene Glycol Solvent Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise but forward-looking briefing designed to orient executive teams, corporate development groups, and supply-chain leaders as they set priorities for 2026. The propylene glycol solvent market is no longer a stable, predictable commodity space. Our base-year assessment (2025) shows a global market that has been expanding steadily through the early 2020s and moves into an accelerated growth phase over the 2026–2032 forecast window at an estimated CAGR of 6.98%. By modelled trajectories, the market moves from roughly the low‑hundreds (USD Million) in 2025 to a materially larger footprint by 2032 — reflecting a confluence of semiconductor-driven demand, specialty solvent applications, and bio-based substitution trends.
Propylene Glycol Solvent Market
Why this briefing matters for 2026
- 2026 is a pivot year: supply-chain disruptions, feedstock volatility and regulatory attention are converging to produce asymmetric upside and downside scenarios for suppliers and consumers.
- Decisions made in 2026 on capacity, sourcing, and customer contracts will materially influence market position throughout the 2026–2032 forecast horizon because lead times for capex and the impact of feedstock-driven cost curves are long.
- This briefing highlights high-conviction strategic levers — pricing strategy, security of supply, targeted product differentiation, and sustainability positioning — that translate our market intelligence into executable actions.
Market trajectory: headline view
From a 2025 base, the total market exhibits a sustained expansion into our forecast period. Our modelling — built on historical trends (2020–2025), feedstock price dynamics, and end‑market demand signals — produces a compound annual growth rate of 6.98% for 2026–2032. The implications are twofold: (1) aggregate demand is strong enough to absorb new capacity if brought to market in a disciplined way, and (2) suppliers that can mitigate margin compression from volatile propylene oxide pricing will capture disproportionate economic value.
Propylene Glycol Solvent Market
Dynamics shaping supply and demand
- End‑market concentration of demand: Growth is being pulled by high-value industrial uses where solvent performance and purity matter (e.g., semiconductor processes and specialty formulations). Buyers in these segments prioritize reliability, traceability and certification — not just price.
- Feedstock volatility is a dominant risk factor. Recent market signals show regional dislocations: propylene oxide trading spikes and regional spreads (notably in North America, Northeast Asia and Europe) are producing asymmetric cost pressures across producers and distributors. These swings create tactical opportunities for market participants with hedged feedstock positions or flexible routing.
- Regulatory and safety context is supportive but requires vigilance. Propylene glycol retains GRAS status in food contexts and currently lacks specific workplace or environmental standards under major U.S. regulatory frameworks — a fact that reduces near-term compliance risk but increases reputational responsibility for end users and formulators.
- Sustainability and bio‑based substitution are no longer boutique themes. Bio‑based propylene glycol capacity additions and customer preference shifts (especially in food, personal care and regulated pharmaceutical uses) are reshaping supplier value propositions.
Recent market events that recalibrate 2026 strategy
- Supply interruptions and force majeure actions are elevating premium for security of supply: a notable force majeure declaration by a major supplier following a manufacturing site incident underscores the vulnerability of regional hubs.
- Leading producers have signalled commercial repositioning: some suppliers enacted price increases earlier in 2026, while others expanded bio‑based capacity in 2025 to capture sustainability-led demand.
- New capacity from regional producers has the potential to shift competitive dynamics, but the timing, ramp rates and feedstock sourcing of these additions will determine whether they create downward pressure on margins or enable differentiated product offers.
Competitive landscape: what the major players are doing
The market structure is fragmented; the top-three and top-five producer concentration metrics are modest, indicating room for agile players to gain share through targeted strategic moves rather than sheer scale alone. Key incumbents combine broad chemical portfolios with product lines tailored to both industrial and regulated applications. High-level observations:
Propylene Glycol Solvent Market
- Dow Inc. (United States) leverages high-purity product lines aimed at pharmaceutical and specialty industrial customers. Recent price actions signal an intent to defend margins amid feedstock pressures.
- BASF SE (Germany) maintains a diversified offer set spanning industrial, pharmaceutical and cosmetic solvent applications where formulation expertise is a competitive advantage.
- LyondellBasell (Netherlands) and other commodity-scale producers emphasize glycol ethers and propylene glycol family products; operational disruptions at major sites in 2026 highlight the importance of diversified asset footprints and contingency planning.
- Huntsman and Shell focus on specialty derivatives and industrial-grade streams respectively; their strategies differ in route-to-market but align on reliability and technical support as differentiators.
- Archer Daniels Midland (ADM) has moved decisively into bio‑based propylene glycol capacity expansion to serve sustainability-driven segments — a clear defensive and offensive play that should pressure conventional producers on value-added credentials.
- INEOS and regional producers continue to plug niche gaps and serve specific regional demand centers; their actions are key to short-term spot availability and regional pricing dynamics.
Strategic implications and recommended playbook for 2026
If your objective is to protect margins and grow share across the 2026–2032 window, consider the following priority moves. These are framed as strategic options rather than prescriptive mandates — the optimal mix depends on your starting position, balance-sheet capacity and customer mix.
- Hedge feedstock exposure and build flexible sourcing: Short‑term feedstock spikes have immediate P&L impacts. Hedging combined with multi‑sourcing and contractual clauses to share or pass through cost movements is table stakes.
- Invest selectively in high-purity and regulated-grade capacity: The segment of demand that values certification and traceability commands a premium. Investments here yield durable margins if executed with tight quality control and strong technical service.
- Differentiate on sustainability credentials: Bio‑based production and lower-carbon supply chains are increasingly procurement criteria in regulated end markets. Positioning and certified product lines will shorten sales cycles with sustainability-focused buyers.
- Operational resilience as commercial leverage: Demonstrable redundancy (alternative routes, diversified warehousing, contingency logistics) should be converted into commercial terms — premium contracts, service guarantees and prioritized allocations to strategic customers.
- Scenario-based pricing and contract design: Use tiered contracts with indexed pass-through mechanisms for feedstock, and design options for volume-flexible commitments given demand unpredictability in certain end applications.
- M&A and partnership playbook: With industry concentration low, bolt-on acquisitions of regional capacity or technical niche players can accelerate access without the prohibitive price of a market-dominant buyout.
What the full PW Consulting report delivers (practical, executable content)
The complete market study is designed to convert intelligence into decisions. Highlights include:
- Demand and revenue modelling through 2032, with scenario trees reflecting high, base and downside cases.
- Feedstock price modelling with regional spreads, volatility analysis and pass-through mechanics tied to contractual architectures.
- Competitive benchmarking and capability heatmaps for primary suppliers, including technology, geography, and product suites.
- Commercial playbooks: contract templates, indexation clauses, and negotiation levers to manage price risk and secure supply.
- Investment decision frameworks: NPV, IRR and payback sensitivities for capacity additions, debottlenecking and quality upgrades in different market scenarios.
- Regulatory risk assessment and compliance roadmaps, including product stewardship for food, pharmaceutical and cosmetic use cases.
- Supply‑chain mapping and risk matrix covering logistics chokepoints, single‑source risks and mitigations.
Important: this introductory briefing deliberately omits granular disclosure of region‑ and application-level split tables and dollarized segment allocations. Those core segmentation datasets, along with exhaustive company scorecards and downloadable financial models, are available exclusively in the full PW Consulting report and online portal.
Methodology and credibility
Our findings synthesize primary interviews, supplier disclosures, proprietary pricing databases and public regulatory sources. Historical calibration (2020–2025) aligns to audited company reporting and third‑party price series; forward projections (2026–2032) are stress‑tested against multiple feedstock and demand scenarios. We also integrate raw‑material market signals — for example, recent regional observations of propylene oxide pricing — to adjust near‑term margin and supply risk assessments.
Final advisory: position for asymmetric outcomes
Market conditions in 2026 will reward organizations that simultaneously defend near‑term cash flow and lay the groundwork for differentiated, higher‑margin offerings. Tactically, prioritize contractual protections, immediate supply redundancy where needed, and selective investments in regulated‑grade or bio‑based product lines. Strategically, evaluate partnerships and targeted acquisitions to accelerate capability without overcommitting capital into a volatile feedstock environment.
For executives building their 2026 playbook, the full PW Consulting Propylene Glycol Solvent Market study contains the granular intelligence, models and executable templates required to move from insight to action. Access to the comprehensive segment tables, downloadable financial models and supplier scorecards is available on our report page — and we welcome tailored briefings to translate these insights into company‑specific strategies.
For detailed analysis of this topic, please visit the official page: Propylene Glycol Solvent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com