

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hyaluronic Acid Market Set to Hit USD 18.93B by 2032 at 7.4% CAGR - PW Consulting

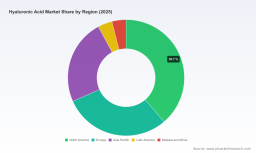
Hyaluronic Acid Market 2026: Strategic Imperatives for Growth, Risk and Differentiation
As global demand for hyaluronic acid (HA) applications continues its steady ascent, corporate leadership teams face a narrowing window in 2026 to translate market momentum into durable competitive advantage. PW Consulting’s latest Hyaluronic Acid Market study situates executives with a data-rich, decision-ready blueprint: from historic consumption pathways and supply-side evolution to forward-looking scenarios that map regulatory friction, reimbursement shifts and product innovation into actionable strategies.
Hyaluronic Acid Market
Why 2026 is a Pivotal Year
The HA market has experienced sustained expansion over the past half-decade, rising from roughly USD 6.0 Billion in 2020 to USD 11.5 Billion in 2025. Looking forward, our forecast through 2032 projects continued growth—reaching the high teens by the end of the decade—supported by a compound annual growth rate of 7.4% during the 2026–2032 forecast window. These headline trajectories reflect converging forces: robust demand in aesthetic and therapeutic applications, ongoing product innovation, and shifting reimbursement and regulatory landscapes that will re-score winners and laggards in real time.
Hyaluronic Acid Market
What This Report Delivers — Practical, Executable Intelligence
- Financial and market modeling: Integrated historic series (2020–2025) and forward-looking financial models (2026–2032) with scenario toggles for regulatory shocks, reimbursement constriction, and technology adoption curves.
- Segment strategy frameworks: Playbooks that align portfolio choices (cosmetic vs. pharmaceutical-grade, injectables vs. viscosupplements) to channel economics, margin sensitivities, and scale thresholds.
- Regulatory and reimbursement matrix: A prioritized map of compliance triggers, approval pathways, and payer policies that materially affect market access in 2026—accompanied by mitigation and evidence-generation roadmaps.
- Supply chain and manufacturing diagnostics: End-to-end analysis of production technologies (including fermentation-based supply), capacity constraints, quality-control hotspots, and outsourcing vs. insourcing decision trees.
- Competitive benchmarking and M&A playbook: Tactical profiles and capability maps for incumbent leaders, fast followers and emerging entrants; acquisition targets filtered by technology fit, geographic footprint and integration risk.
- Commercial acceleration guides: Channel segmentation, pricing and contracting templates, digital engagement strategies for aesthetic clinics and payers, and three prioritized go-to-market pilots for 2026.
- Primary research vault: Confidential interview synopses with senior R&D, regulatory and procurement leaders across manufacturers, payers and treatment centers—used to validate assumptions and calibrate scenarios.
Competitive Landscape — Leaders, Disruptors and the Mid-Market
The HA market remains moderately concentrated; our concentration metrics indicate that the top three firms account for a majority share, with the top five further consolidating the upper-tier. This structure creates a distinct dynamic: scale delivers access to global clinic networks, regulatory capital and branded premiumization, while nimble challengers can win on innovation and targeted clinical evidence.
Hyaluronic Acid Market
- Large global players: Established manufacturers—such as Allergan (AbbVie) and Galderma—continue to anchor the dermal and aesthetic segments with globally recognized filler brands and extensive commercial channels. Their strengths are brand equity, regulatory experience, and distribution scale.
- Pharmaceutical and specialty device firms: Companies like Sanofi and Merz maintain significant positions through therapeutic formulations and medically positioned aesthetic offerings, leveraging clinical trial expertise and payer relationships.
- Orthopedics and viscosupplement specialists: Firms including Anika Therapeutics, Zimmer Biomet, Seikagaku, and Fidia focus on viscosupplementation and orthopedic indications—areas where clinical pathways and reimbursement policies materially govern uptake.
- Innovation-focused entrants: New approvals in 2025 and 2026 (notably novel dermal gels approved by the U.S. regulator) demonstrate how focused R&D and differentiated technology can displace incremental players; these entrants may command outsized attention from acquirers seeking platform diversification.
- Specialty manufacturers: Regional and technology-specialist producers such as Contipro serve critical roles in supplying medical-grade HA via fermentation and other platforms—becoming strategic partners in securing quality raw material and reducing supply volatility.
Recent Industry Shocks and What They Mean for Strategy
- Regulatory tightening in the EU: Recent regulatory action removing certain nano-enabled cosmetic inputs from market access underscores the need for early chemical inventories and reformulation strategies for firms selling across the Union.
- U.S. regulator advisories: The FDA’s 2026 advisories concerning OTC HA products with undeclared actives elevate liability and compliance costs; brand owners and private-label manufacturers must now prioritize laboratory verification and supply-chain transparency.
- Payer policy change for viscosupplements: A major commercial payer’s new prior-authorization and diagnostic criteria for intra-articular sodium hyaluronate heighten the barrier to access for orthopedic HA products. Manufacturers must recalibrate market-access plans and invest in outcomes and cost-effectiveness data to protect commercial volumes.
- Notable product approvals: Several recent FDA approvals for new injectable HA gels highlight both the continued attractiveness of aesthetics and the importance of first-mover clinical differentiation—opportunities for premium positioning but also catalysts for price compression as competition intensifies.
Strategic Priorities for 2026 — Where Leadership Should Focus
Our analysis translates market realities into six priority actions that boards and executive teams should formalize in 2026 planning cycles:
- Prioritize regulatory and quality capital: Expedite workstreams that guarantee compliance across jurisdictions—laboratory verification, supply-chain traceability and documented pharmacovigilance—reducing recall/penalty risk and preserving brand trust.
- Lock core supply via strategic partnerships: Secure long-term agreements or minority equity stakes in upstream producers that use robust fermentation technologies to mitigate raw-material volatility and support scale-up for therapeutic-grade demands.
- Protect and build clinical evidence: For therapeutic and reimbursed applications, invest in pragmatic trials and real-world evidence demonstrating comparative effectiveness and health-economic value to preserve access under tightening payer rules.
- Rebalance portfolio allocation: Reassess capital deployment between premium aesthetic franchises and lower-margin commodity applications—consider spin-outs, divestitures or carve-ins to sharpen focus and improve ROIC.
- Accelerate commercialization via channel innovation: Develop clinic partnerships, bundled-service propositions, and digital-first patient engagement models that increase share of wallet and capture margin beyond product sales.
- Use M&A as capability acquisition, not volume chase: Target assets that add regulatory dossiers, manufacturing capacity, or unique formulation IP rather than only seeking incremental market share; integration playbooks must be pre-approved to avoid value erosion.
How PW Consulting’s Study Helps Executives Make Winning 2026 Decisions
This report is structured as a pragmatic decision tool—not an academic monograph. Executives can use it to:
- Quantify top-line scenarios under alternative regulatory and reimbursement trajectories and translate these into operating budgets and CAPEX plans.
- Prioritize R&D and clinical investments with a return-risk ladder that identifies quick wins and longer-term platform bets.
- Build defensible market-access strategies that map clinical endpoints to payer criteria and identify the minimum evidence required to sustain coverage.
- Screen M&A targets against a proprietary integration readiness index and calculate expected synergy ranges under conservative and aggressive assumptions.
What We Intentionally Withhold Here — And Why
In keeping with a “trailer” approach designed to establish credibility while driving engagement with the full deliverable, this introduction omits the granular breakdowns found in the core dataset: specific country-by-country revenue splits, application-by-application valuations, unit-price trajectories, and individual segment CAGR subcomponents. These detailed tables, interactive models and primary-source annexes are included in the full PW Consulting report and are essential for tactical planning such as pricing by SKU, inventory forecasts by plant, and negotiation-ready payer value dossiers.
Next Steps for Executives
- Request a confidential briefing to review scenario outputs tailored to your corporate mix and go-to-market priorities.
- Commission our regulatory gap assessment to quantify the cost and timeline to secure compliance for target markets in 2026–2027.
- Engage our M&A deal team for a short-list of targets that fit your strategic criteria—manufacturing capacity, formulation IP, or market access capabilities.
Hyaluronic acid is no longer a single-market story: it is a portfolio of linked clinical, regulatory and commercial vectors that will separate durable franchises from short-lived fads in the next 36 months. PW Consulting’s Hyaluronic Acid Market study delivers the actionable intelligence required to navigate that separation—turning macro growth into defensible, profitable and compliant business outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hyaluronic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com