

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Precision Casting Market to hit USD 28.39 Billion by 2032, 5.24% CAGR: PW Consulting

Precision Casting Market 2026: Strategic Preview for Boardrooms and Capital Planners
Introduction — why this briefing matters for 2026 decisions
As private equity, OEM procurement heads, and industrial strategists reassess supply chains and technology bets in 2026, precision casting occupies a unique inflection point. Our latest market study frames the opportunity in macro terms — the global precision casting market expanded from roughly USD 15.9 billion in 2020 to USD 19.8 billion in 2025 and, under the central forecast, is set to reach approximately USD 28.4 billion by 2032, implying a mid-single-digit compound annual growth rate (CAGR) of about 5.24% over the 2026–2032 horizon.
Precision Casting Market
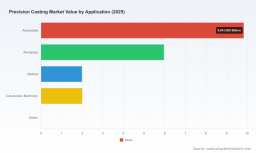
These headline metrics underline steady demand growth driven by aerospace, automotive electrification and lightweighting, medical device precision, and industrial modernisation — yet beneath the topline lie structural shifts that will determine winners and losers. This article synthesizes the study’s strategic insights (without disclosing the granular segmentation and proprietary datasets) so executives can frame high‑stakes 2026 decisions: capacity expansion, vertical integration, M&A targets, digital foundry investments, and regulatory compliance programs.
Precision Casting Market
Market trajectory and what it means for capital allocation
-
Recovery and re-rating: The market’s ascent from 2020 to 2025 reflects both cyclical recovery and durable structural demand. The forecast to 2032 at ~5.24% CAGR signals a predictable, investable growth corridor — attractive for disciplined capital deployment but not immune to margin pressure from raw material volatility and regulatory costs.
Precision Casting Market -
Timing matters: Given the multi‑year lead time of major capacity projects and the accelerating adoption of digital and additive technologies, decisions made in 2026 will materially affect cost curves and market positioning into the early 2030s.
-
Consolidation window: Market concentration metrics (top 3 players ~65%; top 5 ~72%) indicate a market that is neither a pure commodity nor a highly fragmented artisan industry. There remains space for scale plays and bolt‑on M&A for companies that can layer technical differentiation on capacity.
Key industry dynamics shaping 2026 strategy
-
Technology transition — additive and hybrid manufacturing: Recent commercial deployments of ceramic 3D printing for investment casting cores and digital foundry platforms are compressing prototyping-to-production cycles. Capabilities now exist to convert months of tooling time into days for certain workstreams, materially reducing time-to-market for complex geometries and enabling localized, on-demand production for high‑value parts.
-
Supply chain and cost pressure: Raw material volatility — notably for nickel alloys, titanium, and specialty steels — is increasingly a driver of margin compression. A more volatile metal-price environment elevates the strategic value of alloy optimization, hedging programs, and upstream sourcing partnerships.
-
Regulatory and environmental compliance: The regulatory environment is tightening around effluent and stormwater discharges, with recent updates to U.S. permit regimes and industry-level best practices. Companies that proactively invest in environmental controls not only reduce compliance risk but gain competitive advantage with customers that prioritize sustainable suppliers.
-
End-market evolution: Automotive electrification and continued aerospace ramp-ups sustain demand for complex, high‑precision castings, while healthcare and industrial equipment provide stable niches. Pricing power will increasingly follow technological differentiation (surface finish, tolerance, material systems) rather than volume alone.
Competitive landscape — how to read the supplier map
The market is characterized by a mix of legacy specialists, regional champions, and emerging technology entrants. Understanding relative strengths — capacity, alloy expertise, certifications, and proximity to key OEMs — is essential for partnership and M&A strategies.
-
Milwaukee Precision Casting (Milwaukee, WI, USA): A high‑volume, air‑melt alloy specialist with ISO 9001:2015 accreditation and an emphasis on competitive lead times for complex parts.
-
Engineered Precision Casting Company (EPCO) (United States): A long‑standing foundry with deep tooling and in‑house fabrication capability, notable for handling complex projects at scale.
-
Consolidated Precision Products (CPP) (Cleveland, OH, USA): One of the largest aerospace-focused casters globally, with breadth across superalloys, titanium and specialty materials for defense and aviation applications.
-
Bescast (United States): A specialist in high‑precision blades and vanes for high‑temperature and corrosion‑resistant environments in aerospace and defense.
-
Precision Castings of Tennessee (Gallatin, TN, USA): Offers deep design and engineering services with a history of high‑volume military and automotive production parts.
-
Wisconsin Precision Casting Corporation (Waukesha, WI, USA): Noted for its production and rapid‑prototype capabilities and sizeable manufacturing footprint.
-
MPH Precision Castings (India) and several specialized Chinese manufacturers: These players provide export‑oriented capacity and competitive cost structures, increasingly moving up the value chain on quality and engineering services.
-
Smaller innovators and new entrants: Companies integrating additive ceramic printing, digital foundry platforms, and advanced inspection technologies are reshaping the competitive set and creating new acquisition targets.
Recent developments to factor into 2026 strategy
-
CERAM PRO and ceramic 3D printing demonstrations at technical conferences show that core production can be decoupled from traditional tooling, enabling lowered fixed costs for low-to-medium volume runs.
-
Commercial launches of digital foundry platforms accelerate delivery speed and relieve capacity constraints in certain geographies — a potential game changer for on‑shoring and near‑shoring strategies.
-
Updated alloy catalogs from major material suppliers signal improved alloy specification transparency, which supports design‑for‑cast optimization and reduces qualification cycles for OEMs.
-
Trade shows continue to be a proving ground for coated sand and hybrid process offerings, highlighting incremental process optimization that can improve yields and reduce rework costs.
Strategic implications and recommended actions for 2026
-
Prioritize hybrid investments: Combine selective expansion of conventional capacity with pilot projects in ceramic additive cores and digital foundry workflows to hedge against obsolescence while capturing near-term demand.
-
Pursue M&A with engineering uplift: Target acquisitions that bring process IP, alloy know‑how, or certification pathways rather than pure capacity alone — this is where margin improvement is realized.
-
Industrialize sustainability: Build modular environmental control systems and customer-facing sustainability reporting — compliance is a cost today and a differentiator tomorrow.
-
Lock downstream partnerships: Create captive agreements with aerospace and automotive OEMs to secure long‑cycle demand and de‑risk investment in higher‑cost alloys.
-
De‑risk metals exposure: Implement hedging strategies, long‑term contracts, and alloy substitution roadmaps to stabilise input costs without compromising performance.
-
Adopt digital quality at scale: Invest in inline inspection, process analytics and digital twins to reduce scrap, shorten qualification cycles, and shift from price‑based to performance‑based commercial models.
-
Scenario‑proof capacity decisions: Use staged capex with option exercises tied to demand triggers and technology milestones; avoid single‑large bets given potential for rapid productivity gains from additive cores.
What the full PW Consulting report delivers (practical, executable content)
-
Actionable market forecasts and scenario models that allow users to stress-test demand under varying OEM production plans, alloy cost curves, and regulatory cost assumptions.
-
Detailed supplier benchmarking (qualitative and capability matrices) to shortlist partners by certification, alloy competence, capacity flexibility, and proximity to key markets.
-
Commercial playbooks for entrants and incumbents: M&A target profiles, valuation heuristics for foundry assets, and three go‑to‑market strategies for different scale objectives.
-
CapEx planning templates and ROI calculators tailored to conventional cast vs. additive-enabled cell investments, including sensitivity to metal price and yield improvements.
-
Regulatory compliance roadmap and best practices for environmental permits, effluent controls, and air emissions management aligned with recent U.S. EPA developments and multi-sector permit updates.
-
Supply‑chain risk matrix with mitigations for raw material shocks, geopolitical disruptions, and critical skill shortages — actionable procurement levers and supplier diversification playbooks are included.
-
Technology adoption guide: vendor shortlists, pilot KPIs, and integration plans for ceramic 3D printing, digital foundry platforms, and inline NDT (non‑destructive testing) systems.
Concluding guidance
For executives allocating capital or re‑setting supply‑chain priorities in 2026, precision casting presents a mix of reliable topline growth and disruptive technological change. The market’s predictable expansion through 2032 creates attractive windows for investment, but the value will accrue to those who combine operational scale with targeted technology adoption, disciplined raw‑material risk management, and proactive regulatory positioning.
This preview highlights the strategic contours you need for boardroom debate. To act with confidence — and to access the granular segmentation, supplier scorecards, and financial models that underpin these recommendations — consult the full PW Consulting Precision Casting Market report and accompanying tools. The full report is designed to convert the macro growth narrative into repeatable, measurable action plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Precision Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com