

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High-Purity Hydrogen Market to Reach USD 532.2M by 2032 at 7.85% CAGR

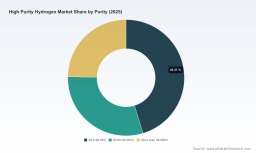
High Purity Hydrogen Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
As energy systems, manufacturing, and advanced electronics converge on tighter purity, lower-carbon footprints, and uninterrupted supply, high purity hydrogen is migrating from a specialist input to a strategic commodity. PW Consulting’s High Purity Hydrogen Market study (base year 2025, historical period 2020–2025, forecast 2026–2032) documents this transition with quantified forward-looking scenarios and operator-grade decision tools designed for boardrooms and deal teams in 2026.
High Purity Hydrogen Market
At a macro level, the market has expanded from an estimated USD 236.5 Million in 2020 to USD 314.2 Million in 2025 and is modeled to reach roughly USD 532.2 Million by 2032, reflecting a compound annual growth rate of 7.85% across the forecast window. Market concentration is moderate: the top three suppliers account for approximately 42.5% of supply, and the top five for about 58.2%, indicating room for competitive moves by mid-tier players and new entrants with differentiated offerings.
High Purity Hydrogen Market
Why 2026 is a make-or-break year for hydrogen strategies
- Regulatory tightening is creating both risk and premium pricing for certified low-impurity hydrogen. Compliance timelines, especially for vehicle fuel standards and electrolyzer-produced hydrogen, compress decision cycles.
- End-markets that demand ultra-high purity (notably semiconductor manufacturing and certain fuel cell applications) are scaling investments in 2026; sourcing choices made this year will lock in supply chains for multi-year product ramps.
- Capital allocation decisions made in 2026 — on on-site generation, long-term pipeline capacity, or liquefaction/cryogenic storage — will determine competitive positioning through the late 2020s as demand growth accelerates.
Market trajectory and what the numbers mean for corporate planners
The market’s growth profile is steady and durable: from USD 314.2 Million in 2025 to an estimated USD 349.7 Million in 2026 and accelerating toward USD 532.2 Million by 2032 under a base-case 7.85% CAGR. For strategy teams this implies three practical implications:
High Purity Hydrogen Market
- Volume-led opportunities are material but require differentiated delivery models. Companies that can combine guaranteed purity, low leakage in logistics, and demonstrable carbon intensity credentials will capture incremental margins.
- Scale matters but so does placement. Given the moderate concentration among incumbents, targeted investments (e.g., regional pipeline interconnects, cavern storage, or dedicated on-site electrolysis) can produce outsized strategic returns when matched to local demand profiles and regulatory incentives.
- Scenario planning is essential. Sensitivity to purity standards, carbon pricing, and electrolyzer cost declines materially changes project NPV and payback timelines — our report provides ready-to-use scenario matrices to stress-test portfolio choices.
Dynamics & regulation: the new compliance frontier
Three recent regulatory and standards developments re-frame supplier and buyer responsibilities in 2026:
- ISO 14687:2025 tightens fuel-cell hydrogen impurity limits (for example, setting an O2 maximum at 1 ppm and CO limits in the sub-micromolar range for certain grades), and formalizes sampling methodologies. This raises testing and certification costs for producers and creates an opportunity for specialized analytical and QA services.
- CEN ISO/TS 15916:2026 updates safety standards for hydrogen systems, explicitly addressing high-purity hydrogen produced by electrolysis — manufacturers and project engineers must redesign component specifications and safety cases to remain compliant.
- Regulatory pressure from emissions reporting (e.g., analysis showing steam methane reforming can emit on the order of 9–12 kg CO2 per kg H2) is accelerating procurement preferences toward low-emission (blue/green) hydrogen. Buyers should expect contracting frameworks to incorporate lifecycle carbon intensity clauses and audit rights.
Competitive landscape — how incumbents are positioning
The market is anchored by global industrial gas majors and regionally specialized suppliers. Each incumbent brings a distinct strategic playbook that buyers and investors need to decode:
- Air Products and Chemicals, Inc. leverages vertically integrated assets across production, logistics (including liquid and compressed deliveries), and emergency services to offer reliability at scale. Their APEX-style services underscore the premium buyers pay for rapid-response contingency capabilities.
- Linde plc operates extensive liquid hydrogen capacity and distribution networks and has invested in strategic storage assets (including large caverns and long pipeline corridors). Their capability to offer hydrogen across a spectrum of carbon-intensity grades positions them strongly where buyers demand contractual flexibility between gray/blue/green supplies.
- Air Liquide S.A. combines pipeline infrastructure with on‑site production expertise, targeting industrial clusters and downstream clean energy projects. Their strength lies in integrated solutions that marry gas supply with engineering and maintenance contracts.
- Messer Group presents a clear value proposition for industrial applications with tightly specified product assays; their adherence to commercial gas association specifications caters to legacy process industries requiring known impurity envelopes.
- Taiyo Nippon Sanso emphasizes electronic-grade hydrogen for semiconductors and advanced electronics. For firms in high-value fabrication, their portfolio and local presence in Asia provide supply continuity and specialized QA protocols.
For prospective entrants or investors, the incumbents’ playbooks suggest two paths to compete: (1) differentiate on purity verification, low-carbon attribution, and service-level guarantees; or (2) become the specialized regional partner providing tailored logistics and just-in-time inventory management to niche industrial segments.
What the PW Consulting report delivers — operational intelligence, not just high-level charts
The published study is structured as a pragmatic guidebook for 2026 decision-makers. Key actionable components include:
- Supply-side mapping: asset-level capacity, technology mix (electrolysis, SMR, liquefaction), and operator scorecards to benchmark suppliers on purity, delivery modes, and carbon reporting.
- Demand-side playbooks for major end-use sectors with procurement templates, purity acceptance matrices, and suggested contractual levers to manage price and quality risk.
- Unit-cost and break-even curves for production technologies under multiple energy-price and carbon-policy scenarios, enabling quick "what-if" analysis for capital approvals.
- Regulatory impact modelling that translates standards (e.g., ISO 14687:2025, CEN ISO/TS 15916:2026) and emissions constraints into compliance costs and timeline risks for projects.
- Commercial structuring guidance, including offtake template clauses that align supplier incentives with buyers’ carbon and purity requirements, and a negotiation playbook for long-term purchase agreements and tolling arrangements.
- Project pipeline intelligence: an anonymized, scored list of near-term projects and likely procurement windows across regions and sectors to aid deal origination teams.
- M&A and JV decision frameworks for medium and large players, identifying where bolt-on acquisitions or partnerships can close capability gaps (e.g., analytical labs, cryogenic logistics, electrolyzer OEM relationships).
How executives should use this research in 2026
- Board-level capital allocation: Use our scenario matrices to prioritize investments that hedge both purity tightening and carbon constraints. For example, on-site electrolysis may be preferred for wafer fabs seeking lower embedded emissions and tight purity control — but the economics vary by electricity price regimes; our report quantifies these crosswinds.
- Procurement & supply security: Convert our supplier scorecards into RFP requirements. Insist on verified assay limits (including third-party sampling protocols aligned to ISO 14687:2025) and embed audit clauses for carbon intensity reporting.
- Operational risk management: Use the safety and standards digest to update plant safety cases, especially where electrolyzers and new storage modes are deployed, to comply with CEN ISO/TS 15916:2026 guidance.
- Commercial structuring: Adopt our recommended contract clauses that protect buyers from inadvertent quality drift (e.g., impurity excursions) and from emissions intensity misreporting.
- Deal origination: Sales and business development teams should use our anonymized project pipeline and demand timing windows to prioritize commercial effort and structure pilot-to-scale pathways with strategic customers.
Investment, M&A and partnership playbook
Given the market size trajectory and moderate supplier concentration, the optimal investment posture differs by investor type:
- Strategic acquirers should look for capability-based targets (analytical labs, cryogenics logistics, local on-site engineering houses) that can be integrated rapidly to secure quality and service differentiation.
- Financial investors benefit from platform plays: aggregating regional providers with standardized QA and carbon reporting systems creates a scalable, higher-margin business model.
- Project developers should prioritize modular, replicable electrolyzer + storage + purity-conditioning packages that reduce project execution risk and accelerate payback under 2026 pricing environments.
Final note — a trailer, not the full film
This preview highlights why 2026 is a strategic inflection point for high purity hydrogen: tightening standards, growing end-use demand, and an evolving competitive field create both risks and sharp opportunities. PW Consulting’s full High Purity Hydrogen Market report contains the granular intelligence you will need to act decisively — including project-level data, supplier scorecards, contract language templates, and downloadable financial models that let you stress-test capital and procurement choices against a range of regulatory and price scenarios.
For boards, deal teams, and operational leaders planning for 2026 and beyond, this report is designed to be the operative playbook. Reach out to access the comprehensive dataset, executive dashboards, and implementation modules that convert insight into immediate action.
For detailed analysis of this topic, please visit the official page: High Purity Hydrogen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com