

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
AI Surveillance Camera Market to Reach USD 34.31M by 2032 with 10.93% CAGR — PW Consulting

AI Surveillance Camera Market: Strategic Imperatives for 2026 — PW Consulting Preview
As organizations plan capital allocation, product roadmaps, and procurement strategies for 2026, the AI surveillance camera market is emerging from a period of maturation into one defined by accelerated edge intelligence adoption, supply-chain realignment, and regulatory friction. PW Consulting’s full market study (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) quantifies these forces and translates them into operational levers for corporate decision-makers. This preview outlines the strategic value of the report for enterprise stakeholders while preserving the granular segment-level intelligence that is available via the full report.
AI Surveillance Camera Market
Market at a Glance: Growth Trajectory and Concentration
Our synthesis shows the market expanding steadily through 2032, underpinned by strong demand for edge AI capabilities across security, infrastructure management, and industrial safety use cases. Using 2025 as the base year, PW Consulting models the market growing at a compound annual growth rate of approximately 10.93% across the 2026–2032 forecast window. The historical series (2020–2025) demonstrates a clear inflection as AI-enabled devices began to replace legacy cameras, and our forecast anticipates continued acceleration driven by smarter edge processors and wider AI model deployment on-device.
AI Surveillance Camera Market
From a competitive concentration perspective, the market displays moderate concentration: the top three suppliers control a meaningful portion of market revenues, and the top five increase that share substantially. This structure creates a set of strategic opportunities for challengers and niche specialists while also signaling where incumbents can consolidate positions through product depth, vertical integration, or channel partnerships.
AI Surveillance Camera Market
Why 2026 Is a Decision Point for Enterprises
- Procurement and CAPEX timing: The 2026 procurement cycle will be shaped by product refreshes that embed new application-specific NPUs and improved sensors. Our analysis shows that choosing when to invest—now or in later refresh cycles—can have material implications for total cost of ownership and time-to-value for analytics projects.
- Supply-chain resiliency: Extended lead times for NPU-enabled SoCs and high-dynamic-range CMOS sensors (reporting at 20–30 weeks as of mid‑2026) mean that procurement windows and component sourcing strategies must be planned 6–9 months ahead for large rollouts. Sourcing alternatives, buffer strategies, and collaborative supplier contracts will be decisive.
- Regulatory and tariff exposure: With trade measures such as continuing Section 301 tariffs on certain products of Chinese origin still in force, organizations must weigh tariff exposure against vendor capabilities. The tariff environment is actively driving supply chain diversification toward Taiwan and Southeast Asia—an operational trend with budgetary and compliance implications for 2026 projects.
- Operationalizing edge AI: The move from proof-of-concept to enterprise-wide deployment depends on integrated hardware-software stacks, model lifecycle management at the edge, and interoperable APIs. 2026 will favor vendors and integrators that can demonstrate streamlined deployment, reduced false-alarm rates, and explainable model behavior in live environments.
Practical Takeaways Contained in the Full Report
Our full-market report is organized to support strategic decisions and operational planning. Highlights of practical, actionable content include:
- Scenario-based demand forecasts and roll-up revenue projections (base year 2025; forecast 2026–2032) to inform budgeting and revenue planning.
- Vendor capability maps and technical scoring that assess edge AI compute, sensor performance, low-light imaging, and thermal integration—designed for CIOs and product procurement teams.
- Supply-chain playbooks that address lead-time management, alternative sourcing options, and inventory buffer sizing in response to current semiconductor bottlenecks.
- Regulatory risk matrices that align procurement decisions to tariff regimes, data-privacy constraints, and local certification requirements.
- Commercial models for procurement—OPEX vs. CAPEX, managed services, and hybrid models—calibrated to ROI thresholds typical in security and industrial deployments.
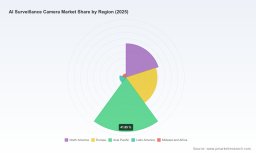
To preserve competitive value, the report deliberately withholds the fine-grained regional and application-specific revenue breakdowns in this public preview; these segmentation layers are presented in full within the paid study to support market-entry, channel prioritization, and go-to-market planning.
Competitive Landscape: How Leading Players Are Positioning for 2026
The competitive dynamics are being reshaped by a mix of silicon advances, model innovation, and differentiated go-to-market approaches. PW Consulting’s company profiles and benchmarking section provide granular assessments of product architecture, edge capability, and vertical focus. Here is a high-level appraisal of the strategic moves taken by core vendors:
- Axis Communications AB (Lund, Sweden) — Axis has leaned into bespoke silicon with its ARTPEC family, embedding advanced AI analytics into network dome and block cameras. Recent ARTPEC-9-powered releases emphasize low-light performance and integrated on-device analytics, targeting municipalities and commercial real estate customers seeking reduced latency and on-board processing resilience.
- Hangzhou Hikvision Digital Technology Co., Ltd. (Hangzhou, China) — Hikvision’s latest DeepinViewX bullet cameras leverage large-scale AI models to improve perimeter detection and reduce false positives. Their strategy focuses on high-volume, model-driven enhancements that expand video-content-analysis (VCA) ranges in perimeter and public-safety contexts.
- Dahua Technology Co., Ltd. (Hangzhou, China) — Dahua is specializing in thermal and hybrid camera systems for industrial-safety use cases, such as overheating detection and plant safety. This product posture aligns with industrial digitalization programs and the increasing demand for predictive safety analytics.
- Bosch Security Systems GmbH (Gerlingen, Germany) — Bosch continues to target critical infrastructure and perimeter security with industrial-grade PTZ and thermal AI cameras that emphasize robustness, long service life, and certified performance for mission-critical deployments.
- Honeywell International Inc. (Charlotte, United States) — Honeywell is integrating AI video solutions within broader enterprise and smart-building platforms, offering end-to-end solutions that appeal to large enterprises and infrastructure operators seeking vendor consolidation across building automation and security.
Our competitive analysis highlights that product differentiation is no longer solely about optics and resolution; it is now a systems-level battle—AI model robustness, edge compute efficiency, cybersecurity posture, serviceability, and channel strength determine long-term competitive advantage.
Supply-Chain and Technology Dynamics
Two operational realities will dominate procurement and product development conversations in 2026:
- Semiconductor and component lead times: NPUs and high-dynamic-range CMOS sensors continue to face extended lead times (20–30 weeks), creating scheduling risk for large rollouts. Procurement teams must integrate supply forecasts into project timelines and consider multi-sourcing contracts or forward-buy strategies for critical components.
- Geopolitical and trade effects: Tariff regimes on certain Chinese-origin products remain in place, prompting many buyers and OEMs to re-evaluate vendor footprints and manufacturing footprints. Organizations that proactively realign manufacturing or sourcing toward diversified nodes will reduce cost volatility and regulatory exposure.
Implications for Key Stakeholders
- Security and facilities leaders should treat 2026 as a year to standardize on AI-capable hardware platforms and demand vendor roadmaps that guarantee model updates and explainability over a multi-year horizon.
- Procurement teams must embed supply-risk KPIs into contracts, focusing on lead-time guarantees, alternative supply options, and tariff-mitigation clauses.
- Product and R&D leaders should prioritize modularity—separable sensor modules, updateable edge model frameworks, and clear software-development kits to accelerate integration and reduce lifetime maintenance costs.
- Investors and strategy teams will find M&A and partnership opportunities where specialist players offer unique thermal, industrial, or analytics capabilities that can bolt onto broader platforms operated by the large incumbents.
What PW Consulting Recommends for 2026 Planning
- Adopt a phased deployment strategy that accounts for semiconductor lead times and allows operational learning from pilot installations before full-scale rollouts.
- Negotiate supplier agreements that include capacity commitments and priority allocation for critical AI SoCs and sensors.
- Prioritize vendors that publish transparent model governance practices and provide lifecycle management for edge models and firmware updates.
- Where tariff exposure is material, evaluate near-shore or alternative manufacturing partnerships to preserve competitiveness and reduce compliance risk.
Closing: The Strategic Value of the Full PW Consulting Study
For executives planning product investments, large-scale rollouts, or market-entry moves in 2026, PW Consulting’s comprehensive study provides the quantitative backbone and qualitative interpretation necessary to make informed choices. The full report combines scenario-driven forecasts (anchored to the 2025 base), supplier benchmarking, regulatory impact assessments, and supply-chain playbooks—all calibrated to real-world procurement and deployment constraints.
This preview is designed to surface the critical strategic themes and operational trade-offs that will define success in 2026. For the detailed regional and application-level segmentation, vendor scorecards, and executable deployment templates, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: AI Surveillance Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com