

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Bed Market to Hit USD 6,509M by 2032 at 5.9% CAGR

Medical Bed Market 2026: Strategic Preview for Decision Makers
As healthcare delivery continues to evolve under pressure from aging populations, higher acuity, and tightening provider budgets, the medical bed market has become a critical strategic frontier for manufacturers, health systems, and investors. This preview, prepared by PW Consulting’s senior industry analysts, synthesizes the market trajectory, competitive dynamics, regulatory inflection points, and pragmatic playbooks that will matter most in 2026. It is designed to signal the high-value conclusions of our full market study while intentionally withholding detailed segment-level tables and models to encourage direct engagement with the full report.
Medical Bed Market
Market snapshot: Where we are and where we are headed
-
Historical momentum: The global medical bed market expanded steadily through the early 2020s, reflecting a combination of replacement cycles in mature systems and capacity investments in growth markets.
Medical Bed Market -
Scale in context: Our consolidated model shows the global market at roughly USD 4.4 billion in the base year (2025), up from approximately USD 3.25 billion in 2020.
Medical Bed Market -
Forward view: Across our primary forecast scenarios (2026–2032), the market grows at a core CAGR of 5.9%, reaching the multi‑billion-dollar range by the end of the forecast window. The trajectory is robust but differentiated by product complexity, care setting, and regulatory headwinds.
-
Concentration and competitive posture: The market exhibits mid-level concentration (top-three vendors account for roughly 42% of market revenues; top five approach half of the market), implying room for both scale players and focused specialists to capture meaningful share through product differentiation or narrow vertical plays.
What this report delivers — pragmatic intelligence for 2026 decisions
-
Actionable market-sizing and outlook: A transparent model (base year: 2025; historical window: 2020–2025; forecast: 2026–2032) that can be adapted to bespoke scenario inputs.
-
Go-to-market playbooks: Channel segmentation, procurement timing, and competitive positioning templates for OEMs, private-label manufacturers, and distributors.
-
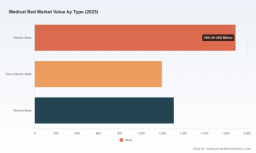
Product & technology roadmaps: Comparative analyses of electric, semi-electric, and manual platforms, including lifecycle cost calculators and upgrade pathways for smart features and connectivity.
-
Regulatory and reimbursement impact matrix: Quantified implications of standards updates and coverage policy changes on time-to-market and allowable pricing constructs.
-
Supplier benchmarking and supplier selection toolkits: Cost, capability, and compliance scorecards for manufacturing partners and component suppliers.
-
M&A and partnership playbook: Identification of targets and rationale—capability fills, go-to-market leverage, or geographic expansion—plus integration risk checklists.
-
Operational levers for hospital buyers: Total cost of ownership (TCO) frameworks, preventative maintenance optimization, and procurement timing recommendations to lower lifecycle expense.
Market dynamics shaping 2026 choices
-
Demand drivers: Aging demographics and rising chronic disease prevalence continue to increase long-term care and post-acute demand, while higher inpatient acuity and ICU utilization drive demand for feature-rich acute care beds.
-
Technology integration: Smart beds—with integrated sensors, remote monitoring, and analytics—are shifting value from capital pricing to outcomes enablement. Early adopters are recouping costs through reduced falls, shortened LOS, and more efficient staffing models.
-
Cost pressure and product stratification: Health systems are increasingly differentiating bed portfolios by care intensity. This bifurcation creates opportunities for premium, software-enabled platforms in acute and critical care, and for lower-cost, high-durability solutions in home and lower-acuity settings.
-
Regulatory inflection: Standards updates and certification windows materially affect product roadmaps. For example, an important transition window for conformity declarations to IEC 60601‑2‑52 closed in early July 2026, and safety standard updates in 2026 raise the bar for design and documentation.
-
Reimbursement and procurement policy: State-level coverage criteria and documentation rules—such as those revised in certain U.S. jurisdictions in 2025—create local variability that influences replacement cycles and total addressable market timing.
Competitive landscape — strategies that win in 2026
The market is populated by legacy OEMs with broad hospital relationships, specialist brands focused on long-term care or homecare, and new entrants leveraging digital platforms. Leading players differentiate along three dimensions: integrated clinical capability, caregiver-centric ergonomics, and cost-to-serve.
-
Baxter International: Emphasizes smart ICU and acute care portfolios with integrated data platforms—positioned to compete on clinical outcomes and enterprise integrations.
-
Stryker: Focused on caregiver efficiency and safety alarms with wireless connectivity; recent product introductions underscore a push to standardize across multi-regional footprints.
-
LINET Group SE: Competes with AI-driven monitoring and automated safety features for intensive-care-grade platforms; their strategy is centered on premium feature differentiation.
-
Arjo AB: Targets the hospital and long-term care interface, emphasizing repositioning and pressure-injury prevention for value-based procurement discussions.
-
Invacare & Drive DeVilbiss: Focused on accessible and cost-effective solutions for homecare and lower acuity segments—an important play as care shifts away from hospitals.
-
Paramount Bed, Stiegelmeyer, Midmark, Medline, Joerns, Umano Medical: Range from configurable clinical platforms to modular and wall-integrated systems; many pursue channel partnerships and aftermarket services to extend lifetime value.
Strategically, winning vendors will combine clinical evidence, device interoperability, and economical service models. Middle-market consolidation and targeted partnerships—particularly around software ecosystems—are likely in 2026 as platform economics become central to differentiation.
Recent developments with outsized implication
-
Product launches: New platform introductions in 2025–2026 underscore the urgency for incumbents to refresh hardware and software stacks. Notably, multi-region bed launches focused on caregiver efficiency signal an acceleration in product cycle timing.
-
Standards updates: Safety standards were updated in 2026, requiring updated design and verification activity; organizations that anticipated this shift are gaining a time-to-market advantage, while late adopters face rework risks and potential market exclusion.
-
Procurement policy shifts: Changes in documentation requirements and coverage rules in certain U.S. states have altered procurement timelines and the documentation burden on suppliers, increasing marginal compliance costs for smaller vendors.
Strategic implications for 2026 decision-makers
-
For OEMs: Prioritize modular platforms with software upgrade pathways. Protect R&D investment through phased launches—start with core clinical features, follow with over-the-air software enhancements linked to demonstrable caregiver efficiency gains.
-
For health systems: Reframe procurement around TCO and outcomes, not just capital price. Introduce pilot programs that track falls, pressure injuries, and staff time before committing to wide-scale rollouts.
-
For investors & M&A teams: Seek targets that either provide unique software/analytics capabilities or that occupy adjacent channel specializations (e.g., homecare durable medical equipment) to hedge against hospital capital variability.
-
For service providers: Build aftermarket programs emphasizing predictive maintenance and consumables replenishment. These recurring revenue streams materially change unit economics and buyer lock-in.
-
Compliance and product teams: Accelerate conformity evidence generation for updated standards and audit trails for state-level coverage policies. Non-compliance now has a more immediate commercial impact given the closure of transitional declaration windows.
Methodology & scenarios — rigorous, transparent, adaptable
-
Dataset foundation: The model uses a 2025 base year with a historical series covering 2020–2025 and a forecast horizon running to 2032. Our central projection applies a CAGR of 5.9% under the baseline macro assumptions.
-
Scenario stress-tests: The full report includes upside and downside scenarios that vary deployment speed of smart features, reimbursement behavior, and component supply-chain disruption timelines.
-
Data integrity: Revenue and growth estimates triangulate public filings, primary interviews with procurement leads, and proprietary shipment and pricing datasets. We flag where sample sizes are thin and recommend follow-up primary research for bespoke decisions.
Why this matters in 2026 — and what to do next
By 2026, the medical bed market is no longer a commoditized hardware play. It is a systems decision: selecting beds now commits health systems to specific workflows, IT integrations, and service economies for years. Manufacturers that lock in software-enabled services, validate clinical impact, and navigate evolving safety standards will secure enduring differentiation and higher-margin revenue streams.
PW Consulting’s full report provides the granular regional, type, and application splits, detailed pricing ladders, service-cost models, and downloadable financial templates that enterprises need to translate this strategic preview into executable plans. In keeping with this brief’s “trailer” approach, we have deliberately withheld the detailed segment tables and raw datasets here—these are included in the core research package.
Next steps
-
Download the full report for complete segment-level models, supplier scorecards, and TCO calculators.
-
Schedule a briefing with our senior analysts for a bespoke scenario run—tailored to your product portfolio, geographic focus, or procurement cycle.
PW Consulting’s Medical Bed Market study is designed to convert insight into action. If your 2026 plans include product launches, R&D prioritization, procurement changes, or M&A activity in the medical bed space, this research will sharpen execution and reduce strategic risk.
For detailed analysis of this topic, please visit the official page: Medical Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com