

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Power Transmission Equipment to Hit USD 301.5M by 2032 at 6.99% CAGR

Electric Power Transmission Equipment Market — Strategic Imperatives for 2026
Introduction: Why this briefing matters for 2026 decisions
As power systems evolve to meet decarbonization, resilience and electrification targets, executives must make near-term capital, procurement and partnership choices that lock in multi‑year performance. PW Consulting’s new Electric Power Transmission Equipment Market study synthesizes market-level forecasts, supplier maps, regulatory dynamics and practical playbooks so leadership teams can convert macro trends into defensible 2026 actions. This overview demonstrates the analytical depth you can expect; to preserve the commercial value of the full study we intentionally withhold the underlying sub‑segment tables and granular regional splits — the full dataset and interactive models are available through the report portal.
Electric Power Transmission Equipment Market
Market snapshot: validated growth trajectory and what it implies
Using a 2025 base year, our topline market model shows the global electric power transmission equipment market has expanded materially since 2020, rising from a quantified baseline to a larger 2025 valuation (USD, Million) and continuing to grow through the forecast window. PW Consulting projects a compound annual growth rate (CAGR) of 6.99% over the 2026–2032 forecast period, taking the market from its 2025 base to a materially larger market by 2032. This pace reflects a blend of core grid reinforcement programs, new long‑distance links (including HVDC), and replacement cycles driven by regulatory change and technology refresh.
Electric Power Transmission Equipment Market
What this means for 2026: the market is neither an episodic construction boom nor a slow‑moving commodity cycle. It is a structural growth market with pockets of accelerated demand — and therefore a landscape where timing, product positioning and supply chain resilience will determine which players capture outsized returns.
Electric Power Transmission Equipment Market
What the full report delivers (operational, actionable content)
- Granular market model (interactive): time‑series demand, price assumptions, scenario toggles and sensitivity analyses keyed to raw material and labor cost shocks.
- Segment frameworks: product, application and regional architectures with editable assumptions for customized forecasting (note: core split tables are reserved for report access).
- Competitive intelligence dossiers: capability maps, go‑to‑market strategies, recent wins and product roadmaps for the leading incumbents and fast followers.
- Procurement & supply chain playbook: hedging strategies for aluminium and other critical inputs, dual‑sourcing templates, and localized manufacturing decision matrixes.
- Regulatory & standards tracker: implications of SF6 phase‑down, interregional transfer requirements, and large transmission program pipeline reviews (including program-level schedules and contracting models).
- Investment and M&A guide: valuation ranges (public comparables), integration playbooks and priority targets for bolt‑on capabilities (digital, HVDC systems, SF6‑free GIS).
- Implementation tools: supplier scorecards, risk registers, capital expenditure phasing templates, and a 12–24 month tactical roadmap with critical milestones for 2026 execution.
Market dynamics: drivers, headwinds and material inputs
Several structural forces are shaping equipment demand and margins in 2026:
- Grid expansion and interconnection: Transmission program mandates in large markets are creating sustained demand for long‑distance links and reinforcement works. Independent reliability assessments and national planning bodies are formalizing multi‑year build schedules that increase certainty for project pipelines.
- Technology migration: HVDC, SF6‑free GIS/AIS, and digital sensing/automation are transitioning from niche to mainstream. Vendors that can commercialize low‑GWP insulating technologies and integrated digital services will capture premium positioning.
- Raw material volatility: A notable rise in aluminium prices in 2026 — exceeding prior projections — has reintroduced input‑cost risk, particularly for overhead lines and conductor-intensive projects. Our report models both pass‑through and margin‑absorption scenarios to support contract negotiation and hedging strategies.
- Labor & execution risk: Transmission work remains labour‑intensive. For example, the US transmission, distribution and storage sector continued to employ large workforces at resilient median wages, underscoring both capacity and cost considerations for large program delivery.
- Regulatory pressure: Phase‑down expectations for SF6 and increasingly stringent interregional transfer requirements are altering product specifications and procurement criteria; early movers have a technical and contracting advantage.
Competition and concentration: what the marketplace looks like
The transmission equipment market exhibits moderate concentration: the top three players account for a majority share of installed capability, and the top five increasing that concentration slightly. This structure creates a market where global incumbents retain scale advantages in project delivery, but regional champions and specialized firms are consistently winning on localization, cost and niche technologies.
Key participants profiled in the report include global system integrators and equipment manufacturers such as ABB, Siemens Energy, GE Vernova, Schneider Electric, Eaton, Mitsubishi Electric, Toshiba Energy, Hyosung Heavy Industries, CG Power, BHEL, Hubbell and SPX Transformer Solutions. Each is mapped across capability dimensions including:
- High‑voltage equipment portfolio (transformers, breakers, GIS/AIS)
- System solutions (HVDC, substations, turnkey delivery)
- Service and digital offerings (grid sensors, asset management)
- Geographic footprint and localization potential
Recent public developments underscore strategic trajectories: Siemens Energy’s prominent presence at major trade forums in 2026 highlights a push toward SF6‑free and digital grid offerings; GE Vernova’s awarded contracts for high‑voltage circuit breakers demonstrate continued project execution momentum; and product launches from major vendors show the race to combine hardware with sensing and services. These moves fit broader competitive playbooks — scale plus technology adjacency — captured in our firm profiles and win‑loss analysis.
Strategic priorities for 2026 — recommended executive actions
Based on our analysis, companies should prioritize three near‑term decisions in 2026 to materially improve outcomes across 2026–2028:
- Hedge supply exposure and de‑risk procurement: Execute aluminum and key‑component hedges tied to project pipelines; qualify secondary suppliers and implement price‑escalation clauses in new contracts. Target: reduce raw‑material price exposure on committed orders by a material share within 6–9 months.
- Accelerate SF6‑free product adoption and certification: Fast‑track type‑testing and standards alignment for SF6‑free switchgear and substations. This is both a compliance and commercial differentiator given accelerating regulation.
- Bundle hardware with digital services: Move beyond equipment sales to recurring‑revenue service models (grid sensors, predictive maintenance, digital twins). Allocate near‑term capex to pilot service contracts on strategic transmission projects.
- Localize strategic capacity selectively: Use a country‑by‑country matrix to identify where local manufacturing or JV structures will improve bid competitiveness and shorten delivery times for long‑lead items.
- Prioritize HVDC and offshore transmission plays: Align R&D and BD resources to HVDC converter systems and long‑distance cable portfolios where unit economics and project pipelines point to above‑market growth.
- Scenario‑based capital planning: Adopt the report’s sensitivity scenarios (aluminum shock, labor premium, accelerated SF6 phase‑down) to stress‑test 2026 CAPEX and contract commitments.
How strategy, procurement and investment teams should use this report
- Executives: Use the topline scenario outputs to set corporate investment priorities and M&A criteria for the next 18 months.
- Product & R&D: Prioritize certification paths and modular designs that lower cost to certify across jurisdictions and support SF6‑free migrations.
- Procurement: Adopt the supplied hedging templates, supplier‑scorecard and dual‑sourcing playbooks to reduce delivery and input‑cost volatility.
- Business Development: Leverage the competitive dossiers and project pipeline maps to target tenders where incumbents are weakest on localization or service propositions.
- Investors & M&A teams: Use the valuation frameworks and regional risk overlays to size potential returns and integration risks for bolt‑on acquisitions.
Concluding note — what’s behind the curtain
PW Consulting’s Electric Power Transmission Equipment study blends a robust market model (base year 2025) with program‑level project mapping, supplier capability assessments and pragmatic execution tools designed for 2026 decision cycles. The headline numbers presented here demonstrate a clear, compound growth profile through 2032 and validate the strategic urgency around SF6‑free technologies, HVDC, supply‑chain resilience and service monetization.
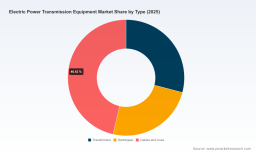
To preserve the report’s commercial integrity we have not published the granular regional, type and application split tables in this preview. The full study contains the interactive spreadsheets, segment breakdowns, and contract‑level pipeline views required to build your 2026 procurement calendar, CAPEX plan and M&A shortlist. Contact PW Consulting via the report portal to access the complete dataset, downloadable dashboards and a tailored briefing with one of our senior industry consultants.
For detailed analysis of this topic, please visit the official page: Electric Power Transmission Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com