

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Construction Materials Market to Hit USD 1,452.72B in 2025; 3.95% CAGR Outlook

Construction Materials Market 2026: Strategic Imperatives for Executive Decision‑Making
Executive overview
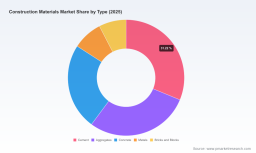
The construction materials sector is navigating a period of structural transition. After steady expansion through the first half of the decade, the global market reached approximately USD 1.45 trillion in our base year (2025). Our modelling projects continued expansion through the forecast window (2026–2032) at a compound annual growth rate of 3.95%, taking the industry toward an almost USD 1.9 trillion market by the end of the horizon. These headline figures mask meaningful divergence beneath the surface — between commodity and specialty segments, between regions with renewed public infrastructure investment and those facing cyclical residential slowdowns, and between firms that are integrating vertically and those focused on product differentiation.
Construction Materials Market
For executives planning capital allocation, pricing actions, or M&A in 2026, this research is not a retrospective recounting. It is an action-oriented guide that translates macro momentum into operational choices, risk mitigation, and value capture strategies for the next 18 months and beyond.
Construction Materials Market
Why 2026 is a pivot year
-
CapEx rebalancing: A wave of capacity investments completed in 2024–2026 has shifted the supply landscape for higher-value construction chemistries and automated mortar production. These investments are now testing demand elasticity and logistics resilience in major metropolitan catchments.
Construction Materials Market -
Input price volatility: Raw-material supply tightness and geopolitical friction in energy‑ and feedstock‑sensitive regions have prompted input price repricing and selective manufacturer surcharge strategies. The result is a renewed emphasis on procurement resilience and product formulation efficiency.
-
Concentration and specialization: Market concentration remains moderate — the top three players account for roughly one third of industry sales, while the top five approach the mid‑forties percentage range — creating space for specialist players to capture margin via niche offerings or localized service models.
-
Sustainability and regulation: Regulatory pressure on embodied carbon, coupled with contractor and developer demand for low‑carbon alternatives, is accelerating reformulation and product certification initiatives. This is shifting R&D spend into lifecycle‑oriented solutions and creating first‑mover advantages for validated low‑carbon offerings.
What the PW Consulting report delivers — practical, transaction‑ready outputs
Our market study is deliberately built as a toolkit for 2026 decision-makers. The full report combines high‑granularity forecasting with executable frameworks so teams can move from insight to action within weeks, not months. Key deliverables include:
-
Proprietary demand model (2020–2032) with scenario toggles — baseline, downside, and accelerated green‑build adoption — allowing users to stress test revenue and utilization under multiple macro paths.
-
Price‑to‑margin sensitivity matrices for key product families and formulations, enabling finance teams to quantify pass‑through potential and margin compression under different raw‑material trajectories.
-
Supply‑chain heatmaps and critical‑node risk ratings that flag single‑source exposures, logistic bottlenecks, and country‑level permitting risks relevant to 2026 capital plans.
-
Commercial playbooks for regional go‑to‑market moves, from bolt‑on acquisitions to distribution partnerships and service‑led differentiation (e.g., automated mortar provision, turnkey admixture systems).
-
Regulatory and sustainability tracker with certification timelines and estimated compliance cost ranges to support product roadmap prioritization.
-
A curated M&A playbook and valuation benchmarker tailored to different corporate strategies — scale, capability, or regional entry — with runnable synergies and integration checklists.
Competitive landscape: who is reshaping the industry
The competitive picture is characterized by a mix of diversified chemical majors and specialist construction‑chemicals houses. Our analysis highlights strategic moves and operational actions that will shape market share and margin trajectories in 2026.
-
Sika AG — Sika is aggressively expanding manufacturing automation and localized mortar capacity to capture urban retrofit and metropolitan new‑build projects. Recent commissioning of automated mortar capacity in the northeastern US is emblematic of a strategy that pairs production proximity with service‑level differentiation.
-
BASF SE — Leveraging scale in performance chemicals, BASF has focused on improving supply reliability and capacity for high‑performance dispersants. Their investments in Asia aim to reduce lead times for regional coatings and construction markets, a direct response to global supply chain pressures.
-
Henkel AG & Co. KGaA — Henkel’s adhesive and sealant businesses continue to pursue solutions that integrate with modular construction and prefabrication value chains, positioning the firm to benefit from productivity‑led shifts in building practices.
-
Mapei S.p.A. — As a specialist in tile adhesives, waterproofing, and flooring systems, Mapei maintains a product‑innovation focus, targeted at contractor productivity gains and advanced substrate systems.
-
Arkema S.A. — Arkema’s emphasis on performance additives and functional polymers is aligned with growing demand for higher‑value formulations, particularly where long‑term durability and sustainability credentials are decisive for specification.
-
Wacker Chemie AG — Input‑driven cost pressure led to price actions in polymer product lines earlier in 2026, an indicator of the sector’s vulnerability to feedstock and freight volatility. These moves sharpen the need for end‑to‑end procurement strategies.
-
RPM International Inc. — RPM remains a consolidator at the specialty end — nimble brands that win on contractor trust and niche formulation advantages.
-
Saint‑Gobain Construction Chemicals — A recent series of acquisitions illustrates a consolidation play to combine additive technologies and lightweight concrete know‑how with established distribution channels.
Recent developments that matter for 2026 planning
-
Manufacturers are expanding automated downstream capacity to reduce finished‑goods lead times and service costs in high‑density urban markets.
-
Major chemical producers have commissioned new production lines in Asia to address regional supply reliability — a structural response to the fragility revealed by recent disruptions.
-
Selective price adjustments by polymer suppliers in 2026 underscore the ongoing sensitivity of margins to feedstock and freight dynamics; procurement teams should prepare for episodic cost shock scenarios.
-
Strategic acquisitions by large building materials firms are accelerating capability stacking in concrete additives and lightweight technologies, altering competitive thresholds for mid‑market players.
Actionable strategic priorities for 2026
Translating our findings into a 12–24 month action plan, we recommend executives prioritize the following:
-
Stress‑test capacity plans against three demand scenarios and embed trigger points for greenfield vs. brownfield investments; avoid committing to large new‑build capacity without modularity or redeployability clauses.
-
Implement dynamic pricing frameworks and raw‑material hedging policies that balance competitive positioning with margin protection; consider tiered pass‑through clauses for long‑term contracts.
-
Accelerate product reformulation where lifecycle‑based procurement is emerging in major developer tenders; invest in certification pathways now to become a preferred supplier for low‑carbon projects.
-
Target M&A and bolt‑on acquisitions that either fill capability gaps (e.g., admixtures or lightweight concrete tech) or provide last‑mile manufacturing nodes in urban catchments to capture service premiums.
-
Reconfigure supplier bases to reduce single‑source exposure and increase dual‑sourcing for critical feedstocks, including contractual commitments from tier‑one chemical suppliers tied to reliability KPIs.
-
Deploy commercial pilots for value‑added service models (just‑in‑time mortar supply, technical installation support, performance guarantees) to transform transactional relationships into annuity streams.
What we do not disclose here — and why the full report matters
This briefing intentionally omits the granular regional, product and application splits that underpin the models and valuation work in the full study. Those segment‑level forecasts, pricing ladders, and downloadable financial models are core to transactional diligence and strategic planning; we reserve them for the full report to ensure readers can act on validated, source‑level data rather than summary impressions.
Why PW Consulting’s Construction Materials report is a practical edge for 2026
Our study combines an empirically calibrated market model (2020–2032), competitive profiling, a proprietary supplier database, and scenario‑ready financial tools. It is designed to be used by strategy teams, corporate development groups, and procurement functions to shorten decision cycles and reduce downside risk when committing capital or executing M&A in 2026. The work integrates public disclosures, proprietary surveys, and field interviews with procurement and engineering leads to ensure recommendations are implementable and defensible.
For executives who must convert sector dynamics into measurable business outcomes this year — whether that means adjusting pricing mechanics, prioritizing investments, or pursuing capability‑driving acquisitions — the full construction materials market study provides the data, frameworks, and playbooks to make those choices with confidence.
To access the complete dataset, scenario models, and the transaction playbook, request the full report and toolkit on our research portal.
For detailed analysis of this topic, please visit the official page: Construction Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com