

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bathroom Vanities Market $76.15M by 2032; 7.3% CAGR

Bathroom Vanities Market — 2026 Strategic Outlook
As PW Consulting’s lead industry analyst, I present a focused, executive-grade introduction to our Bathroom Vanities Market study. This briefing explains why the study is essential for corporate leaders planning strategy in 2026, highlights the high-level, data-driven signals that will shape near-term choices, and outlines the practical, decision-ready content contained in the full report. The analysis below demonstrates the depth of our work while intentionally withholding the detailed subsegment tables and region/application splits that subscribers will find in the full deliverable.
Bathroom Vanities Market
Context and headline market trajectory
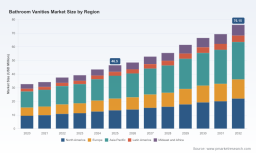
Using a consistent base year of 2025 and a historical window covering 2020–2025, our market model shows clear expansion ahead. The global market measured USD 32.69 Million in 2020, grew to USD 46.5 Million by 2025, and is forecast to reach USD 48.5 Million in 2026 as the forward curve begins a sustained recovery. Over the 2026–2032 forecast period our model projects a compound annual growth rate (CAGR) of 7.3%, bringing the market to approximately USD 76.15 Million by 2032 (all values USD, revenue unit: Million). These headline figures establish a constructive growth backdrop, but they conceal important structural shifts that should drive different strategic responses across manufacturers, retailers, distributors and investors.
Bathroom Vanities Market
Why this study matters to decision-makers in 2026
- Tariff-driven disruption. Section 232 trade measures on wooden kitchen cabinets and bathroom vanities have materially increased import duties, rising from 25% to 50% effective January 1, 2026. That change abruptly alters landed costs, supplier economics and sourcing calculus for companies that depend on imports or global supply chains.
- Moderate market concentration and consolidation opportunity. Market concentration metrics reveal a landscape where the top three players account for roughly one-third of demand (CR3 ~32%), while the top five control under half (CR5 ~47%). The structure supports both defensive scale strategies by incumbents and opportunistic roll-up plays for investors seeking to create national champions.
- Product and channel bifurcation. Premiumization and modularization trends continue alongside strong demand from traditional residential remodel and new-construction channels. Retailers and manufacturers face divergent margin dynamics by channel, creating an urgency to refine channel strategies, SKU portfolios, pricing and fulfillment.
- Near-term volatility, long-term growth. While 2026 will reflect tariff-related cost pressures and some supply-chain rebalancing, the medium-term trajectory—driven by remodeling cycles, design innovation and material evolution—remains positive under the projected 7.3% CAGR to 2032.
What the full report contains — practical, actionable insight
Our objective is to equip executives with actionable choices, not just descriptive charts. The full report (base year 2025) delivers:
Bathroom Vanities Market
- Top-down and bottom-up market sizing (historical 2020–2025; forecast 2026–2032) with transparent methodology and stress-test scenarios under different tariff and macro conditions.
- Demand drivers and elasticity models that quantify sensitivity to price, material costs and trade policy shocks.
- Channel profitability matrices for major go-to-market routes (direct-to-consumer, big-box, specialty dealers, builders and commercial channels), including SKU profitability by typical configurations.
- Supply chain and sourcing playbooks—cost-to-serve models, landed-cost calculators, nearshoring ROI frameworks, and supplier scorecards that identify candidates for vertical partnerships or insourcing.
- Competitive intelligence dossiers on major players, including product portfolios, capacity and capability maps, and strategic triggers for potential M&A targets.
- Innovation and design radar highlighting rising materials, finishes and configuration trends that influence margin and customer acquisition.
- Scenario templates and board-ready slides that allow management teams to run three strategic responses to the tariff shock: defensive pricing, offensive domestic scale-up, and a hybrid hedged approach.
To preserve the signal-to-noise ratio of this preview and to maintain the commercial value of the full dataset, we do not disclose the granular regional or application splits in this article. Those tables and interactive models are available with the full report.
Data-driven strategic signals (what the numbers imply)
- Cost structure re-optimization is urgent. The Section 232 tariff increase to 50% (effective January 1, 2026) is a structural cost shock for any player with significant import exposure. Our sensitivity analysis shows landed-cost pass-through varies by channel and contract type; firms that can partially absorb or strategically reprice will protect share, but margin erosion is unavoidable without operational changes.
- Domestic manufacturers can gain share—but must scale. Domestic producers that already have manufacturing and distribution footprints are positioned to capture demand from repatriated sourcing. However, winning sustained share requires aligning SKU breadth, dealer partnerships and lead times to the rapid reorder cycles typical of remodel-driven demand.
- Product differentiation reduces price elasticity. Brands that invest in clear design language, material innovation and installation-friendly modularity will face lower price elasticity and can defend margins more effectively than private-label commodity lines.
- Dealers and big-box partners will intensify commercial negotiations. With rising supplier costs, expect channel partners to seek better terms, seasonal buy-downs, and private-label expansion. Firms should prepare countermeasures—e.g., faster optical inventory turns, better EDI integration, and exclusive SKUs.
- M&A becomes a credible pathway to scale. Given the current CR3/CR5 ratios, strategic consolidation can create synergies in procurement, distribution density and brand portfolio management. Investors should evaluate targets that provide either manufacturing capacity in non-import-exposed geographies or proprietary design capabilities.
Competitive landscape: what the market’s leading players are signaling
Our qualitative and quantitative scans identify distinct strategic archetypes among incumbent and emerging players:
- Heritage, craftsmanship-focused manufacturers (e.g., Strasser Woodenworks): These firms emphasize custom, built-to-order hardwood construction and premium positioning. Their strengths are brand, quality and the ability to command price premiums in the luxury segment, but scaling rapid-volume channels is often a challenge.
- Designer and luxury brands (e.g., James Martin Vanities): These players focus on curated design languages and collection marketing. They are well-placed to benefit from premiumization trends and can exploit trade shows and designer relationships—as evidenced by product showcases at KBIS 2026.
- Made-to-order cabinet specialists (e.g., Bertch Bath, American Woodmark): Their business models are tailored to builders and big-box retail, with lean manufacturing and configurable platforms. Tariffs push these players to re-evaluate sourcing and supplier contracts quickly.
- Stone/quartz-integrated suppliers and dealer-focused brands (e.g., Stonewood Bath): Value-added offerings—such as shallow-depth quartz tops—address dealer needs for easy merchandising and fast turnover. These product innovations reduce price competition and reinforce channel stickiness.
- Comprehensive bathroom system suppliers (e.g., Kohler): Large OEMs combine sink, fixture and vanity portfolios, which enables bundled solutions and cross-selling but requires careful channel governance to avoid channel conflict.
- Trade-show innovators and niche freestanding players (e.g., Sudio Design, Vaughan Bassett, TONA): Recent product launches at KBIS 2026 highlight market appetite for freestanding vanities, modern aesthetics and North America–focused launches—signals that design-led entrants are actively pursuing higher-margin niches.
Recommended 90–360 day playbook for executives (practical steps)
- First 90 days (stabilize): Conduct an immediate tariff exposure audit by SKU and channel; reprice where contracts permit; negotiate short-term freight and supplier relief; prioritize inventory that hedges against 2026 cost shocks.
- 90–180 days (adapt): Launch supply-chain pilots for nearshoring or dual-sourcing of key components; rationalize SKUs to remove low-margin, import-exposed items; create a premium SKU lane that can absorb higher margin requirements.
- 180–360 days (scale): Invest in capacity expansion or M&A targets that provide domestic footprint; accelerate digital dealer portals and integrated logistics for faster lead times; commit to one or two design-language-led collections with marketing support to lower price sensitivity.
How PW Consulting’s report supports board-level decisions
The full study delivers not only forecast tables but also executable playbooks: board-ready scenario analyses that quantify margin and cash-flow outcomes under alternative tariff, inflation and housing scenarios; supplier consolidation roadmaps with estimated synergy profiles; and an M&A heat map that ranks targets by integration complexity and value creation potential. For management teams weighing nearshoring capital allocation, the report contains an NPV-based factory expansion calculator calibrated for the bathroom vanities value chain.
Closing — strategic imperative for 2026
The Bathroom Vanities Market is at a policy and supply-chain inflection point. The market’s long-term growth dynamics remain attractive—the 2026–2032 7.3% CAGR is compelling—but the immediate environment requires fast, disciplined responses to tariff and sourcing shocks. Firms that move decisively to reprice thoughtfully, secure supply through diversification or domestic capacity, and invest in differentiated product propositions will emerge stronger. Our full PW Consulting report supplies the granular segmentation, financial models and playbooks that enable those choices; this preview outlines the strategic stakes and the specific decision levers that matter for 2026.
To access the complete dataset, interactive models and the full list of company profiles and scenario templates, please refer to the PW Consulting report page. The detailed regional, material and application-level splits are included in the subscriber edition and are intentionally omitted here to preserve the commercial value of those insights.
For detailed analysis of this topic, please visit the official page: Bathroom Vanities Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com