

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thermoelectric Modules to Reach USD 1,471M by 2032 at 9.29% CAGR

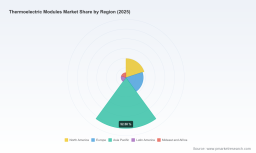
Thermoelectric Modules Market — Strategic Briefing for 2026 Decision‑Makers
As enterprises reassess product portfolios, manufacturing footprints, and R&D priorities for 2026, thermoelectric modules (TEMs) have shifted from niche components to strategic enablers across automotive, consumer, industrial, medical, and aerospace systems. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — maps this transition with quantitative rigor and actionable guidance. At the macro level, the global TEM market stood at approximately USD 790 million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of about 9.3% over the 2026–2032 horizon, reaching a materially larger opportunity by 2032. This trajectory reframes TEMs from tactical thermal elements into investable technology platforms for organizations that move decisively in 2026.
Thermoelectric Modules Market
Why this study matters to 2026 corporate strategy
- Investment timing: Rapid, but not runaway, growth (mid‑single to low‑double digit CAGR) creates a window to scale manufacturing, secure supply, and capture share before structural consolidation accelerates in the late 2020s.
- Technology inflection: Advances in miniaturization, thin‑film processes, multistage architectures, and integrated control electronics are enabling new applications with tighter performance and reliability requirements — favoring firms that synchronize product development with systems engineering.
- Supply‑chain choreography: Geographic shifts in production and targeted facility expansions are altering lead times and total cost of ownership. A targeted manufacturing or partner strategy in 2026 will materially affect EBITA and time-to-market through 2028.
- Competitive positioning: The market’s moderate concentration (top‑3 and top‑5 shares demonstrate a clear incumbent group) means scale advantages exist, but specialist players can still win in differentiated niches if they execute on product‑platform and channel strategies.
What PW Consulting’s report delivers (practical, decision‑ready content)
- Robust market sizing and forecast model (2020–2032) with scenario variants for demand shocks, commodity swings, and accelerated electrification — delivered as an editable financial model.
- Segment maps and value‑chain overlays by module type, end‑use application, and region — with targeted guidance on margin pools and value migration (note: this briefing intentionally omits granular segment figures; full tables are in the report).
- Supplier and OEM playbooks: go‑to‑market options (direct, distributor, OEM integrations), pricing levers, and sample contracts tailored to TEMs and assemblies.
- Technology radar and product roadmaps describing material choices, packaging trends, controller integration patterns, and reliability standards that materially impact adoption velocity.
- Manufacturing and capex decision framework: build vs. buy thresholds, footprint optimization, and ramp‑planning templates designed for 12–36 month execution cycles.
- M&A and partnership playbook with target archetypes, valuation heuristics, and a 12‑month integration checklist to accelerate capability capture.
- Regulatory, test, and qualification matrix that maps certification pathways (including telecom‑grade and aerospace/medical standards) to product launch timelines and incremental cost impacts.
- Primary research appendix: executive interviews, supplier audits, and plant‑level benchmarking that validate the forecast and stress key assumptions.
Market dynamics and strategic implications
Demand-side drivers are converging: automotive thermal management and comfort systems, tighter thermal budgets in high‑performance consumer devices, industrial process control, medical temperature management, and emerging waste‑heat recovery use cases are all extending TEM applications. On the technology side, two trends stand out — miniaturization (micro TECs and thin‑film approaches) and system integration (modules paired with precision controllers and embedded sensors). Companies that combine module competence with electronic control systems will capture a disproportionate share of higher‑margin assemblies.
Thermoelectric Modules Market
On the supply side, capacity expansion and regional manufacturing shifts are already visible. Notable moves by incumbent manufacturers to establish additional high‑technology facilities are lowering regional risk but also raising the bar on capital intensity and operational discipline. Material supply and process consistency remain key margin levers; organizations that secure materials and qualify alternative process routes in 2026 will be more resilient to price and lead‑time volatility.
Thermoelectric Modules Market
Competitive landscape — who matters and why
- Ferrotec Corporation — a global incumbent with deep capabilities in TECs and thermal assemblies. Its strategy includes capacity expansions in Southeast Asia to support higher‑volume, precision applications. For decision‑makers: Ferrotec represents scale, established OEM relationships, and a template for integrating module supply with system‑level thermal design.
- Crystal Ltd. — a manufacturer with broad product breadth across standard, multistage, micro, and high‑power modules. Their strength lies in modularity and high‑power density solutions for industrial and instrumentation customers.
- TEC Microsystems GmbH — a specialist in miniature and aluminum‑header TECs, with an expanded product series and recent reliability qualifications aligned to telecom and scientific markets. Their product engineering and qualification pedigree make them a preferred partner where miniaturization and Telcordia‑grade reliability are requisites.
- KRYOTHERM and Thermonamic — regionally strong players with flexible product portfolios, addressing both cooling and energy‑harvesting use cases, valuable as acquisition targets or regional partners.
- Specialist suppliers (Laird Thermal Systems, TE Technology, RMT, Gentherm, KELK) — each brings distinct strengths: systems integration, laboratory/industrial focus, energy conversion know‑how, and automotive system experience respectively. These companies are often the linchpin for OEM integrations or channel expansion.
Collectively, the market exhibits a moderate degree of concentration: the leading few players capture meaningful share, but the landscape still allows mid‑tier specialists to thrive in narrowly defined, technically demanding niches. This structure generates both the potential for strategic consolidation and the opportunity for focused players to command premium margins via differentiation.
Recent developments to watch (implications for 2026 planning)
- Product innovation: new miniature coolers with sub‑watt to double‑digit watt capacities enable optoelectronics and precision instrumentation to adopt active thermal control without significant size penalties. These product introductions accelerate adoption in space‑constrained applications.
- Partnerships that link modules to controllers are maturing, creating single‑source value propositions for OEMs seeking simplified procurement and validated thermal solutions.
- Qualification and standards: market leaders are securing industry qualifications (e.g., Telcordia‑grade testing), shortening customer qualification cycles — an important differentiator where time to revenue is mission‑critical.
- Capacity shifts: strategic plant investments in Asia indicate a two‑track play: secure near‑term cost advantage while maintaining technical centers in established engineering hubs.
Actionable recommendations for 2026
- Prioritize platform plays over one‑off products. Build modular TEM architectures that pair with configurable controllers to address multiple end‑use verticals with common SKUs and firmware variants.
- Lock supply and qualify dual sources for critical materials and subassemblies now. A 12–18 month qualification lead time means decisions in 2026 materially affect 2028 availability.
- Evaluate selective capacity investments only after stress‑testing utilization scenarios. Consider toll‑manufacturing or co‑located assembly partnerships to minimize capex while capturing time‑to‑market benefits.
- Use certification as a market entry weapon. Prioritize Telcordia, medical, and aerospace qualifications where they accelerate adoption and justify price premiums.
- Explore bolt‑on M&A or technology partnerships for micro TECs, controller IP, or thin‑film processing — these capabilities are projected to command outsized value as end‑use demands tighten.
- Implement a real‑time KPI dashboard tied to order intake, lead times, material costs, and qualification milestones to govern execution risk across 2026–2028.
How to use the full PW Consulting report
This briefing outlines the strategic contours and decision levers that matter in 2026. The full PW Consulting Thermoelectric Modules Market report contains the granular inputs and executable assets you will need to act: downloadable financial models, segmented demand tables, regional and application splits, detailed company profiles, M&A target lists, supplier scorecards, and playbooks tailored by end‑use. That level of granularity is intentionally withheld here to preserve the value of the source deliverable and to ensure readers engage the interactive tools and datasets that enable confident, executable decisions.
For executive teams preparing capital allocation, product roadmaps, or M&A playbooks this year, the combination of a validated CAGR, the 2025 market base, competitive maps, and our scenario analyses provides a practical foundation for prioritizing initiatives that will deliver differentiated returns through 2032.
To obtain the full dataset, editable models, and tailored executive summaries that translate this strategic insight into an operational plan, please access the PW Consulting Thermoelectric Modules Market report through our client portal or contact your PW Consulting engagement lead for a 2026 briefing and implementation workshop.
For detailed analysis of this topic, please visit the official page: Thermoelectric Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com