

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Airborne Surveillance Radar hits USD 1,000M in 2025; 4.5% CAGR forecast

Airborne Systems Surveillance Radar Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused strategic preview of our latest Airborne Systems Surveillance Radar Market study. This briefing is designed to demonstrate the analytical depth that underpins the full report and to highlight exactly how senior leaders should use that intelligence in 2026—while holding back the granular segment-level datasets that make the full research uniquely actionable. Think of this as a trailer: it reveals the arc and the stakes, but reserves the playbook for the full report.
Airborne Systems Surveillance Radar Market
Market snapshot: trajectory and structure
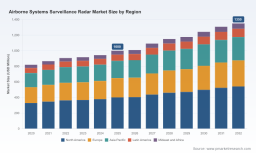
The airborne surveillance radar market is mature but evolving. On a macro basis, PW Consulting estimates the global market at approximately USD 1,000 Million in the base year 2025. After a period of steady growth from 2020, when the market was roughly USD 820 Million, our forecast shows a continued upward path through the 2026–2032 horizon, reaching about USD 1,350 Million by 2032. This corresponds to a compound annual growth rate (CAGR) of approximately 4.5% for the forecast window—sufficient to support selective expansion but also reflective of constraints such as spectrum regulation, export controls, and platform budget cycles.
Airborne Systems Surveillance Radar Market
Market concentration is a strategic reality. The top three vendors account for a clear majority of vendor revenue, and the top five together control nearly four-fifths of the market—conditions that favor incumbents with platform integration expertise, scale in systems-of-systems, and established defense procurement relationships.
Airborne Systems Surveillance Radar Market
Why this preview matters for 2026 corporate strategies
- Timing decisions: 2026 is a hinge year for multiple procurement cycles, technology refresh programs, and export-control updates. Firms that align product roadmaps and go-to-market investments now can secure prime positions in multi-year programs that commit budgets through 2032.
- Resource allocation: With moderate aggregate growth, the upside is selective—not all product lines will justify large-scale capital allocation. The full report identifies priority technology bets versus capabilities better suited to partnering or divestment.
- Risk calibration: Regulatory shifts and platform obsolescence form the dominant downside risks. The preview outlines key stress points; the complete analysis provides scenario-driven financial sensitivities for board-level risk appetite decisions.
What we cover — practical outputs in the full study
The full PW Consulting report is built as a decision-support toolkit for CEOs, business-unit heads, BD leads, and M&A teams. Highlights include:
- Proprietary TAM and forecast model: Annualized market sizing from 2020–2025 and forward-looking projections across 2026–2032, including baseline, upside, and downside scenarios driven by platform demand and regulatory vectors.
- Buyer demand mapping: Detailed procurement pipelines, budget phasing for fixed-wing, rotary, and unmanned platforms, and prioritization matrices for military versus civilian acquisition authorities.
- Technology roadmap and adoption curves: Comparative benchmarks for AESA, multi-mission modes, cognitive sensing, and sensor fusion, with time-to-deploy and integration complexity scoring for each capability.
- Commercial playbooks: Go-to-market options by platform segment (prime-led, subsystem supplier, integrator), partnership archetypes, and negotiated contract term guides for multi-year sustainment deals.
- M&A and JV target screening: A prioritized shortlist of capabilities and corporate profiles that would deliver accelerated access to spectrum-cleared technologies, software-defined radar IP, or embedded avionics integration capacity.
- Regulatory and export matrix: An operational guide to spectrum allocation, licensing timelines, and export-control constraints that materially affect product design, customer eligibility, and route-to-market.
- Supply chain resiliency analytics: Critical component shortfall scenarios, dual-sourcing strategies, and cost-to-requalify estimates for legacy radar lines.
- Scenario-driven financial models: Payback, NPV, and IRR outcomes for strategic initiatives—new product lines, market entry, and acquisition—under multiple assumptions.
Competitive landscape — positioning the leading vendors
The market structure favors vendors that combine radar-specific IP with platform integration and program delivery capability. Key firms covered in the study include:
- HENSOLDT (Germany): Known for multi-mission ISR radar families and Detect-and-Avoid systems for airborne platforms. Strength lies in European program ties and sensor miniaturization efforts.
- Thales Group (France): Offers the AirMaster family—multi-role airborne surveillance radars with a track record in contested environments and integration across defense OEMs.
- Honeywell (United States): Brings in-domain avionics and weather-surveillance pedigree via platforms such as its IntuVue series; advantage is avionics integration and civil certification pathways.
- Leonardo S.p.A. (Italy): Specializes in maritime and helicopter surveillance radars, leveraging platform-specific optimization and regional defense contracts.
- Israel Aerospace Industries (IAI): Active in multi-mode, multi-role airborne radars with recent program deliveries that demonstrate fielding velocity and export traction.
- Northrop Grumman (United States): Positions through high-end multi-platform programs and long-duration airborne ISR radars, targeting strategic airborne platforms.
- RTX Corporation, L3Harris Technologies, BAE Systems (United States/UK): These primes play to systems integration strengths, sustainment economies, and program management capabilities across large defense programs.
Competitive positioning in the report goes beyond logos and capabilities. We map each vendor across five vectors: technology differentiation, systems-integration reach, program delivery performance, export-sensitivity, and aftermarket/sustainment scale. The result is a tactical playbook for suppliers and customers: who to partner with, who to challenge, and where to seek asymmetric advantage.
Regulatory and operational dynamics that will shape decisions in 2026
Policy and infrastructure factors are central to near-term outcomes.
- Spectrum governance: Federal radar spectrum requirements remain the primary constraint for airborne radar operations across early warning, land, and maritime missions. Compliance is a precondition for platform acceptance and coalition operations.
- Export control tightening: The application of modern export-classification measures to advanced radar systems—most notably classifications such as an updated 6A008—raises development and go-to-market friction for firms seeking cross-border sales and collaborative development. Procurement strategies must bake in licensing timelines and contingencies.
- Platform modernization backlog: Specific infrastructure pressures—such as a quantified backlog of airborne systems exceeding intended lifespans—create both demand windows for replacement programs and supply-side constraints due to component availability and certification lags.
- Procurement interoperability: Military and government buyers increasingly condition purchases on demonstrated spectrum compatibility and adherence to national telecommunications authority guidance, making early-stage compliance an axis of competitive differentiation.
These dynamics are not abstract. For example, an OEM or subsystem supplier that can demonstrate pre-cleared spectrum profiles and export-path strategy will materially shorten procurement cycles and reduce bid risk. Conversely, firms that under-appreciate licensing timelines may see multi-million-dollar proposals deferred or disqualified.
Use cases — how executives should apply the research in 2026
- Portfolio prioritization: Use our scenario models to decide whether to accelerate R&D on AESA/multi-mode upgrades, expand sustainment services, or pursue bolt-on M&A. The report quantifies relative returns under conservative and aggressive market outcomes.
- Market entry and partnership design: For suppliers aiming to enter new geographies or platform segments, the study prescribes partner profiles and contract structures that minimize export and spectrum exposure while maximizing near-term revenue capture.
- Bid and proposal optimization: Integrate our procurement pipeline intelligence and buyer decision criteria to structure contract terms, delivery schedules, and sustainment offerings that align with buyer risk tolerances.
- Risk mitigation: Adopt the report’s supply-chain stress-tests and contingency costings to avoid single-supplier bottlenecks for critical radar components.
What this preview withholds — and why you need the full report
To preserve the utility of the full study as an action-oriented subscription product, this preview intentionally omits the granular breakdowns that drive low-risk, high-confidence decisions—specifically: detailed regional and application-level revenue splits, granular pricing and tender-by-tender analysis, and the sensitivity matrices for individual product lines. These datasets are the operational currency for program bids, JV negotiations, and M&A valuation; they remain available in the paid report.
Recent signal: industry momentum and delivery evidence
Market momentum is supported by program deliveries and tender awards. One near-term confirmation: in February 2025 Israel Aerospace Industries reported delivery of the first unit of a new multi-mode airborne surveillance radar to a strategic customer. Such deliveries validate technology readiness and shorten the sales ramp for subsequent units—an important datapoint in PW Consulting’s adoption curves.
Closing — actionable next steps for 2026
- Executive teams should commission a short internal audit against the report’s seven-point readiness checklist (technology, export-clearance, platform integration, supply-chain resilience, aftermarket capability, program-delivery history, and partnership map).
- Business development leads should align 2026 commercial plans to the procurement windows identified in the full report and prioritize engagements with partners who offer spectrum and export clearance experience.
- M&A and corporate development teams should request the full vendor benchmarking annex to surface targets that shift a company’s position on the five competitive vectors we use for valuations.
PW Consulting’s full Airborne Systems Surveillance Radar Market report contains the models, datasets, and playbooks to operationalize these recommendations. Request the full study to access the proprietary segment matrices, vendor scorecards, and scenario financials that Boards and executive teams need to make confident investments in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Airborne Systems Surveillance Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com