

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti-Reflective Glass Market Poised for 8.2% CAGR

Anti-Reflective Glass Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As global demand for higher-efficiency photovoltaic systems, low‑glare displays, premium architectural glazing, and advanced consumer electronics intensifies, anti‑reflective (AR) glass has moved from niche to strategic material status. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — quantifies a clear growth trajectory: the global AR glass market expanded from approximately USD 188.0 Million in 2020 to USD 257.0 Million in 2025, and is forecast to grow at a compound annual growth rate (CAGR) of 8.2% over 2026–2032, reaching roughly USD 442.0 Million by 2032. For executives making investment, procurement, or M&A decisions in 2026, the signals are unambiguous: the window for shaping differentiation and securing upstream/ downstream advantage is now.
Anti Reflective Glass Market
Why 2026 Is a Pivotal Inflection Point
-
Policy and procurement drivers are converging. National renewable energy targets and procurement rules increasingly require higher module-level efficiencies, which raises the commercial value of AR solar glass. Parallel demand in museums, premium architecture, and display sectors is driving requirements for near‑invisible transparency, UV protection, and scratch resistance.
Anti Reflective Glass Market -
Technology bifurcation is creating strategic choice points. Sol‑gel and multilayer dielectric coating approaches present different trade‑offs in cost, performance (transmittance and durability), and scalability. Recent product launches demonstrate rapid performance advances that can influence OEM sourcing decisions within quarters, not years.
Anti Reflective Glass Market -
Market structure enables both consolidation and rapid specialization. Market concentration metrics indicate a mid‑level concentration (CR3 ~54%; CR5 ~62%) — sufficient scale among leaders to set standards, but with room for niche or regional challengers to capture premium positions through technical differentiation or localized capacity.
What PW Consulting’s Report Delivers — Practical, Transaction‑Ready Intelligence
This study is designed as an operational toolkit for leaders who need to act in 2026. Highlights include:
-
Transparent market sizing and forecasting: historical reconciliation (2020–2025), base‑year calibration (2025), and scenario‑based forecasts (2026–2032) with sensitivity to raw material and policy shocks.
-
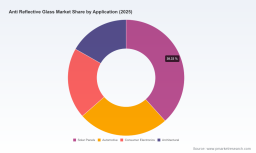
Demand driver matrix: quantified levers by end‑use (solar, automotive, consumer electronics, architecture) and how policy or technology shifts alter penetration curves (note: full segment tables and granular splits are available in the paid dataset).
-
Supplier benchmarking and scorecards: capabilities, capacity footprints, cost and yield proxies, quality certification status, recent product developments, and IP posture across incumbent and challenger suppliers.
-
Technology roadmap and cost models: unit economics for sol‑gel vs dielectric coatings, CAPEX/OPEX envelopes for coating lines, throughput and yield assumptions, and break‑even scenarios for vertical integration.
-
Regulatory and testing playbook: compliance checklists for photovoltaic module standards (e.g., IEC 61215), quality system requirements (ISO 9001), and ASTM testing guidance for architectural and museum applications.
-
Commercial strategies and negotiation frameworks: sample long‑form supply‑agreement terms, price escalation clauses linked to float glass feedstock indices, co‑development contracting templates, and recommended KPIs for off‑take and JV arrangements.
-
M&A and partnership pipeline: shortlist of strategic targets (technology specialists, regional coaters, niche product manufacturers), valuation benchmarks, and integration risk maps.
Competitive Landscape: Who Moves the Market — and How to Respond
The competitive field combines large integrated glass manufacturers with specialty coaters. Understanding each player’s strategic posture is essential for negotiating supply, forming co‑development partnerships, or identifying acquisition candidates. Key players covered in the report include:
-
Guardian Glass (Northville, Michigan, USA) — producer of low‑reflection coatings for architectural and display segments, with capability in double‑sided coatings that target minimal reflection. Strategic implication: strong partner for large architectural developers and façade integrators seeking guaranteed supply and durability testing documentation.
-
AGC Inc. (Tokyo, Japan) — offers Clearsight portfolio for museum and architectural applications and recently commercialized SOLITE‑AR for utility‑scale solar modules (Nov 2025), a sol‑gel solution with transmittance above 96% in selective markets. Strategic implication: AGC’s product roadmap demonstrates how rapid performance improvements can reset supplier qualification gates — suppliers and module manufacturers must reassess acceptance testing cycles.
-
Saint‑Gobain (Courbevoie, France) — supplies solar‑focused ALBARINO product lines, integrating solar glass capabilities with building glass portfolios. Strategic implication: strength in blended offers for BIPV (building‑integrated photovoltaics) and façade solutions.
-
Corning Incorporated (Corning, New York, USA) — strong in consumer electronics and specialty applications, where optical clarity and scratch resistance are critical. Strategic implication: essential partner for OEMs targeting premium display and AR performance in compact form factors.
-
Asahi Glass Co., Ltd. (Tokyo, Japan) — Planibel AR series for architecture and displays, leveraging broad global distribution and certification track record. Strategic implication: reliable route‑to‑market for architectural OEMs with legacy procurement processes.
-
PPG Industries, Inc. (Pittsburgh, Pennsylvania, USA) — offers two‑sided AR glass for solar and architectural applications, positioning around production scale and consistent quality. Strategic implication: capacity and service reliability matter where project timelines are unforgiving.
-
JNS Glass (United States) — specialty producer of single and multi‑layer dielectric coatings on a variety of substrates (glass, acrylic, polycarbonate). Strategic implication: an attractive co‑development partner for applications where substrate flexibility matters.
-
Mirit Glas (Netherlands) — custom AR and anti‑glare solutions for industrial and commercial end uses. Strategic implication: suited to complex, high‑margin niche projects (e.g., museum retrofits, custom displays).
Collectively, these incumbents and specialist players shape an ecosystem where scale, certification, and rapid product innovation drive procurement choices. The report’s supplier scorecards and recent‑development timelines enable buyers to align qualification cadence with product roadmaps.
Technology and Supply‑Chain Dynamics to Monitor in 2026
-
Feedstock sensitivity: the primary feedstock remains high‑purity float glass; coating processes (sol‑gel vs dielectric) add incremental materials and capital intensity. Our models show that yield improvements on coating lines produce outsized margin gains relative to raw material cost reductions.
-
Standards and certification: solar AR coatings must demonstrate compliance with photovoltaic module standards (e.g., IEC 61215) and ISO quality systems. Architectural and museum coatings often require ASTM‑level UV and abrasion resistance certifications — failure to present these can bar market access despite superior lab performance.
-
Regional policy drivers: national renewable programs and building codes materially affect procurement windows. Manufacturers and suppliers who pre‑emptively map certification timelines to these policy calendars secure procurement slots and reduce time‑to‑revenue.
Actionable Strategic Recommendations for 2026
-
For purchasers and OEMs: shorten supplier qualification cycles by running parallel technical evaluations — combine laboratory transmittance/durability testing with small‑batch field pilots to derisk adoption of novel AR chemistries.
-
For glass producers and coaters: prioritize yield optimization and certification investments. Small percentage improvements in process yield translate into meaningful cost advantages given the market’s projected growth trajectory.
-
For investors and corporate development teams: target bolt‑on acquisitions in specialty coating firms and regional coaters with proven certification histories. The mid‑concentration market means well‑executed M&A can rapidly move the competitive needle.
-
For technology strategists: pursue modular capacity expansion and co‑development partnerships rather than large single‑site greenfield bets. This preserves optionality as new chemistries (e.g., the sol‑gel innovators) shift performance baselines.
-
For risk managers: integrate regulatory compliance checkpoints into commercial contracts and include raw‑material price pass‑through mechanisms tied to recognized indices to protect margins.
How to Use This Brief — and Where the Full Intelligence Helps You Decide
This article is a strategic preview: it surfaces the structural dynamics, competitive positioning, and action‑oriented recommendations that PW Consulting’s full study develops in operational detail. The complete report and datasets include the granular market splits by region, type, and application, downloadable financial models, supplier scorecards, and scenario analytics that executives need to finalize 2026 budgets, capital plans, and M&A mandates. We intentionally withhold core granular segment tables in this executive preview — those are included in the full report package to ensure you have a defensible data foundation for negotiations and capital allocation.
To convert this strategic perspective into executable plans in 2026, firms should procure the full dataset, run the scenario model against internal cost assumptions, and schedule supplier and technology due‑diligence sessions within Q1. PW Consulting stands ready to support bespoke diligence, valuation work, or negotiated procurement strategies.
Closing
The anti‑reflective glass market presents a classic strategic intersection: accelerating end‑market demand, shifting technology frontiers, and a competitive structure that rewards both scale and specialized capabilities. With a projected CAGR of 8.2% across 2026–2032 and market expansion from a 2025 base of roughly USD 257.0 Million toward USD 442.0 Million by 2032, decisions taken in 2026 — on capacity, certification, partnerships, and M&A — will disproportionately determine market leadership and margin capture over the next business cycle. PW Consulting’s full report transforms these macro signals into deal‑ready, operational intelligence to support those decisions.
For detailed analysis of this topic, please visit the official page: Anti Reflective Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com