

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
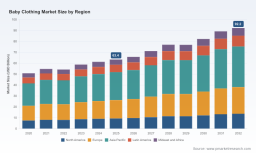
PW Consulting: Baby Clothing Market to Reach USD 92.2 Billion by 2032 at 5.5% CAGR

Baby Clothing Market 2026: Strategic Preview for Decision‑Makers
Executive snapshot
As companies plan their 2026 strategies, the baby clothing market presents a blend of stable growth, accelerating sustainability-led demand, and tightening regulatory guardrails that together reshape competitive advantage. Our PW Consulting base-year analysis (2025) shows a global industry that has grown steadily from the early 2020s and is projected to expand at a mid-single-digit compound annual growth rate (CAGR) through the next planning horizon. In plain terms: the market you compete in today is larger, more complex, and more regulative than it was five years ago, and the strategic choices you make in 2026 will determine whether you capture the higher-value segments that emerge over the next seven years.
Baby Clothing Market
Why this preview matters for 2026 decisions
Two practical realities make timely, data-driven strategic work essential this year. First, the market’s baseline size at the end of 2025 gives incumbents and new entrants scale to pursue premium, sustainable, and direct‑to‑consumer plays without sacrificing distribution. Second, regulatory and certification headwinds are increasing the effective cost of entry—and favor suppliers with proven compliance credentials and traceable supply chains. Leaders who align assortment design, sourcing and compliance investments with changing consumer expectations and regulatory requirements in 2026 will secure outsized returns as the market grows into the early 2030s.
Baby Clothing Market
Market trajectory: what the headline numbers tell you
-
The global baby clothing market expanded steadily over the first half of the decade and reached a substantial size in our 2025 base year, driven by normalization of retail demand and a renewed focus on premium and certified textiles.
Baby Clothing Market -
From our 2026–2032 forecast period, the market is projected to grow at a 5.5% CAGR, reaching a materially larger size by 2032. This trajectory creates capacity for new product tiers, regional expansion programs, and consolidation plays.
-
Concentration metrics indicate a moderately consolidated landscape: the top three players control a meaningful share, and the top five increase that share further—conditions that favor scale-based advantages in sourcing, compliance management, and brand distribution.
Dynamics reshaping demand and supply
Several concurrent forces are changing how baby clothing is designed, manufactured, and brought to market. For decision‑makers, these dynamics translate into discrete cost and revenue levers you can influence in 2026:
-
Regulatory tightening: New customs and certification requirements are being implemented that raise the compliance bar for apparel importers. In the U.S., for example, importers of children’s products must electronically file Children’s Product Certificates through specific customs channels beginning in mid‑2026. Parallel changes require age‑labeling verification and stricter documentation for garments intended for infants and toddlers.
-
Certification momentum: Certification bodies focused on organic and sustainable textiles have expanded capacity. Independent verification is now a core procurement requirement for many retail buyers rather than a premium add‑on, which reorders supplier selection criteria.
-
Health and safety as purchase drivers: Parents increasingly prioritize PFAS‑free, organic, and otherwise chemical‑safe textiles for infants. This preference is no longer niche—it's shaping assortment, labeling claims, and marketing strategies across premium and mass channels.
-
Channel bifurcation: Direct brands continue to gain traction with digital-native parents, while traditional retailers double down on curated, certification‑backed assortments. Managing channel margin divergence and inventory timing is a 2026 operational imperative.
What this means for sourcing, assortment and pricing
Operationally, the convergence of regulation and sustainability preference has five immediate implications for commercial teams planning 2026 rollouts:
-
Supplier selection must integrate compliance scorecards and certification maturity as core KPIs—beyond price and lead time. The cost of non‑compliance is now tangible at the border and in retail delists.
-
Assortment planners should layer “health-first” product propositions (PFAS‑free, certified organic, low chemical footprint) into both premium and accessible price bands—differentiation through verified claims will be a growth multiplier.
-
Low‑MOQ and private‑label manufacturing models are enabling new entrants and omnichannel brands to test assortments quickly; procurement teams must build flexible supplier arrangements to support fast turns.
-
Pricing strategies should reflect the full landed cost of certified supply chains (including documentation and testing), while capturing consumer willingness to pay for verified safety attributes.
-
Inventory and replenishment models require shorter cycles for trend and seasonal assortments, and longer tail visibility for staple certified basics to minimize working capital tied up in compliance‑sensitive SKUs.
Competitive landscape — who matters and why
The field includes a mix of specialized manufacturers, private‑label specialists, sustainable producers, and fashion houses that have extended into infant apparel. Key archetypes we track include private‑label Pima and organic specialists, European compliant manufacturers offering low minimums, and fashion brands operating capsule luxury collections.
-
The Pima Company (Jacksonville, FL, USA) — a private‑label specialist focused on 100% Peruvian Pima cotton knit apparel, known for baby layettes and sleepwear. Their product focus exemplifies differentiation by raw material provenance and textile story.
-
ExploreTex (Lisbon, Portugal) — a dual‑hub operator positioning on European compliance, low‑MOQ private label manufacturing, and near‑market lead times—the kind of supplier winning small brand and specialty retailer business.
-
Royal Apparel (Hauppauge, NY, USA) — U.S. production with an emphasis on organic cotton, bamboo and recycled fibers, servicing wholesale and private label channels; representative of reshored production and sustainability credentials.
-
Tack Apparel (Los Angeles, CA, USA) — custom manufacturer focused on softness, secure construction and regulation‑compliant garments; a player for brands demanding fast turn and North American sourcing pedigree.
-
Alanic (bulk supplier) and Billoomi Fashion (India) — illustrate the contrast between high‑volume, low‑cost suppliers and ethically‑oriented, craft‑specialist producers. Choices between these models determine margin and compliance risk profiles.
-
John Richmond (London, UK) — a fashion house extending capsule collections into baby and kids, signaling the premium fashion channel’s interest in early-life apparel as a brand halo opportunity.
Recent market events—from capsule launches at flagship stores to elevated trade shows in New York and Los Angeles—underscore that growth will be carved by both lifestyle brands and specialty manufacturers that can meet compliance, sustainability and speed demands simultaneously. Meanwhile, certification bodies report meaningful growth in verified facilities, reinforcing a structural shift toward certified supply chains.
What the PW Consulting report delivers (practical, implementable content)
Our full market study goes beyond headline numbers to provide the actionable intelligence commercial teams need in 2026. Highlights include:
-
Robust market sizing and scenario‑based forecasts calibrated to regulatory inflection points and certification adoption curves.
-
Go‑to‑market playbooks for premium, private‑label, and value segments—covering assortment architecture, pricing bands, and margin modeling.
-
Supplier risk matrices and a compliance readiness checklist to quantify border, testing and documentation exposures.
-
Case studies and sourcing templates that show how to structure low‑MOQ contracts, near‑shoring windows, and multi‑tier supplier portfolios.
-
Channel strategies for DTC, marketplace and wholesale, including promotional calendars and inventory cadence guidance.
-
Investment and M&A screening criteria for buyers targeting consolidation or capability acquisition in manufacturing, testing labs, or certified supply assets.
To preserve commercial value for subscribing clients, we intentionally withhold detailed line‑by‑line segment allocations in this preview. The full report contains the granular splits, region and application breakdowns, supplier scorecards and downloadable models needed to operationalize the recommendations above.
Immediate actions for leadership in 2026
Decision‑makers should treat the next 6–12 months as a window to harden competitive position. Recommended near‑term moves:
-
Run a compliance audit: map your current supplier base against the new customs and certification requirements and quantify potential border delays or testing costs.
-
Prioritize certified basics: accelerate certification or source certified cores that reduce customer churn and meet retailer delist thresholds.
-
Negotiate flexible MOQs: secure low‑MOQ pilots with compliant manufacturers to test “health-first” concepts with minimal inventory risk.
-
Revisit pricing architecture: update margin models to absorb certification and documentation costs while preserving promotional flexibility.
-
Set a one‑year roadmap for capability upgrades: invest in traceability (batch tracking, certificates, lab testing partners) and cross‑functional governance to lower disruption risk.
Closing — a practical invitation
The baby clothing market’s steady expansion and the regulatory/consumer shifts we describe make 2026 a pivotal planning year. PW Consulting’s full report provides the granular segmentation, supplier assessments, and scenario tools you need to convert this preview into an executable strategy. For teams preparing budgets, sourcing roadmaps, or M&A screens this year, our deep dive is structured to move projects from analysis to action quickly.
Contact PW Consulting to access the complete dataset, downloadable financial models, and supplier scorecards that translate these strategic signals into measurable operational plans.
For detailed analysis of this topic, please visit the official page: Baby Clothing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com