

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Amebocyte Lysate Market to Hit USD 4,065M by 2032 at 9.98% CAGR

Amebocyte Lysate Market 2026: Strategic Intelligence for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise but rigorous preview of our latest Amebocyte Lysate Market research — a playbook designed to inform executive decision-making in 2026. This document is written as a "trailer": it demonstrates the analytical depth and actionable thinking embedded in the full report while preserving the detailed segment-by-segment outputs that are available in the complete study.
Amebocyte Lysate Market
Executive snapshot: why this market matters in 2026
The Amebocyte Lysate market has moved from niche reagent status to a strategically important node in biologics, diagnostics and medical-device value chains. Our base-year analysis (2025) shows the industry expanded from USD 1,324 million in 2020 to USD 2,113 million in 2025, reflecting rapid adoption across drug testing and clinical diagnostics. Looking forward, our modeled forecast (2026–2032) projects continued expansion to approximately USD 4,065 million by 2032, underpinned by a 9.98% compound annual growth rate (CAGR) across the forecast horizon. Market concentration remains moderate, with the top three and top five players accounting for roughly 28.5% and 42.3% of the market respectively — a structure that supports both competition and opportunity for specialist entrants.
Amebocyte Lysate Market
What changed between 2020–2026 — the dynamics reshaping strategy
- Regulatory inflection points: The acceptance of recombinant, non-animal reagents has switched from future possibility to practical route-to-market. Key milestones — including USP Chapter <86> (formalized in 2025) and regulatory guidance updates that remove strict LAL (Limulus Amebocyte Lysate) references — have materially reduced regulatory friction for recombinant assays.
- Product innovation and de-risking: Incumbents and challengers are launching animal-free assay platforms, cartridge-based workflows and integrated consumable solutions. These moves materially reduce dependence on traditional raw-material supply lines and ease customers’ validation burdens.
- Sustainability and supply-chain imperatives: Large biopharma process teams and service providers are actively reducing horseshoe-crab derived inputs. Several public and private initiatives — including cartridge and recombinant platforms that use substantially less or no animal-derived material — are now validated through real-world bridging studies, accelerating procurement shifts.
- Service-model consolidation: Contract testing providers are offering bundled offerings (rapid cartridges, recombinant reagents and advisory services) which compress time-to-result and shift customer preference toward turnkey solutions.
Competitive landscape — what the major players are doing (select snapshots)
Our competitive analysis emphasizes capability vectors rather than raw market share alone. The landscape is populated by diversified global suppliers, specialist reagent houses and contract testing laboratories; together they form an ecosystem in which technology leadership, regulatory traction and supply resilience matter more than size alone.
Amebocyte Lysate Market
- FUJIFILM Wako Pure Chemical Corporation (Osaka, Japan) — offers a suite of endotoxin-specific reagents and endotoxin-free consumables across gel-clot and kinetic formats. Their product focus is reliability across traditional LAL workflows.
- Associates of Cape Cod, Inc. (East Falmouth, USA) — has positioned itself with an animal-free recombinant cascade reagent (PyroSmart NextGen®) and continues to support classic LAL formats; it represents a classic fast-follower/innovator hybrid.
- Lonza Group AG (Basel, Switzerland) — combines a broad LAL portfolio with recombinant Factor C platforms, offering manufacturers an integrated supply option aligned to regulatory change.
- Charles River Laboratories (Wilmington, USA) — is integrating rapid cartridge-based testing with recombinant reagents and has publicly emphasized dramatic raw-material reductions via cartridge technology, making them a go-to for rapid, lower-footprint testing.
- Xiamen Bioendo Technology (Xiamen, China) and GenScript Biotech (Nanjing, China) — represent regionally strong reagent suppliers offering both traditional TAL/LAL reagents and chromogenic assay kits; they are important players in pricing and availability dynamics.
- Nelson Laboratories (Salt Lake City, USA) — is a prominent contract testing partner, executing bacterial endotoxin testing and microbial validation across complex customer portfolios.
Recent milestones shaping commercial strategy
- Product introductions: New animal-free solutions and cartridge integrations have moved from R&D labs into commercially available products, reducing customers’ validation overhead and accelerating adoption.
- Standards and guidance: USP’s 2025 chapter and subsequent regulatory guidance adjustments through early 2026 have reduced compliance barriers for recombinant reagents, shifting the balance of clinical and QA procurement discussions.
- Supply resilience: High-profile bridging studies and public commitments by large biopharma firms to reduce animal-derived LAL usage have de-risked the business case for recombinant platforms.
Strategic implications — five actionable considerations for 2026
- Resource allocation: invest in recombinant and cartridge-compatible platforms — Given regulatory tailwinds and customer demand for lower-footprint assays, capital allocation to recombinant Factor C and cartridge-compatible production lines is now a risk-mitigated investment. Firms choosing to delay will face longer and costlier validation cycles when customers mandate non-animal options.
- Commercial model: move from product-only to solution-centric offers — Buyers increasingly prefer solutions that combine reagents, cartridges and testing-as-a-service. Pricing and sales structures should reflect recurring revenue potential from consumables and service contracts.
- Supply-chain redesign: prioritize dual-sourcing and vertical integration where strategic — The historical dependence on biological raw materials introduces volatility. Targeted vertical integration (e.g., recombinant enzyme production) or secured long-term supply agreements will materially lower operational risk.
- Regulatory intelligence: maintain an active, proactive engagement strategy — Regulators are accepting new modalities; companies that lead with standardized validation packages and pre-submission dialogues will shorten approval cycles and capture first-mover advantages.
- M&A and partnership scouting: screen for capability gaps — Look for bolt-on assets that accelerate recombinant capabilities, cartridge manufacturing, or rapid-testing service capacity. The moderate market concentration means well-timed M&A can shift positioning materially.
How PW Consulting’s report supports 2026 decisions
Our full study is designed for immediate operationalization by executive teams and strategy units. Key operational deliverables include:
- Proprietary demand model (2020–2032) calibrated to primary interviews and validated against company disclosures, enabling scenario stress-testing at product, regional and application levels.
- Regulatory mapping and an approvals tracker that aligns product types to current and anticipated standards, with recommended regulatory playbooks for substitution strategies.
- Competitive capability matrices that rank players on technology readiness, scale, regulatory access and supply resilience — optimized for partner or acquisition screening.
- Commercial scenarios and pricing models that quantify total cost of ownership for cartridge vs. traditional workflows across typical customer segments.
- Implementation blueprints — short-term (0–12 months), medium-term (12–36 months) and long-term (36+ months) — with resource, CapEx and validation roadmaps tied to specific adoption pathways.
Decision frameworks we recommend using in 2026
To translate market intelligence into action, we recommend companies apply three lenses:
- Value-to-cost swap analysis: Quantify the net switching cost for customers (validation + procurement + operational) versus the lifetime value of recurring consumables and preferred-supplier status.
- Regulatory-probability overlay: Combine regulatory acceptance probabilities with technology readiness to prioritize product launches and market entry sequencing.
- Supply-resilience index: Score suppliers and internal options against raw-material dependency, scalability and geographic risk to allocate hedging capital appropriately.
Where this preview stops — and why the full report matters
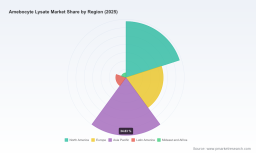
This preview supplies the topline growth trajectory and the strategic logic you need to align leadership priorities in 2026. What it does not contain — intentionally — is the granular regional and application-level splits, detailed price curves, and the full list of modeled competitor scenarios and annex data. Those elements are the working currency for transactions, procurement negotiations and M&A diligence; they are included in the full PW Consulting report and interactive model.
Practical next steps for executives
- Request the full report and the interactive demand model to run your in-house scenarios (replicate our valuation assumptions, swap in your pricing, or stress-test supply disruptions).
- Use our competitor capability matrix as a short-listing tool for potential partnerships or acquisitions — prioritize firms with recombinant capabilities and cartridge manufacturing.
- Begin a three-month pilot with a recombinant or cartridge partner to validate performance, cost and regulatory fit within your internal QA envelope.
Closing perspective
Between 2020 and the 2025 base year, the Amebocyte Lysate market consolidated into a strategically relevant supply chain for biologics and devices. As regulatory frameworks and customer preferences swing toward animal-free, lower-footprint solutions, 2026 becomes the watershed year for executing technology transitions and commercial repositioning. Companies that combine targeted investment in recombinant and cartridge technologies with disciplined regulatory engagement and a solutions-oriented go-to-market will capture disproportionate growth as the market progresses toward the USD 4,065 million horizon in 2032.
For access to the complete dataset, regional/application breakdowns, full competitive profiles and PW Consulting’s interactive scenario engine, please consult the full Amebocyte Lysate Market report on our website or contact our advisory team. The nuanced, model-backed insights there are designed to translate directly into boardroom decisions in 2026.
For detailed analysis of this topic, please visit the official page: Amebocyte Lysate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com