

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Healthcare Workforce Management Market to Reach USD 413.65M by 2032 at 10.6% CAGR

Healthcare Workforce Management Systems: Strategic Imperatives for 2026 — A PW Consulting Brief
Executive snapshot
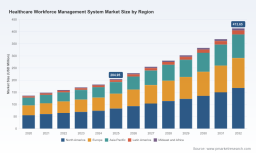
Healthcare workforce management systems have moved from niche operational tools to strategic platforms that materially affect care quality, labor costs, and regulatory compliance. PW Consulting’s latest market study — anchored on 2025 as the base year and projecting through 2032 — shows a market that expanded from approximately USD 136.3 million in 2020 to about USD 205.0 million in 2025 and is forecast to reach roughly USD 413.7 million by 2032, growing at a compounded annual growth rate (CAGR) of 10.6% over the forecast period. For executive teams planning investments, partnerships, or M&A in 2026, the implications are clear: workforce systems are a growth vector and a strategic control point for both clinical and operational outcomes.
Healthcare Workforce Management System Market
Why this market matters in 2026
-
Operational leverage: Workforce systems are central to managing rising labor spend and shift-based staffing complexity. Beyond timekeeping and scheduling, modern platforms embed predictive staffing, compliance workflows, and payroll orchestration that directly affect margins and service capacity.
Healthcare Workforce Management System Market -
Regulatory and privacy posture: Proposed and evolving rulemaking (notably updates to privacy and security guidance for healthcare workforce systems) elevates compliance from an HR function to a board-level risk. Solutions that can demonstrate robust audit trails, fine-grained access controls, and rapid breach response capabilities will command premium credibility.
Healthcare Workforce Management System Market -
Clinical quality & staffing resilience: Workforce platforms increasingly influence patient outcomes by optimizing nurse-to-patient ratios, minimizing burnout through predictive scheduling, and ensuring skill-aligned staffing in high-acuity settings.
-
Strategic integration: The most valuable deployments are those that interoperate seamlessly with EHRs, payroll, and enterprise HCM stacks — converting workforce data into actionable operational intelligence.
Market trajectory and what the numbers say
The market’s historical expansion and projected doubling to the low hundreds of millions (in USD, denominated in millions) over the 2026–2032 forecast period reflect structural demand rather than a short-term cycle. A sustained CAGR of 10.6% signals durable adoption across provider settings, driven by digitization, regulatory complexity, and workforce shortages that force health systems to invest in optimization technology. For executives, this trajectory implies that decisions made in 2026 — about platform selection, customization, and integration strategy — will determine cost and quality outcomes for the coming decade.
Report coverage — what PW Consulting delivers
Our full report translates the market trajectory into operational playbooks for three types of readers: health system executives, vendor strategists, and private investors. Key practical deliverables include:
-
A buy-versus-build decision framework that quantifies TCO drivers (implementation, change management, integration, and ongoing maintenance) and maps them to five typical provider archetypes.
-
Vendor selection matrices that weigh critical capabilities — clinical shift scheduling, predictive analytics, compliance automation, EHR integration, and payroll fidelity — against deployment risk and time-to-value.
-
Implementation playbooks that cover stakeholder alignment, data governance, phased rollouts, and KPIs to measure clinical and financial returns within 12–24 months.
-
Commercial insights on pricing strategies, channel models, and partnership structures tailored to vendors and system integrators pursuing healthcare accounts.
-
Risk scenarios and regulatory readiness checklists tied to recent policy shifts affecting workforce data privacy and security.
Note: the full report contains detailed regional and application splits, vendor scorecards, and financial benchmarks reserved for subscribers and clients.
Competitive landscape — positioning and strategic moves
The competitive field combines large enterprise HCM vendors, specialized healthcare workforce providers, legacy healthcare IT firms, and emerging AI-enabled niche players. Market concentration remains modest; incumbents enjoy recognizable footprints but no single vendor controls the majority of market value, leaving room for consolidation, vertical specialization, and innovation-led share shifts.
-
UKG Inc. — Strengths: deep healthcare-focused modules for clinical staffing, predictive scheduling, and payroll integration. Strategic posture: expanding healthcare-centric feature sets and partnerships to deepen clinical adoption and long-term account retention.
-
Oracle Corporation — Strengths: large-scale HCM and analytics capabilities suited to complex hospital systems. Strategic posture: leveraging cloud scale and enterprise integrations to win large, centralized health systems and multi-hospital groups.
-
Workday, Inc. — Strengths: robust workforce planning and shift management for complex, shift-based organizations. Strategic posture: positioning workforce modules within an integrated HCM narrative to capture mid-to-large enterprise transformations.
-
SAP SE — Strengths: enterprise-grade workforce and compliance tools with strong analytics. Strategic posture: winning accounts that prioritize SAP-centric enterprise stacks and global compliance coverage.
-
ADP, Infor, ATOSS, Ceridian Dayforce, McKesson, symplr, Nextech, Allscripts — Each of these firms occupies differentiated niches: payroll and compliance specialists, healthcare IT integrators, and AI-driven scheduling vendors. Strategic moves include product enhancements, healthcare-specific integrations, and partner-led go-to-market plays.
Recent developments to watch (directional)
-
Major multi-year public-sector contracts for next-generation workforce platforms underscore governments’ intent to modernize payroll and staffing infrastructure. These programs are creating referenceable implementations and raising the bar for security, scalability, and interoperability.
-
Vendors continue to invest in healthcare-specific enhancements — from sophisticated scheduling rules for clinical certification and nurse-to-patient mapping to embedded compliance workflows intended to simplify audit readiness.
-
Third-party recognition of AI-driven scheduling tools is accelerating commercial adoption, particularly for acute-care nurse staffing where schedule optimization has immediate operational impact.
Strategic implications for 2026 decision-makers
-
For health systems: Treat workforce systems as strategic infrastructure. Prioritize solutions that demonstrate measurable clinical staffing improvements, integrate with the EHR and payroll, and provide robust compliance/audit capabilities. Pilot projects should be tightly scoped with clear success metrics tied to labor cost savings, overtime reduction, staff satisfaction, and patient throughput.
-
For technology vendors: Differentiate through outcome-based services — guarantee measurable improvements (e.g., reduced agency spend, improved staff retention) rather than selling modules alone. Invest in interoperability adapters and pre-configured clinical scheduling templates to reduce implementation friction.
-
For private equity and strategic investors: The market’s mid-single-digit concentration and projected CAGR create an attractive runway for roll-up strategies, especially combining best-of-breed scheduling/AI capabilities with broader HCM footprints. Due diligence should emphasize client retention, integration debt, and compliance posture.
-
For integrators and service providers: There is a growing opportunity for implementation and managed-service offerings that absorb change management risk. Bundled services (platform + managed scheduling operations) win in constrained labor markets.
Risks, barriers, and mitigations
-
Regulatory volatility: Upcoming privacy/security rule changes increase compliance costs. Mitigation: adopt modular architectures that enable rapid policy-driven controls and logging.
-
Integration complexity: Legacy EHRs and payroll systems create brittle integrations. Mitigation: prioritize vendors with pre-built connectors and hybrid deployment models to reduce cutover risk.
-
Workforce adoption: Poorly executed rollouts risk low clinician uptake. Mitigation: co-design scheduling rules with clinical leaders and invest in training, governance, and continuous feedback loops.
How PW Consulting can help
Our advisory services translate the market study into executable roadmaps: vendor selection support, commercial negotiation playbooks, implementation governance, and post-deployment performance measurement. For executive teams evaluating strategic options in 2026, we provide scenario-based financial models that convert workforce system choices into EBITDA, quality, and capacity impacts.
Next steps
This brief highlights the strategic contours of the Healthcare Workforce Management System market as you plan for 2026. The full PW Consulting report contains: granular regional and application splits, vendor scorecards, detailed TCO models, case studies, and executable playbooks — information we intentionally reserve to preserve actionable differentiation for our clients. To access the complete dataset, methodologies, and customizable tools, please visit our report landing page or contact PW Consulting’s Healthcare Practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Healthcare Workforce Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com