

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vacuum Blood Collection Tube Market to Hit USD 4,285M by 2032 (4.25% CAGR)

Vacuum Blood Collection Tube Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused introduction to our latest market research on the Vacuum Blood Collection Tube market. This briefing distills the report’s strategic value for leadership teams making pivotal choices in 2026 — from product roadmaps and regulatory investment to M&A, procurement, and lab engagement. The full study (base year 2025; historical 2020–2025; forecast 2026–2032) combines rigorous market-sizing with scenario analyses and supplier-level intelligence. Below we reveal the high-level signals you need to justify near-term allocation decisions while intentionally omitting core granular tables and segment-level figures to preserve the invitation to access the full report.
Vacuum Blood Collection Tube Market
Macro Picture: Growth, Scale and Concentration
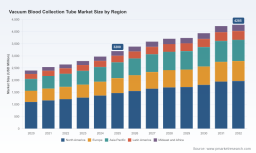
The vacuum blood collection tube market has shown steady expansion through the first half of the decade. Our bottom‑up synthesis estimates the global market increasing from a multi‑billion basis in 2020 to a significantly larger footprint by the base year 2025, reflecting a compound annual growth rate (CAGR) of approximately 4.25% across the historical-plus-forecast window. Forward projections to 2032 indicate continued growth driven by rising diagnostic volumes, broader adoption of integrated sample-management systems, and incremental product innovation (e.g., advanced separators, miniaturized capillary systems).
Vacuum Blood Collection Tube Market
Market concentration is meaningful: the three leading global suppliers control a clear majority share, and the top five raise that dominance to a three‑quarters level of market control. For incumbents and challengers alike, this structure defines both the competitive barriers and the levers for disruption — scale economics, distribution breadth, clinical validation capabilities, and regulatory credentials.
Vacuum Blood Collection Tube Market
What the PW Consulting Report Delivers — Practical, Actionable Content
-
Quantified market sizing and growth scenarios: conservative, baseline and upside paths through 2032, with demand drivers and risk factors explicitly modeled.
-
Supply-side mapping and capacity diagnostics: sterile manufacturing footprint, sterilization bottlenecks (gamma, EO), and supplier lead‑time stress tests under demand surges.
-
Regulatory and standards playbook: step‑by‑step guidance for US 510(k) pathways, EU IVDR conformity approaches for sterile devices, and sterilization validation requirements per recognized standards.
-
Clinical compatibility and adoption framework: laboratory validation protocols (aligned to CLSI guidance), assay-compatibility risk matrices, and go‑to‑laboratory engagement templates.
-
Competitive intelligence dossiers: benchmarking of leading manufacturers, their product portfolios, routes to market (brand vs. OEM), and a curated list of recent approvals and product launches.
-
Commercial playbooks for procurement and pricing teams: tender templates, negotiation levers, and short‑term supply continuity plans including multi-sourcing and regional buffer strategies.
-
M&A and partnership roadmaps: prioritized target archetypes and valuation heuristics for platform-buyers and strategic acquirers seeking to consolidate mid-market share.
-
Operational stress tests and sensitivity analyses: cost‑curve scenarios for raw materials, sterilization throughput, and freight disruption to quantify margin implications under various shocks.
We intentionally withhold the granular segment tables and regional breakdowns from this preview to ensure you consult the full report for the detailed, transaction-grade data essential for investment memoranda or procurement bids.
Competitive Landscape — Who Matters and Why
The market is anchored by a handful of global players with full vertically integrated capabilities — brand equity in blood collection systems, broad regulatory coverage, and deep clinical relationships. Key companies profiled in the report include established global manufacturers and rising regional suppliers:
-
Becton, Dickinson and Company (BD): A market leader with flagship vacuum blood collection brands and a steady cadence of regulatory clearances. Recent 510(k) approvals (including plasma separator and heparin tube clearances in 2025 and a miniaturized capillary system clearance in 2026) reinforce BD’s clinical product pipeline and support expansion into point‑of‑care and capillary-sampling workflows.
-
Greiner Bio‑One: Known for its VACUETTE® product family and strong European clinical penetration; competitive strengths include integrated system design and laboratory training programs.
-
Terumo Corporation: A major regional OEM with durable ties to Asia‑Pacific markets and a growing presence in specimen collection systems, leveraging upstream manufacturing scale.
-
Sarstedt AG & Co.: European specialist with a reputation for quality tubing and ancillary disposables; positions strongly among hospital procurement groups that prioritize compatibility and service.
-
FL Medical and a cohort of China and India‑based manufacturers (e.g., KS Medical, KDL, BIOBASE, Narang Medical, Sunphoria, CML Biotech, Labtech Disposables): These suppliers form the competitive long tail — cost‑competitive, increasingly quality‑compliant, and prime candidates for OEM partnerships or bolt‑on acquisitions by global players seeking cost optimization or regional penetration.
Our competitive mapping highlights three strategic pathways observed among market participants: (1) premium branded differentiation via clinical evidence and lab‑support services; (2) OEM/contract supply to large diagnostics and hospital groups; and (3) price/volume disruption from regional manufacturers expanding international certifications. The CR3 and CR5 concentration metrics underscore that mid‑market consolidation and targeted alliances remain high‑impact strategic moves.
Regulatory, Standards and Clinical Dynamics — The Non‑Negotiables
-
US Regulation: Vacuum blood collection tubes are generally classified under Class II devices and typically require premarket 510(k) notification for US market entry. Recent 510(k) clearances for plasma separator and capillary systems illustrate both opportunity and the need for disciplined regulatory resourcing.
-
EU IVDR: While sterile Class A devices may follow self‑declaration pathways, manufacturers must address EUDAMED registration and updated conformity expectations; strategy should differentiate between local distribution via CE marking and future IVDR oversight changes.
-
Sterilization Standards: Validation protocols per ANSI/AAMI/ISO 11137 series for gamma/EO sterilization are industry norms. Sterilization capacity constraints have material implications for scaling new product launches.
-
Laboratory Standards: CLSI GP41 guidance obliges laboratories to validate any supplier change for assay compatibility — a practical barrier to rapid supplier switching and an important opportunity for suppliers that offer lab validation support packages.
-
Reimbursement and Coding: In mature markets, CPT/Medicare coding conventions influence purchasing economics; understanding the reimbursement mapping by tube type and additive is essential when pricing or evaluating market access investments.
Strategic Implications for 2026 — Decisions That Matter
For executive teams planning allocations in 2026, our report clarifies high‑return investment areas and defensive plays. Key recommendations:
-
Prioritize regulatory and clinical evidence investments. Fast‑track 510(k) and IVDR readiness for products that target higher-margin use cases (e.g., separator tubes, capillary systems). Complement approvals with lab validation toolkits to reduce customer switching friction.
-
Dual‑source critical inputs and de‑risk sterilization. Given sterilization validation demands and potential capacity tightness, secure contractual sterilization capacity or verticalize for strategic SKUs to preserve launch timelines.
-
Adopt a tiered go‑to‑market model. Combine premium branded channels for hospital systems and reference labs with OEM partnerships for volume channels; offer bundled clinical services to tilt procurement decisions toward value over lowest price.
-
Use M&A to bridge capability gaps. Targets that add regional manufacturing, sterilization assets, or laboratory services capability materially accelerate time‑to‑market and margin improvement compared with greenfield investment.
-
Design pricing strategies cognizant of reimbursement realities. Where CPT or insurer reimbursement creates price ceilings, shift to service‑based differentiation or contract‑value propositions (e.g., guaranteed assay performance, training, warranty).
-
Prepare scenario plans for supply shocks. Our sensitivity analyses quantify margin impacts across input-cost and freight disruption events; senior teams should maintain contingency playbooks that include buffer inventories and prioritized allocation rules.
Closing — How to Use This Preview
This introduction surfaces the macro trends, regulatory imperatives, and competitive archetypes that will determine winners and losers through 2026 and beyond. It is designed to help strategy, commercial and operations leaders quickly align investment hypotheses. For transaction-grade segmentation, regional demand curves, supplier scorecards, and the full set of modeled scenarios that support capital allocation or procurement negotiations, please consult the full PW Consulting Vacuum Blood Collection Tube Market report. That report contains the complete data tables, forensic supplier audits, and downloadable templates needed to execute the strategies outlined here.
PW Consulting stands ready to translate these insights into a tailored workshop, a diligence package for M&A, or an operational resilience plan aligned to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Vacuum Blood Collection Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com