

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Debt Collection Software Market to Hit USD 344.8M by 2032, Growing at 6.24% CAGR

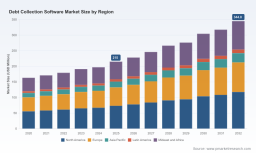
Debt Collection Software Market — Strategic Briefing for 2026 Decision-Makers
Executive preview
As organizations rewire receivables operations for tighter liquidity cycles, the debt collection software market has matured from point solutions into an orchestration layer that combines AI, omnichannel engagement, compliance automation and outcome-based commercial models. This briefing — drawn from PW Consulting’s full market study (base year 2025) — synthesizes the macro trajectory, regulatory inflection points, vendor dynamics and an actionable decision playbook tailored for enterprise and mid-market leaders making procurement and transformation decisions in 2026.
Debt Collection Software Market
Market snapshot (what the headline numbers tell you)
Over the 2020–2025 historical period this market recorded steady expansion and entered 2026 from a position of broad-based growth. Using 2025 as the base year, PW Consulting forecasts the sector through 2032 within a scenario set that assumes continued digitization of accounts-receivable functions and tighter regulation of automated decision-making. The market is projected to expand at a compound annual growth rate (CAGR) of 6.24% over the forecast window, reflecting persistent demand for automation, analytics and customer-engagement capabilities that reduce days sales outstanding (DSO) and improve recovery economics. Market concentration remains low; the combined revenue share of the three largest suppliers is in the mid-twenties percentage range, underscoring an intentionally fragmented competitive environment with many specialized entrants and niche leaders.
Debt Collection Software Market
Why this study matters for 2026 decisions
- Regulatory risk is now a procurement criterion — New and updated regimes (notably the EU’s AI Act, state-level U.S. laws affecting AI explainability and consumer protection amendments) force procurement teams to treat explainability, bias testing and auditability as table-stakes functionality rather than optional extras.
- AI drives capability but increases governance exposure — Agentic and predictive AI have accelerated collections automation, but they also create requirements for logging, model documentation and dispute-support capabilities.
- Commercial models are evolving — Vendors are experimenting with outcome-based pricing and implementation incentives that shift adoption risk away from buyers; procurement teams must adapt evaluation criteria beyond license costs to include measured business outcomes.
- Fragmentation creates both opportunity and integration risk — Lower concentration means specialist innovation and targeted fit-for-purpose solutions, but it also raises integration and TCO complexity for enterprises.
What the full report delivers (practical, actionable products)
PW Consulting’s full report translates market intelligence into tools you can operationalize immediately. Key deliverables include:
Debt Collection Software Market
- Validated market sizing and forecast models (historical 2020–2025 and forward to 2032) with scenario sensitivity and upside/downside cases.
- Procurement scorecards and vendor shortlists calibrated by buyer archetype (enterprise, mid-market, collection agency, lender) and use-case (early-stage outreach, dispute handling, litigation escalation).
- Outcome-based procurement templates and sample contract clauses for revenue-share/implementation-incentive arrangements.
- Implementation blueprints that detail technical integration patterns (ERP/APIs/payment rails), data mapping templates and phased rollout timelines.
- Compliance checklists aligned to the EU AI Act, U.S. state AI laws, California debt collection updates and GDPR-era recordkeeping requirements — including required explainability logs, consent tracking and audit trails.
- ROI and TCO calculators, sensitivity analyses for DSO improvement, cost-to-collect reduction, and program staffing offsets.
- Case studies and playbooks for pilots and scale-up, including KPIs, success criteria and governance roles.
To preserve the strategic advantage for our subscribers, the report intentionally withholds granular regional and application-level splits in this public briefing. The full dataset — including granular segmentation, vendor-level revenue estimates and pricing benchmarks — is available on our source page for authorized readers.
Competitive landscape: profiles and strategic implications
The market is populated by a mixture of digitally native specialists, legacy platforms adapting to modern workflows and software suites extending into AR/collections. Several vendor archetypes and representative players illustrate where the competition is converging and where differentiation persists:
- AI-first AR specialists (examples) — Firms offering agentic AI and workflow prioritization standout for automation-driven efficiency. These vendors are well-suited for organizations seeking to reduce DSO and automate routine collector activities while preserving compliance controls. Recent moves from market leaders show an increasing shift to outcome-based commercial models that share implementation risk with buyers.
- AR automation suites with buyer-facing features (examples) — Providers that combine invoice-to-cash automation and buyer self-service are lowering friction in collections and improving early liquidity visibility. These platforms are attractive where customer experience and early-stage payment recovery are priorities.
- Behavioral-science and engagement specialists (examples) — Vendors that embed behavioral science into chatbots and virtual assistants drive better engagement rates and higher self-service recovery. These tools work best as part of a layered engagement strategy across channels.
- Agency- and debt-buyer-focused platforms (examples) — Solutions tuned to agency workflows and portfolio recoveries prioritize high-volume, compliance-forward automation and predictive analytics for allocation and segmentation decisions.
- Regional and compliance-focused vendors (examples) — Localized platforms continue to matter where jurisdictional rules and language support dominate. These vendors provide deep compliance templates and region-specific audit capabilities.
Notable supplier-level dynamics observed in 2026:
- Some vendors are offering outcome-based pricing and reduced upfront fees to accelerate adoption and align commercial incentives with measurable collections outcomes.
- Platform-level differentiation increasingly centers on explainability, audit logs and consent tracking to satisfy regulators and prove defensibility in dispute scenarios.
- Integration-ready vendors that provide pre-built connections to major ERPs and payment rails reduce implementation friction and can materially shorten time-to-value.
Regulatory and operational noise that will shape your roadmap
The regulatory backdrop is creating new operational requirements that should be embedded into vendor selection and program governance:
- Recent and upcoming laws and regulatory updates require explainability documentation for automated scoring, bias testing, and machine-readable audit trails for any automated decisioning applied in debt collection.
- State-level rules in major jurisdictions require detailed disclosure and operational changes, including new reporting and oversight obligations for AI-driven tools used in collection activities.
- Privacy and consumer protection standards demand GDPR-compliant consent tracking, automated communication logs for disputes, and data minimization controls.
Strategic recommendations for 2026 (priorities and risk controls)
- Immediate (30–90 days) : Conduct a compliance-oriented vendor short-listing that treats explainability, auditability and model governance as mandatory evaluation categories. Run a data readiness and consent audit to identify remediation actions required before any AI-dependent pilot.
- Near-term (3–6 months) : Pilot two complementary approaches — one focused on early-stage engagement and buyer self-service, another on prioritized automation for high-cost accounts. Use measurable success criteria (reduction in DSO, contact-to-pay conversion, cost-to-collect) and require vendors to instrument explainability logs as part of the pilot.
- Commercial strategy : Negotiate outcome-based elements or risk-sharing clauses where vendor performance is measurable. Insist on implementation milestones tied to business outcomes and include model change notification clauses for AI components.
- Governance and risk management : Establish an AI oversight function that owns model validation, bias testing, and audit log retention. Define responsibilities for dispute escalation and maintain a documented chain of custody for decisions generated by automation.
- Resourcing : Invest in a small cross-functional center of excellence (AR operations, legal/compliance, data science, and IT) to manage vendor relationships, measurement, and continuous improvement.
Decision playbook — six tactical steps
- Define the prioritized use cases and the single most important KPI for each (e.g., DSO reduction, recovery rate for >90 day buckets, dispute throughput).
- Create a short-list that maps vendor archetypes to those use cases and require mandatory compliance proof points during RFPs.
- Run time-boxed proofs-of-value with representative portfolios and agreed measurement windows; require explainability and audit artifacts as deliverables.
- Evaluate total cost of ownership including integration, change management and ongoing governance costs — not just license fees.
- Negotiate outcome-linked terms and data ownership/portability clauses to avoid vendor lock-in.
- Phase rollout with continuous KPI gates, tying scale-up to validated performance and regulatory readiness.
Closing — what to do next
The 2026 agenda for debt collection modernization is clear: accelerate automation where it demonstrably reduces cost-to-collect and DSO, but treat AI governance and regulatory compliance as intrinsic selection criteria. PW Consulting’s full market study provides the granular segmentation, vendor scorecards, pricing benchmarks and contract templates necessary to execute quickly and defensibly. This briefing intentionally omits the detailed regional and application splits that inform procurement-level decisions; subscribers and authorized readers can access those datasets and the full set of playbooks on our source page.
For teams preparing a Q2 or Q3 vendor selection, prioritize pilots that deliver early liquidity and instrument explainability from day one. If you would like a tailored vendor short-list or a facilitated procurement sprint aligned to your KPIs, PW Consulting’s industry practice is available to accelerate your through-market execution.
For detailed analysis of this topic, please visit the official page: Debt Collection Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com