

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Caffeine Market to Reach USD 2,743.2M by 2032 at 6.95% CAGR

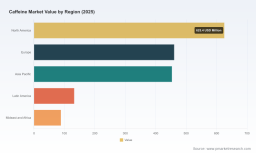
Caffeine Market 2026: Strategic Imperatives for Decision‑Makers
Executive snapshot
As companies prepare strategic plans for 2026, the caffeine market presents both an accelerating opportunity and a complex risk landscape. Our latest PW Consulting study—anchored on 2025 as the base year with a historic window from 2020–2025 and a forecast horizon through 2032—quantifies a robust recovery and structural expansion: the addressed global market (USD, revenue unit: Million) grew materially across the pandemic recovery and is projected to continue expanding at a compound annual growth rate (CAGR) of 6.95% through 2032. This trajectory translates into meaningful scale uplift for ingredient suppliers, beverage formulators, pharmaceutical ingredient vendors, and contract manufacturers. The market concentration profile—CR3 at 46.5% and CR5 at 59.2%—indicates a moderately concentrated supplier base with room for disruptive entrants and consolidation plays.
Caffeine Market
Market trajectory and what it means for 2026 strategy
-
Measured growth and structural demand: The market expanded from an estimated USD 1,372.5 Million in 2020 to USD 1,760.0 Million in 2025, and our scenarios project continued growth—reaching over USD 2,700 Million by 2032 under the central case. That growth is not linear: volatility in raw material availability, regulatory triggers, and product innovation create episodic acceleration and plateau periods that must be anticipated in planning cycles.
Caffeine Market -
Moderate concentration enables strategic options: With the top three and top five suppliers controlling roughly half and just under three fifths of the market respectively, buyers can secure scale advantages with incumbent suppliers while also evaluating vertically integrated or regional sources to improve resilience and cost flexibility.
Caffeine Market -
Regulatory tightening and labeling visibility will reshape consumer and trade flows. The U.S. Food and Drug Administration’s guidance on caffeine labeling in 2026, coupled with legislative proposals and existing EU rules on 'high caffeine' declarations, introduces immediate compliance costs for product portfolios and potential reformulation imperatives for many manufacturers.
Key strategic moves for 2026
-
Portfolio rationalization and premiumization: Brands should map SKU portfolios against regulatory thresholds and consumer preference vectors (natural vs. synthetic positioning, functional claims). The most immediate levers are targeted reformulation for at‑risk SKUs and development of premium, clearly labeled offerings that capture willingness‑to‑pay from health‑conscious segments.
-
Supply‑chain resilience and supplier segmentation: Implement a three‑tiered supplier strategy (strategic partners, transactional suppliers, and niche specialists) and embed real‑time procurement KPIs. Given recent capacity investments by incumbents and new green extraction facilities, buyers should renegotiate supply agreements with clauses for capacity scaling, sustainability verification, and price‑indexing tied to raw inputs.
-
M&A and JV prioritization: Strategic acquisitions remain efficient routes to secure feedstock control, proprietary extraction technologies, or route‑to‑market in growth regions. Our report’s screening matrix highlights target profiles that accelerate access to natural caffeine sources, GMP‑compliant API capabilities, or novel delivery systems.
-
Innovation and alternative ingredient strategies: R&D leaders must diversify formulations—experimenting with microencapsulation, sustained‑release matrices, and curated blends with adaptogens—while evaluating caffeine alternatives and hybrid recipes that mitigate regulatory exposure and extend intellectual property defensibility.
-
Regulatory readiness and consumer communication: Expect labeling changes (U.S. guidance in 2026, proposed federal rules under consideration, and existing EU labeling thresholds) to drive timely updates to packaging, digital ingredient declarations, and point‑of‑sale claims. Companies should pre‑build regulatory scenarios into 2026 product roadmaps to avoid market access disruptions.
What the PW Consulting report delivers (practical, actionable content)
-
Transparent market sizing and scenario models: Excel‑based models with base‑case, upside, and downside scenarios calibrated to macro drivers, regulatory inflection points, and alternative supply scenarios. Models are presented in USD (Million) and align to fiscal planning cycles for 2026 budgeting.
-
Go‑to‑market playbooks: Detailed 12–24 month plans by channel (beverage, pharmaceutical excipient, sports nutrition and supplement channels, and food applications) with prioritized initiatives, expected investment ranges, and ROI benchmarks tailored for incumbents and challengers.
-
Supplier and capability matrix: Comparative profiles of incumbent and emerging suppliers, including manufacturing footprint, compliance credentials (GMP, FSSC, ISO), technical service capabilities, and sustainability claims. The matrix is designed for rapid vendor short‑listing and RFP planning.
-
Regulatory risk heat map and compliance playbook: A practical checklist for labeling, claims, and threshold management across major jurisdictions—complete with breach scenarios, mitigation steps, and estimated compliance costs.
-
Commercial benchmarking and pricing levers: Market rate bands, margin analyses, and negotiation tactics for both spot procurement and long‑term offtake contracts. Sensitivity analyses demonstrate EBITDA impact of +/- X% input cost moves and regulatory compliance investments.
-
M&A screening tools: A short‑list of acquisition archetypes, valuation heuristics, and a rapid‑due‑diligence template focused on manufacturing quality, regulatory affairs, and intellectual property.
Competitive landscape — who matters and why
The competitive set includes integrated chemical majors, specialized pharmaceutical manufacturers, natural‑ingredient suppliers, and ingredient innovators. Below are the core companies we analyzed and the practical implications for strategy teams.
-
BASF SE (Ludwigshafen, Germany) — A global leader in synthetic anhydrous caffeine production. BASF’s recent capacity expansion in Germany (March 2026) signals ongoing commercial confidence in beverage and nutraceutical demand. Strategic implication: BASF’s scale makes it a preferred partner for large‑volume beverage contracts; however, buyers should use capacity cycles to negotiate flexible pricing and co‑innovation clauses.
-
CSPC Pharmaceutical Group Limited (Shijiazhuang, China) — Major producer of pharmaceutical‑grade caffeine, with extensive API capabilities. Strategic implication: CSPC is a credible partner for firms seeking GMP‑grade supply; consider dual‑sourcing and quality audits to mitigate regulatory risks tied to APIs.
-
Aarti Industries Limited (Mumbai, India) — Producer serving both natural and synthetic demand for food and beverage sectors. Strategic implication: attractive for regional partnerships and cost‑advantaged supply; assess sustainability credentials for natural claims.
-
Spectrum Chemical Mfg. Corp. (Gardena, California, USA) — Supplier of pharmaceutical and food‑grade anhydrous caffeine. Strategic implication: strong fit for niche pharma and small‑batch specialty formulations; leverage technical service capabilities for new product development.
-
Shandong Xinhua Pharmaceutical Co., Ltd. (Jinan, China) — Manufacturer of synthetic and natural caffeine; launched a green extraction facility in December 2025. Strategic implication: compelling option for customers prioritizing sustainability and lower environmental footprint; evaluate scale and long‑term feedstock security.
-
Cargill, Incorporated (Minneapolis, USA) — Leading supplier of natural caffeine from green coffee and guarana extracts. Strategic implication: strong channel access to beverage and supplement brands seeking naturally‑sourced claims; partnerships can accelerate market entry for natural‑positioned SKUs.
-
Nutrabolt (USA) — Producer of natural caffeine‑based energy ingredients for sports nutrition. Strategic implication: valuable co‑branding and formulation partner for performance nutrition lines.
-
DSM‑Firmenich (Basel, Switzerland) — Supplier of science‑driven caffeine alternatives and ingredients for sport and functional beverages. Strategic implication: trendsetter for next‑generation actives and differentiated delivery formats—key for firms pursuing premium functional positioning.
Regulatory and policy dynamics — immediate 2026 considerations
-
U.S. FDA guidance (2026): The FDA’s 2026 guidance on caffeine labeling will raise the bar for transparency. Companies must review ingredient declarations, serving‑size definitions, and on‑label claims to ensure continuity of market access and to avoid recalls or enforcement action.
-
Proposed federal legislation: The Sarah Katz Caffeine Safety Act (H.R. 2511) would require caffeine content labeling on foods and dietary supplements exceeding low thresholds. Though not yet enacted, the proposal increases legislative risk and should be included in compliance scenario planning.
-
EU labeling norms: Existing EU rules require declaration and warnings for products exceeding defined caffeine concentrations—requirements that continue to influence formulation strategy for products destined for EU markets.
How to use this intelligence in 2026 planning
-
Integrate the report’s scenario models into your 2026 budget and 3‑year strategic plan. Run sensitivity tests on input cost shifts, regulatory compliance timelines, and consumer demand elasticity to prioritize investments.
-
Use the supplier matrix to shortlist partners for pilot agreements and offtake contracts that include sustainability KPIs and regulatory warranties.
-
Adopt the regulatory heat map to sequence packaging updates and SKU rationalization ahead of enforcement milestones—minimizing trade disruption in major markets.
-
Leverage M&A screening to accelerate capability acquisition in extraction technology, GMP API capacity, or channel reach—particularly where organic build timelines exceed strategic windows.
Next steps — where to find the deeper analysis
This article outlines the strategic framing and practical levers that corporate decision‑makers should prioritize in 2026. The full PW Consulting Caffeine Market report contains the proprietary segmentations, granular regional and application splits, downloadable model files (USD, revenue unit: Million), supplier scorecards, and a prioritized M&A watchlist that we deliberately exclude here to preserve the value of the primary deliverable.
For access to the complete datasets, Excel scenario models, and the supplier short‑list that underpin this analysis, please visit our report page or contact PW Consulting. The full report is designed for commercial teams, R&D and regulatory leaders, and corporate development groups who require executable intelligence to move from insight to implementation in 2026.
For detailed analysis of this topic, please visit the official page: Caffeine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com