

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Peanuts Market Set for 5.2% CAGR Through 2032

Peanuts Market 2026: Strategic Imperatives for Decision‑Makers
Executive snapshot
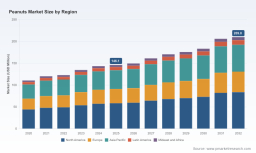
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our new Peanuts Market study — the definitive guide for commercial leaders, procurement heads, investors, and policy advisors who must make high‑stakes decisions in 2026. Grounded in a 2020–2025 historical review and a 2026–2032 forecast, the report quantifies a clear, investable trajectory: the global market, measured in USD (Million), has expanded steadily from its 2020 base and reached a sizable position in 2025 (base year), and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.2% through 2032. By 2032 the market is expected to approach the low‑hundreds in USD (Million), reflecting both consumption resilience and new industrial demand vectors.
Peanuts Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is a hinge year. Economic normalization post‑pandemic, coupled with renewed consumer interest in protein and plant‑based snacks, has created a window where strategic positioning today materially affects market share and margin outcomes over the coming three‑to‑five years.
Peanuts Market -
Clarity on growth drivers: The market’s mid‑single‑digit CAGR masks differentiated pockets of upside — premium snacking innovations, ingredient demand from confectionery and plant‑based formulations, and value‑add processing. Senior teams must distinguish durable structural shifts from temporary demand shocks.
Peanuts Market -
Operational levers matter: Supply‑chain resilience, quality control around aflatoxin management, tariff and quota preparedness, and farm‑level agriscience investments are now tangible value drivers. Our study links macro growth to micro levers that executives can operationalize in 2026.
Market trajectory: what the numbers tell us (and what they don’t)
The market’s path from 2020 through the 2025 base year demonstrates consistent expansion, followed by a forecast that anticipates continued, steady growth at a ~5.2% CAGR across 2026–2032. This is sufficient growth to justify incremental capacity investments, yet modest enough to require disciplined capital deployment and rigorous go‑to‑market planning. Importantly, concentration metrics indicate a fragmented supplier landscape — the top few firms do not dominate the market to the extent seen in many other food ingredient sectors — leaving room for differentiated plays by nimble processors, branded manufacturers, and regional consolidators.
Structural forces shaping 2026 decisions
-
Regulatory and trade posture: Tariff safeguards, import thresholds, and quota regimes are no longer peripheral. For example, safeguard tariffs and minimum access quotas create predictable supply‑side friction points that affect short‑term sourcing choices and long‑term sourcing strategies. Boards and procurement teams must incorporate scenario models that reflect both tariff shocks and quota reallocation risks.
-
Agronomic supply dynamics: A material uptick in U.S. production year‑on‑year underscores that raw‑material availability can swing rapidly. Traders and processors should reassess procurement windows, hedging strategies, and direct grower partnerships to capture quality differentials and control logistics costs.
-
Food safety & quality: Ongoing industry investment in aflatoxin research and grading standards continues to be a gating constraint for premium markets and export channels. Companies investing in upstream quality assurance and testing protocols will unlock higher‑margin channels and reduce recall risk.
-
Consumer and product innovation: Recent product launches and packaging experiments highlight two converging themes — premiumization and convenience. Expect established FMCG players to increasingly co‑opt peanut ingredients into broader snacking and confectionery launches, while ingredient processors pivot to serve industrial applications with customized specifications.
-
Sustainability and farm investment: Leading global brands are moving from commitments to tangible agriscience investments at the farm level. These programs reduce volatility and create longer, higher‑value supplier relationships — an advantage for firms that can integrate traceability, regenerative practices, and capacity building into commercial contracts.
Competitive landscape: high‑level positioning of focal players
Our analysis profiles the full competitive set, with a particular focus on global brands, regional shellers/ processors, and export suppliers that meaningfully shape supply and demand dynamics.
-
Branded consumer goods leaders (examples): Companies with national and global peanut‑incorporated brands continue to drive category innovation and shelf presence through product extensions, marketing, and packaging experiments. Their strategic choices determine ingredient specifications, packaging formats, and off‑take patterns for processors.
-
Large shellers and processors (examples): Domestic shellers and processors remain the backbone of ingredient supply. Their investments in processing efficiency, capacity expansion, and B2B product development set the baseline for delivered cost and ingredient consistency.
-
Regional and international suppliers (examples): Exporters from major producing origins play a critical arbitrage role. Their price and quality competitiveness puts pressure on domestic supply chains, especially under variable tariff and quota regimes.
Across all player types, recent corporate moves — from new flavor launches to packaging innovation and farm‑level sustainability pledges — are early signals that the next phase of competition will combine brand creativity with tighter upstream control.
Recent industry signals you should weigh now
-
Product innovation: National rollouts of new peanut‑flavored SKUs demonstrate that major brands see incremental consumer appetite for peanut‑centric premium offerings. These launches expand ingredient demand into adjacent categories.
-
Packaging as a commercial lever: New packaging formats enhancing shelf impact and on‑the‑go convenience are changing stocking logic for retailers and opening price‑realization opportunities for manufacturers.
-
Sustainability spend: Targeted agriscience investment programs from large confectionery groups indicate a willingness to co‑finance upstream resilience measures — a strategic channel for processors and CPGs to secure consistent quality and favorable commercial terms.
-
Policy and standards: Recent legislation and agency standards continue to shape support mechanisms for domestic producers and create compliance obligations for shellers and buyers. These developments should be embedded into 2026 operating budgets and supplier audits.
What the PW Consulting Peanuts Market report delivers (practical content)
Our full study is designed as an operational playbook that translates macro outlook into immediate, executable actions:
-
Strategic scenarios and stress tests — forward cases calibrated to tariff and production stress events so executives can quantify downside and identify mitigation thresholds.
-
Go‑to‑market playbooks for branded and ingredient players — product concept prioritization, pricing levers, private‑label vs national brand strategies, and retailer negotiation frameworks.
-
Supply‑chain diagnostics and sourcing options — regionally differentiated procurement roadmaps, supplier segmentation, and a decision matrix for vertical integration vs. contract consolidation.
-
Regulatory and quality compliance toolkit — grading and aflatoxin control pathways, recommended testing cadence, and checklist templates for buying‑point compliance.
-
M&A and partnership screens — a targeted list of strategic acquisition themes and JV structures that create scale while preserving margin.
-
Financial models and dashboards — customizable templates that translate market scenarios into P&L and working capital implications for 2026 planning cycles.
How to use this study in your 2026 playbook
-
Procurement heads: Rebase sourcing strategies to include quota and safeguard scenarios, strengthen grower contracts with quality clauses, and pilot traceability projects tied to premium channels.
-
Operations & supply chain: Prioritize investments in sorting, testing, and processing flexibility to capture margin from differentiated product specs; deploy rolling capacity plans tied to short‑term production signals.
-
Product & marketing: Use the innovation roadmap in the report to sequence launches and pilot premium formulations that leverage emerging consumer preferences while preserving base volume channels.
-
Investors & corporate development: Use the M&A screen and concentration analysis to identify consolidation targets that provide cost synergies and route‑to‑market advantages in a fragmented market.
Trailer: what we intentionally withhold here (and why)
In keeping with PW Consulting’s “trailer” approach, this overview surfaces the critical strategic implications, industry signals, and practical uses of our Peanuts Market study. To preserve the commercial value of the analysis for subscribers, we do not disclose the granular regional and application splits or the detailed company share tables in this preview. Those segmental matrices, heatmaps, and underlying primary research are available in the full report and online dataset. If your 2026 roadmap depends on precise regional demand trajectories or application‑level pricing curves, you will need the full dataset to model execution at the required fidelity.
Next steps
For senior teams preparing 2026 budgets and three‑year operating plans, the marginal value of this study is highest in the next 60–90 days: align scenarios, test sourcing and packaging pilots, and establish early farm‑level partnerships. The full report provides the granular inputs and executable templates to turn these recommendations into measurable outcomes. Contact PW Consulting or visit our report page to access the complete dataset, annexes, and client‑only strategy workshops.
— Senior Strategic Consultant & Chief Industry Analyst, PW Consulting
For detailed analysis of this topic, please visit the official page: Peanuts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com