

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PVB Films Market to Top USD 2,730M by 2032 at 6.98% CAGR

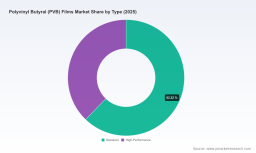
Polyvinyl Butyral (PVB) Films Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive preview
The global Polyvinyl Butyral (PVB) films market sits at a pivotal juncture entering 2026. Our bottom-line market sizing places the industry at USD 1,750 Million in the report base year (2025), up from approximately USD 1,400 Million in 2020. Under conservative-to-optimistic scenarios the market is projected to expand to roughly USD 2,730 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. For leaders evaluating strategic choices this year, those headline numbers represent quantifiable demand momentum — but they mask granular stresses and opportunities that will determine winners and laggards over the next 24 months.
Polyvinyl Butyral (PVB) Films Market
Why 2026 is a strategic inflection point
Three structural dynamics converge in 2026 to make it an inflection year:
Polyvinyl Butyral (PVB) Films Market
- Regulatory tightening: Global safety and optical standards have shifted. Notably, amendments to ECE R43 require higher-energy impact resistance for windshields, driving nominal increases in typical PVB thickness for compact vehicles; parallel harmonization of China’s standards with ISO optical rules is accelerating OEM preference for certified, branded interlayers. North America is actively consulting on expanding laminated glazing requirements, a change that would materially widen addressable volumes.
- Supply-side pressure: Feedstock dynamics are subtle but consequential — butyraldehyde availability tightened slightly in 2025 (a modest decline concentrated in Asia-Pacific hubs), producing short-term cost volatility and creating a leverage point for integrated suppliers and traders.
- Market structure and competitive discipline: The PVB films market remains concentrated among a handful of global incumbents, creating a balance of pricing discipline and high certification barriers. At the same time, product differentiation (standard vs. high-performance and specialty sustainability credentials) is emerging as a durable margin lever.
Together these forces mean that 2026 will not be business as usual. Firms that treat the year as a planning cycle rather than an execution inflection risk ceding margin or losing strategic footholds in high-growth end uses.
Polyvinyl Butyral (PVB) Films Market
Key near-term developments highlighting market direction
- Product and sustainability positioning: In April 2026, a leading global supplier expanded a “lite carbon” PVB range with verified sustainability credentials — a signal that OEMs and institutional buyers are rewarding verified lifecycle attributes.
- Commercial discipline by incumbents: Price adjustments by major suppliers in 2026 underscore the capacity of integrated producers to pass through cost and to defend margins, particularly where certification and track record reduce buyer friction.
- Certification and regulatory hurdles: ISO, ASTM and IATF certification regimes remain effective gatekeepers; newcomers face meaningful time- and investment-to-market — a structural advantage for established brands.
What the PW Consulting report delivers — practical, decision-grade content
This study was built to be an operational tool for 2026 planning cycles. Key deliverables include:
- Proprietary bottom-up market model (2020–2032) with base-year reconciliation, quarterly seasonality overlays, and a scenario engine calibrated to regulatory, feedstock, and OEM adoption levers.
- Supply-demand balance and raw-material dashboard highlighting regional feedstock flow risks, cost curves and marginal production economics.
- Regulatory impact modules that quantify the demand shifts from recent ECE and ISO alignments under multiple adoption timelines.
- Competitive landscaping with strategic scorecards: capability matrices covering production footprint, product range (including high-performance grades), certification status, and sustainability credentials.
- Commercial playbooks for procurement, pricing, and OEM engagement plus M&A screens identifying viable bolt-on targets and integration risks.
- Operational implementation checklists — from testing and certification gating to supplier qualification — designed for cross-functional teams (procurement, product, regulatory, manufacturing).
- Access to the underlying Excel model and an executive slide deck for board-level briefings; interactive dashboards are available for tailored client workshops.
To preserve the report’s commercial integrity and to adhere to the “trailer” principle, the summary above intentionally highlights capabilities rather than publishing the report’s detailed regional, application or type splits — those are available in full to licensed report purchasers and consultancy clients.
Competitive dynamics — what incumbents are doing and why it matters
The market is dominated by a small set of multi-regional suppliers that combine branded interlayer offerings, established OEM relationships, and certification depth. The competitive posture of each incumbent matters differently for buyers and for potential entrants:
- Integrated branded producers are using product breadth and certification to defend higher-margin segments and to accelerate branded adoption by OEMs and architectural specifiers. Recent product expansions that include sustainability verifications illustrate how incumbents are staking out premium positions.
- Price moves by major producers demonstrate the speed with which upstream cost shifts (feedstock and energy) can propagate through the value chain once certification lock-in reduces short-term supplier switching.
- Independent producers and regional players can compete on lead-time, customization and local regulatory familiarity, but they face elevated certification and capital requirements to scale into automotive-grade supply.
For executives, the takeaway is straightforward: supplier selection is now a multi-dimensional decision—cost matters, but certification, product portfolio, supply-chain resilience and sustainability credentials are equally determinative of long-term TCO and risk.
Priority strategic moves for 2026 decision-makers
Our analysis yields a short list of high-impact, executable actions for suppliers, OEMs, and investors entering the 2026 planning window:
- Procurement: Shift from short-term spot buying to portfolio contracting that explicitly models certification lead-times and feedstock risk. Negotiate clauses for capacity commitments, quality penalties and sustainability proofs.
- Product & R&D: Prioritize certification investments (optical and mechanical) and accelerate development of higher-performance and low-carbon interlayer variants where OEM roadmaps indicate adoption potential.
- Manufacturing & CAPEX: Use the report’s scenario engine to stress-test planned capacity increases against feedstock volatility and regulatory-driven demand uplifts. Phase investments to preserve optionality.
- Commercial & Pricing: Implement a scenario-based price governance framework that can communicate cost drivers transparently across the value chain while protecting margin during episodic shocks.
- M&A & Partnerships: Target acquisitions that close certification gaps, add localized production in growth geographies, or bring differentiated technologies (optical control, acoustic damping, solar-enabled interlayers).
- Risk Management: Build a supply-visibility program for butyraldehyde and related intermediates, and create contingency sourcing protocols for Asia-Pacific supply disruptions.
Scenario lens — three plausible 2026–2028 trajectories
- Constrained-supply / Margin expansion: Tight feedstock supply and phased regulatory adoption trigger higher realized prices; incumbents with integrated feedstock positions tighten market share. Players without forward coverage or certification face margin compression.
- Baseline growth: Gradual regulatory adoption and steady electrification of vehicles sustain the historical demand trajectory reflected in the mid-single-digit CAGR; suppliers balance price and volume through contractual discipline.
- Accelerated adoption: Faster-than-expected regulatory roll-outs and accelerated OEM specification of higher-performance and sustainable interlayers produce above-trend demand, favoring suppliers with flexible capacity and validated sustainability credentials.
Each scenario has distinct implications for capex timing, working capital, supplier strategy and M&A appetite — the full report provides quantitative overlays for each to inform board-level decisions.
Closing — why this study should be part of your 2026 playbook
For leadership teams weighing investments, procurement frameworks or M&A in 2026, the PVB films market will reward precision: precise modeling of regulatory impact, precise assessment of certification timelines, and precise management of feedstock and logistics risk. The topline market trajectory — rising from roughly USD 1.75 Billion in 2025 toward the multi‑billion-dollar horizon by 2032 at a near 7% CAGR — signals opportunity, but the real value lies in navigating the micro-dynamics outlined above.
PW Consulting’s full study provides the granular datasets, scenario models, and competitive scorecards required to turn those strategic imperatives into executable 90-day and 24-month plans. To access the complete market tables, interactive model and bespoke advisory options, please consult PW Consulting’s report distribution page or contact our industry team for a tailored briefing and model license.
For detailed analysis of this topic, please visit the official page: Polyvinyl Butyral (PVB) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com