

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Demineralized Allografts Market Poised for 5.1% CAGR Through 2032

Demineralized Allografts Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise but deeply informed preview of our full Demineralized Allografts Market study — a research product designed to be directly actionable for executives, corporate strategists, product leaders, and M&A teams as they plan for 2026. Below I synthesize the market’s macro trajectory, the competitive and regulatory forces that will shape near-term outcomes, and the types of strategic moves that will decide winners and laggards. This preview intentionally highlights insight and frameworks while withholding select granular segmentation outputs — our objective is to demonstrate the study’s strategic value and prompt direct engagement for full access to the underlying models and segment-level intelligence.
Demineralized Allografts Market
Why 2026 is a Pivotal Year
-
The demineralized allografts market has demonstrated steady expansion since 2020 and entered 2026 from a position of resilience: the market grew from just over USD 1.0 million in 2020 to approximately USD 1.3 million in 2025 (base year), and our model projects continued growth across the 2026–2032 forecast window. The compound annual growth rate (CAGR) underpinning this forecast is 5.1% — a pace that signals a predictable but strategically active market environment.
Demineralized Allografts Market -
For 2026 strategic planning, this is a market where disciplined investments in portfolio differentiation, regulatory navigation, and integrated supply-chain resilience will deliver asymmetric returns relative to competitors who continue to compete principally on price or legacy distribution channels.
Demineralized Allografts Market
Market Trajectory — The Big Picture
Across the historical period (2020–2025) the market displayed steady single-digit expansion, driven by demographic tailwinds, broader adoption of biologics in spine and orthopedic surgery, and incremental product innovation (flowable media, fiber formulations, and cryopreserved viable allografts). Our base-year assessment (2025) and forward model through 2032 reflect a maturation phase: growth remains positive and structurally supported, but the market is moving from early-adopter diffusion into selective consolidation.
Key implications for 2026: firms with clear clinical differentiation or regulatory clarity will capture disproportionate share expansion; those without will face margin pressure as procurement bodies emphasize cost-effectiveness and evidence-backed outcomes.
Dynamics That Matter
-
Regulatory posture is a competitive axis. Human demineralized bone matrix products sit at an intersection of tissue and device regulation: minimally manipulated HCT/P categorization applies for certain harvest-and-transplant uses, while modified DBM products with additives fall under Class II medical device controls requiring 510(k) premarket notification and established special controls. Recent FDA guidance reinforces this bifurcation, and clarifications issued through 2025–2026 raise the bar on documentation, design controls, and post-market surveillance.
-
Product innovation is increasingly clinical- and logistics-driven. Flowables, reverse-phase carriers, cryopreserved viable allografts, and fiber formats are not just marketing variations — they change surgical handling, graft incorporation profiles, and supply chain requirements (cold chain vs ambient storage). Our full study quantifies the operational and clinical trade-offs that drive adoption in different surgical pathways.
-
Concentration and channel dynamics favor established tissue banks and medtech integrators. Distribution relationships with hospitals, ambulatory surgery centers, and specialty clinics remain critical; however, new entrants with targeted propositions (e.g., dental viable grafts, injectable DBM pastes) can accelerate adoption in niche segments if they secure clinical champions and streamlined regulatory pathways.
-
Procurement pressures and health-economics scrutiny are rising. Payers and hospital networks increasingly evaluate graft selection through an outcomes-and-cost lens. Demonstrating improved OR time, reduced reoperation, or favorable cost-per-quality-adjusted-life-year (QALY) metrics materially affects adoption in large health systems.
Competitive Landscape — Who Moves First Wins
The field is populated by a mix of large medtech incumbents, established nonprofit tissue banks, and specialized biologics suppliers. The market’s competitive topology is characterized by a handful of organizations that combine tissue banking volume with commercial reach, and a broader set of players focused on differentiated product formats or surgical specialties.
-
Major tissue banks and integrators (examples include MTF Biologics, AlloSource, LifeNet Health) offer vertical capabilities from tissue procurement through processing and distribution. Their strengths are scale, established clinical relationships, and platform-level quality systems. These players are best positioned to absorb increased regulatory documentation burdens and to invest in next-gen formats.
-
Large medtech firms (examples include Medtronic, Zimmer Biomet, Stryker) leverage global sales channels and clinical trial infrastructures to scale new DBM formats quickly. Their typical playbook bundles DBM options with hardware solutions in spine and trauma — creating integrated product-service propositions that hospitals find convenient.
-
Specialists and agile innovators (e.g., ZimVie, SeaSpine, Xtant Medical, RTI Surgical, Orthofix, HansBioMed) focus on one or two product formats or surgical niches. Their advantage is speed-to-market and focused clinical evidence generation, often enabling premium pricing for clear-use scenarios.
Recent industry moves underscore these dynamics: a major 510(k) clearance for an enhanced DBM paste and the launch of a cryopreserved viable dental allograft in 2025 both highlight two simultaneous trends — regulatory pathway maturation for modified DBM and targeted product introductions for dentistry and spine. These are indicative of how leading players are bifurcating the market into evidence-driven premium segments and cost-competitive commoditized segments.
Strategic Imperatives for 2026
-
Prioritize regulatory clarity early. If your roadmap includes modified DBM products or additive carriers, invest in regulatory resourcing and early engagement with authorities. A well-executed 510(k) strategy materially shortens commercialization timelines and is often the gating factor for reimbursement conversations.
-
Design portfolio plays by surgical pathway, not by product format alone. Different formats (flowable, fiber, cryopreserved viable grafts) alter clinical workflows; build value narratives that tie directly to surgeon ergonomics and hospital economics. Our full analysis maps these pathways and assigns differential adoption probabilities across them.
-
Build strategic partnerships with tissue banks or clinical networks. If you lack scale in tissue sourcing or distribution, alliances can accelerate market access while defraying upfront capital in processing facilities and donor networks.
-
Invest in outcomes data. Health systems increasingly require real-world evidence demonstrating reduced reoperation rates or improved integration. Early investment in registries and post-market studies becomes a durable barrier to entry.
-
Plan for supply-chain contingencies. Cold chain handling for viable allografts and donor material variability require robust supplier qualification and logistics contingency planning. Operational resilience directly affects time-to-surgery and customer service metrics.
What Our Full Report Delivers (Operational, Not Just Observational)
-
A validated market model (historical 2020–2025 baseline; forecast 2026–2032) with scenario toggles to test alternative growth, pricing, and regulatory timelines.
-
Competitive profiles and capability maps for all major players — including manufacturing footprints, product portfolios, regulatory status, and go-to-market channels. (Preview above lists core firms; the report contains deeper playbooks and direct comparison matrices.)
-
Decision tools: investment heatmaps for portfolio prioritization, an M&A target short-listing methodology, and a due-diligence checklist for tissue-bank partnerships and product acquisitions.
-
Regulatory and reimbursement playbooks tailored to DBM formats and surgical specialties, with a timeline of key FDA guidance and likely enforcement touchpoints.
-
Clinical evidence frameworks mapping the minimum study designs required to influence hospital procurement committees and payers, including sample size estimates and expected time-to-evidence thresholds.
-
Supply-chain risk assessment with mitigation options for donor variability, cold chain logistics, and single-source dependencies.
Scenario Thinking — Three Pathways to 2032
-
Consolidation-led growth: incumbents leverage scale and regulatory muscle to consolidate niche players; value accrues to vertically integrated providers that can optimize cost and evidence generation.
-
Clinical-differentiation uplift: innovators who deliver measurable clinical advantages (reduced surgery time, better incorporation) create premium sub-segments with higher margins and selective adoption across high-volume centers.
-
Commoditization pressure: procurement-led cost competition squeezes margins for undifferentiated products, accelerating price sensitivity and favoring players that can neutralize costs through scale or lower-cost sourcing.
How to Use This Preview
Consider this preview your strategic checklist for 2026: validate regulatory readiness, map surgical-pathway value, invest in outcomes, and hedge supply-chain exposures. For corporate development teams, the full PW Consulting report offers an executable M&A rubric and target profiles; for product leaders it provides a prioritized set of clinical studies and commercialization tactics; for commercial teams it supplies channel playbooks keyed to hospital procurement dynamics.
Next Steps — Accessing the Full Intelligence
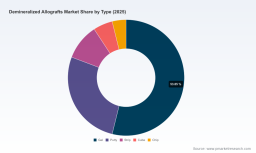
This article intentionally omits select segment-level percentages and the full quantitative elasticity matrices that power our acquisition and pricing models. Access to the complete dataset, interactive forecast model, and competitor scorecards is available via the PW Consulting report page. For executive briefings, scenario workshops, or custom modeling tailored to your portfolio, contact our industry team to schedule a confidential session.
In markets like demineralized allografts, where regulatory nuance, clinical evidence, and distribution mastery intersect, the right strategic choices in 2026 will determine who captures the most valuable growth pockets through 2032. PW Consulting’s full study is built to make those choices with conviction — not conjecture.
For detailed analysis of this topic, please visit the official page: Demineralized Allografts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com