

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CRP Test Market to Reach USD 1,588 Million by 2032 at 6.98% CAGR

C-Reactive Protein (CRP) Test Market — Strategic Preview for 2026 Corporate Decisions
As healthcare systems re‑calibrate in the mid‑2020s, C‑Reactive Protein (CRP) testing is re‑emerging as both a clinical staple and a commercial battleground. PW Consulting’s latest market study, built on a 2020–2025 historical base and projecting through 2032, quantifies a market that has grown from roughly USD 750 million in 2020 to USD 1,000 million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of approximately 6.98% across the 2026–2032 horizon. By 2032 the market is expected to approach the USD 1.6 billion range, driven by converging clinical demand, technology diffusion, and shifting reimbursement dynamics. This preview synthesizes strategic implications for 2026 decision‑making while preserving the granular, commercial‑grade data available in the full report.
C-Reactive Protein Test (CRP) Market
Why CRP Matters Now — Clinical and Commercial Catalysts
-
Clinical convergence: CRP remains a rapid, broadly validated biomarker for inflammation, infection triage, and cardiovascular risk stratification. Its role in emergency departments, primary care, cardiology, and infectious disease pathways keeps demand resilient through episodic public‑health shocks and cyclical care utilization.
C-Reactive Protein Test (CRP) Market -
Point‑of‑care acceleration: The push to decentralize diagnostics has materially expanded addressable channels. Rapid, cartridge‑based and point‑of‑care (PoC) fluorescence/immunoassay platforms shorten decision cycles and open new revenue streams beyond centralized laboratories.
C-Reactive Protein Test (CRP) Market -
Technology stratification: Product classes — from standard immunoturbidimetric assays to high‑sensitivity and ultra‑sensitive hsCRP formats — are differentiating clinical use cases and pricing tiers. This stratification creates pockets of premium margin for firms that secure clinical validation and payor recognition.
-
Regulatory and coding inflection points: Recent updates to HCPCS coding and ongoing regulatory guidance shape coverage, payment rates, and market access timelines, affecting near‑term unit economics for new product launches.
Market Structure and Competitive Dynamics — What the Topography Tells You
The market exhibits meaningful concentration: the three largest vendors account for a clear majority share, and the top five firms control an even larger portion of commercial revenues. This concentration underscores two strategic realities for 2026:
-
Scale matters for reagent supply and lab integration — established instrument manufacturers maintain preferential access to high‑volume channels and bundled purchasing relationships with hospital systems and reference labs.
-
There are defensible niches for specialists and PoC innovators — companies that deliver speed, convenience, or differentiated analytics can extract premium pricing and faster adoption in ambulatory settings.
Key players profiled in the study include platform incumbents and PoC specialists. Each presents a distinct strategic posture that matters for potential partners, acquirers, and competitors:
-
ProciseDx Inc. (United States): A PoC innovator with an FDA‑cleared instrument and a rapid fluorescence immunoassay that delivers quantitative CRP results in minutes. Strategic edge: speed and PoC positioning; strategic considerations: scaling manufacturing and reimbursement acceptance.
-
Abbott Laboratories (United States): A large, diversified diagnostics player with cartridge‑based CRP assays optimized for rapid, decentralized use. Strategic edge: channel reach and established cartridge ecosystem; strategic considerations: pricing pressure in high‑volume channels.
-
Roche Diagnostics (Switzerland): A major laboratory systems provider with reagent families tailored for cobas and Integra platforms and broad clinical validation for cardiac and inflammatory use cases. Strategic edge: lab installed base and assay standardization; strategic considerations: defending margins in mature lab segments while enabling PoC connectivity.
-
Siemens Healthineers (Germany): Focused on hsCRP for cardiovascular risk stratification across Dimension and BN instrument lines. Strategic edge: cardiovascular diagnostics portfolio alignment; strategic considerations: securing guideline endorsement and payer recognition for hsCRP use cases.
-
Beckman Coulter, Inc. (United States): Provider of quantitative CRP reagents for widely used chemistry analyzers; recent product documentation updates signal ongoing product lifecycle management and supply continuity efforts.
-
Sekisui Diagnostics (Japan): Specialist in immunoturbidimetric CRP kits with flexible kit sizing directed at both labs and hospital networks. Strategic edge: reagent economics and kit formats adaptable to client throughput.
-
QuidelOrtho Corporation (United States): Supplier of CRP slides for VITROS systems; recent recall activity and its subsequent resolution exemplify operational and reputational risk drivers in this market.
Recent Developments that Matter for 2026 Strategy
-
Reimbursement and coding shifts: CMS updates to HCPCS (notably January and mid‑year 2026 notifications) have altered the payment landscape. These changes influence both test utilization and product pricing strategies — urgent input for commercial models and contracting negotiations.
-
Regulatory guidance endurance: FDA guidance documents for CRP/hsCRP and cardiac CRP assays remain the touchstone for clinical claims and submission expectations. Companies advancing new hsCRP or cardiac CRP claims should preemptively map their analytical and clinical validation programs to those review criteria.
-
Quality and recall risk: The 2024 recall and subsequent resolution tied to a major supplier’s CRP slides demonstrate how product lifecycle events can transiently compress demand and open market access windows for competitors — and how rapid remediation can restore trust.
-
Supply‑economics signals: Reagents and cartridges continue to be packaged in standardized kit sizes (e.g., commonly seen 250‑, 600‑, and 1000‑test presentations). These sizes influence unit cost, inventory strategies, distributor economics, and tendering behavior.
What PW Consulting’s Full Report Delivers (Practical, Actionable Contents)
The study is engineered for executives making 2026 allocation decisions. Highlights include:
-
Robust market sizing and trend models (historical 2020–2025, base year 2025, and granular forecasts through 2032) with scenario sensitivities tied to adoption curves, reimbursement shifts, and PoC penetration.
-
Commercial due diligence templates and revenue modeling tools to stress‑test product launches, pricing strategies, and channel mixes.
-
Regulatory and reimbursement playbooks detailing likely submission requirements, coding sequences, and payer engagement approaches for CRP, hsCRP, and cardiac CRP claims.
-
Competitive heatmaps that capture product positioning, platform dependencies, and go‑to‑market strengths — calibrated for M&A, partnerships, and white‑label opportunities.
-
Supplier and cost benchmarking, including reagent kit sizing economics and manufacturing scale considerations to inform CAPEX and COGS planning.
-
Scenario planning sets and prioritized strategic options (fast followers, niche champions, scale consolidators) with clear decision gates for 2026.
-
Primary interview synthesis and methodological transparency to support board‑level debate and investor diligence.
Strategic Implications and Recommended Actions for 2026
-
Prioritize channel segmentation: Decide whether to compete as a lab‑centric scale player or a PoC specialist. Each path favors different investments (e.g., instrument partnerships vs. cartridge supply chains).
-
Lock down reimbursement pathways early: Coding and payment updates materially affect unit economics. Invest in payer intelligence and early utility studies to accelerate coverage decisions.
-
Design for supply resilience: Standard kit sizes drive inventory strategies. Optimize manufacturing footprint and buffer strategies to absorb demand shocks such as recalls or sudden uptake in PoC sites.
-
Invest in differentiation: Clinical claims around hsCRP and cardiac CRP require targeted validation. Selective investment here can convert clinical differentiation into durable pricing power.
-
Explore M&A and partnership windows: Given market concentration, bolt‑on acquisitions or distribution agreements can expedite access to installed bases and lab networks — but valuation discipline is critical.
-
Mitigate regulatory/quality risk: Build rapid response and traceability systems to reduce downtime in the event of adverse quality events that can otherwise erode trust and market share.
Final Note — Why This Preview Should Lead to the Full Study
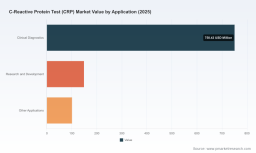
This market preview synthesizes the strategic contours that will matter to boards and commercial teams in 2026: a resilient growth trajectory, concentrated competitive forces, technology‑driven channel bifurcation, and a reimbursement/regulatory environment that is both a risk and an opportunity. For actionable granularity — including regional and application splits, detailed competitive revenue shares, modeled P&L impacts under alternative reimbursement scenarios, and downloadable financial models — please consult the full PW Consulting C‑Reactive Protein Test (CRP) Market study. The full report supplies the confidential tables and segment‑level analytics necessary to make defensible, high‑stakes decisions this year.
For detailed analysis of this topic, please visit the official page: C-Reactive Protein Test (CRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com