

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chloroacetic Acid Market Set for 6.5% CAGR Through 2032

Chloroacetic Acid Market 2026: Strategic Preview for Corporate Decision-Makers
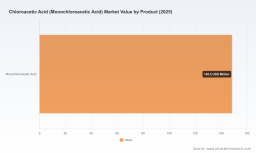
As companies reset priorities for 2026, monochloroacetic acid (MCA) occupies an outsized strategic position at the intersection of sustainability, specialty chemicals, and regulated supply chains. This briefing — derived from PW Consulting’s full Chloroacetic Acid (Monochloroacetic Acid) Market study (base year 2025; historical 2020–2025; forecast 2026–2032) — synthesizes the high‑impact signals executives need now to align investment, commercial and risk decisions with market momentum. The global MCA market has expanded from an estimated USD 120.0 Million in 2020 to USD 148.5 Million in 2025 and is projected to grow to approximately USD 230.5 Million by 2032, representing a compound annual growth rate of 6.5% over the forecast window. This preview demonstrates our analytical depth while intentionally omitting core segment-level tables and granular regional/application breakdowns — the gated intelligence available in the full report.
Chloroacetic Acid (Monochloroacetic Acid) Market
Why MCA Matters to 2026 Strategy
- Critical chemical intermediate : MCA remains a feedstock for high-value downstream chains — including surfactants, carboxymethylcellulose (CMC), herbicides, and pharmaceutical intermediates. Decisions around MCA supply therefore cascade into formulations, regulatory compliance, and brand positioning for a wide set of customers.
- Sustainability reframing of supply : Renewables-validated production routes and ISCC certification are rapidly becoming commercial differentiators. Producers already marketing ISCC PLUS-certified MCA secure preferential access to customers pursuing biobased claims and the circular‑feedstock narrative.
- Regulatory tightening : New potable water limits and stricter intermediate‑handling rules raise the bar for production and wastewater management. These rules generate compliance costs but also create opportunity for premium, high‑purity suppliers.
- Concentration, but not immobility : The supply base is notable for a handful of established global players together controlling a meaningful share of capacity. Concentration supports disciplined pricing, but recent project announcements and regional capacity investments indicate the market remains contestable.
- Feedstock volatility and margin pressure : Acetic acid and chlorine inputs are exposed to global commodity cycles. Recent feedstock cost increases have already translated to price inflation in core markets, creating both margin squeeze and short‑term arbitrage opportunities for agile producers.
Topline Market Momentum (What the numbers mean)
The 2020–2025 historical arc shows a recovery and step‑change in demand following pandemic era disruption; the forecast pathway to 2032 embeds steady, broad‑based growth driven by industrial end‑markets and incremental premiumization of product offerings (e.g., biobased and ultra‑pure grades). The market’s 6.5% CAGR reflects a combination of volume growth and price/mix improvements as downstream customers prioritize higher‑specification inputs and sustainability‑aligned sourcing.
Chloroacetic Acid (Monochloroacetic Acid) Market
What the Full Report Delivers (Practical, Actionable Content)
- Forward-looking demand model (2026–2032) with scenario runs that stress macroeconomic, feedstock and regulatory shocks — includes upside/downside supply curves and break‑even price sensitivities.
- Supply map and capacity analytics identifying structural chokepoints, prospective brownfield/greenfield projects, and near‑term availability risk by trade lane.
- Buyer playbook: procurement levers, contract archetypes, pass‑through mechanisms for feedstock inflation, and supplier scorecards tailored to automotive, detergent, agrochemical and pharma buyers.
- Purity and compliance matrix: cost/benefit for capital investment in ultra‑pure or low‑DCAA production routes, with payback ranges under multiple contract assumptions.
- Competitive landscape and capability heatmap (differentiators, supply security, sustainability certification, and specialty chem focus), plus strategic profiles of leading producers and emergent challengers.
- M&A & partnership playbook: target profiles, valuation benchmarks, integration risk checklists, and regulatory considerations across principal jurisdictions.
- Practical templates: sample term sheets, RFP frameworks, and wastewater compliance checklists to accelerate procurement and technical decision cycles.
Each deliverable is accompanied by data tables, supplier contacts, and executable recommendations that move beyond description to transaction-ready guidance. The full dataset and segment tables are available through the source link for clients requiring immediate deal support.
Chloroacetic Acid (Monochloroacetic Acid) Market
Competitive Landscape: Forces Shaping 2026 Positioning
- Nouryon (Amsterdam) — Early mover on renewable‑validated MCA. ISCC PLUS certification and adjacent supply to carboxymethylcellulose customers provide both strategic leverage and route to higher‑margin biobased products. Their product launches and facility integrations position them to capture procurement mandates tied to sustainability commitments.
- CABB Group (Germany) — Strength in high‑purity MCA and chlorinated intermediates for pharma and agrochemical use. The company’s focus on process control and quality appeals to customers for whom impurity profiles determine downstream feasibility.
- PCC MCAA (Poland) — Investing in capacity expansion for ultra‑pure MCA to serve European specialty channels. Their proposition is tailored to regulatory-driven demand for low‑impurity intermediates.
- Niacet (USA) & Daicel (Japan) — Diversified intermediates portfolios and longstanding relationships in CMC and thioglycolate value chains provide resilience; both are positioned to serve regional specialty demand with established logistics networks.
- AkzoNobel, Denak, Shandong Minji, Archit Organosys, Meridian Chem Bond — A mix of global specialty suppliers and regional producers. Their role is critical in meeting localized demand, offering competitive price points, or filling short-term supply gaps.
Market concentration metrics indicate a tight top‑tier: the three largest participants account for a substantial share of capacity, and the five largest for a dominant share. That concentration supports coordinated pricing discipline but also elevates the strategic value of targeted capacity additions or differentiated product lanes (e.g., ISCC‑certified or ultra‑pure grades) as routes to grow share without triggering price wars.
Regulatory, Cost and Infrastructure Signals to Watch
- Water quality regulation : Recent drinking water limits in certain jurisdictions introduce compliance cost and reputational risk for producers and users. Expect heightened monitoring, more stringent discharge controls, and a need for traceability in supply agreements.
- REACH and purity drivers : European regulatory expectations continue to favor high‑purity intermediates for specialty chemicals. Suppliers that can demonstrate low‑impurity production and robust documentation gain pricing power in regulated supply chains.
- Feedstock pressures : Acetic acid feedstock price swings will remain a primary margin lever. Producers with integration, long‑dated supply contracts, or hedging strategies will outperform during commodity episodes.
- Infrastructure concentration : Strategic production hubs that feed large downstream clusters (for example, facilities supplying the CMC market) create upstream downstream lock‑in. Control or access to such hubs is a competitive differentiator.
Strategic Playbook for 2026 (Immediate Actions and 18‑24 Month Moves)
- Secure feedstock lines and hedge price exposure — Build multi‑source acetic acid contracts with pass‑through clauses and consider strategic inventories for production continuity.
- Pursue certified supply paths where value accrues — Invest selectively in ISCC or equivalent certifications if customers require verified biobased inputs; this can unlock premium contract terms.
- Prioritize purity where regulation dictates — For pharma and specialty customers, consider brownfield upgrades for ultra‑pure output; model payback under conservative uptake scenarios.
- Evaluate tactical M&A or tolling partnerships — Target assets that add regional throughput, specialized purification capabilities, or downstream integration into CMC and surfactant value chains.
- Enhance compliance and disclosure — Upgrade monitoring, reporting, and wastewater treatment investments to address tightening potable water and discharge regimes.
- Customer segmentation and pricing intelligence — Differentiate commercial terms by end‑use sensitivity to feedstock volatility and regulatory risk; embed flexibility into long‑term agreements.
Conclusion — How to Use This Preview
This briefing highlights the strategic levers that will matter most in 2026: supply security, certification‑driven premiumization, purity‑led positioning, and tactical capacity moves in a concentrated market. PW Consulting’s full Chloroacetic Acid (Monochloroacetic Acid) Market report translates these high‑level imperatives into executable options, with the complete data tables, regional splits, application segmentation and supplier scorecards required to underwrite deals, capital projects, and procurement arrangements. We have deliberately withheld granular segment tables and region/application share detail in this preview — access to that gated intelligence accelerates execution and reduces transactional risk.
For executives evaluating capital allocation, M&A, or strategic sourcing in 2026, the window to act is open: price cycles and regulatory changes are creating differentiators that will crystallize over the coming 12–24 months. PW Consulting’s full report provides the playbooks, models and supplier diagnostics to convert those differentiators into market advantage.
For detailed analysis of this topic, please visit the official page: Chloroacetic Acid (Monochloroacetic Acid) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com