

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VCI Film Market to Grow at 2.8% CAGR (2026–2032)

VCI Film Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
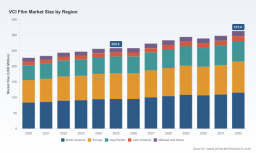
The PW Consulting VCI Film Market study (base year 2025) is written for corporate strategists, procurement leads, product managers, and M&A teams seeking a focused, actionable view of corrosion-inhibiting films as they plan for 2026 and beyond. Our analysis synthesizes five years of historical performance (2020–2025) and a forward-looking forecast (2026–2032). The headline: the global VCI film market is modest in absolute size but strategically important to industrial supply chains, exhibiting a steady compound annual growth rate (CAGR) of roughly 2.8% over the forecast window. After a near-term plateau around the 2025 level, the market resumes measured expansion through 2032 underpinned by demand from capital goods, automotive, and electronics supply chains and by a structural shift toward sustainable chemistries and circular-material strategies.
VCI Film Market
Why this report matters for 2026
- Decisions in 2026 will be made against a backdrop of regulatory tightening, raw-material volatility, and selective consolidation. Our research isolates these dynamics and translates them into immediate levers (sourcing, product spec, pricing, and partner selection) that reduce downside risk and capture upside.
- VCI films sit at the intersection of packaging, corrosion science, and sustainability. Small changes in chemistry, supplier capability, or regulation can deliver outsized P&L impacts for OEMs and packagers. This study quantifies those vectors and converts them into operational playbooks.
- For investors and corporate development, the sector’s concentration metrics show a market that is not tightly monopolized — leaving room for targeted acquisition or scale-up plays focused on technology differentiation or geography-specific services.
Market trajectory — what the numbers tell us
Our top-line figures provide a clear narrative: the VCI film sector reached a midpoint scale in 2025 and, despite short-term friction in 2026, is projected to grow through 2032 driven by replacement of legacy chemistries, rising service expectations (e.g., overnight supply and certified compostable lines), and incremental adoption in adjacent industrial applications. With a ~2.8% CAGR over the forecast, companies that invest now in resilient supply chains and compliant, demonstrably greener formulations will disproportionately capture the growth available.
VCI Film Market
Two structural observations emerge from the data and customer interviews we conducted: first, growth is demand-led but constrained by raw-material and regulatory shocks; second, premiumization — selling performance and environmental credentials rather than competing solely on price — is becoming the primary route to margin expansion.
VCI Film Market
Key industry dynamics shaping 2026 strategies
- Regulatory pressure: Emerging and existing regulations (including EU REACH-type restrictions and regional VOC controls) are narrowing the formula set usable in some markets. This raises compliance costs and favors suppliers with early investments in compliant chemistries and robust regulatory intelligence.
- Raw-material volatility: Sharp polyethylene price swings and petrochemical trade restrictions have materially increased cost uncertainty for film producers. Tactical procurement, hedging programs, and alternative resin strategies are now priorities for producers and converters.
- Sustainability as a product differentiator: Biodegradable, compostable, and recycled-content VCI films moved from niche to near-mainstream during 2024–2026, with several suppliers launching certified lines and rapid-delivery channels. Buyers increasingly require lifecycle evidence and third-party certifications as purchase prerequisites.
- Supply-chain frictions: Tariffs, export controls on specialty chemicals, and localized manufacturing mandates in key emerging markets mean that companies must actively design dual-source or regionalized supply footprints to avoid single-point disruptions.
Competitive landscape — what to watch
The sector is populated by a mix of specialist corrosion-solution providers, traditional packaging manufacturers, and distributors. Concentration metrics indicate a market where the top three and top five players together do not fully dominate, leaving space for mid-sized leaders and nimble innovators to expand.
- Established corrosion specialists: Firms with deep chemistry IP and established brands in industrial corrosion protection hold a defensive advantage. Their investments in bio-based or certified-compostable VCI chemistries are creating differentiated product lines that command premium pricing and reduce regulatory exposure.
- Packaging incumbents and converters: Large polymer converters are leveraging scale and distribution channels to bundle VCI films into broader protective-packaging portfolios. Their value proposition emphasizes logistics reliability and integrated packaging solutions rather than chemistry innovation alone.
- Distributors and service-led players: Rapid-delivery storefronts and value-added distributors that combine inventory guarantees with technical support have emerged as a decisive go-to-market model, especially for just-in-time industrial customers.
Recent strategic moves illustrate these trends: leaders have launched certified biodegradable product lines and expanded quick-ship e-commerce fulfillment to capture service-sensitive buyers. Trade-show activity and product rollouts in 2025–2026 underscore a bifurcation: firms are either doubling down on chemistry/IP or on logistics and channel economics.
What the PW VCI Film Market report contains (practical deliverables)
- Actionable demand model and forecast (2026–2032) built from bottom-up synthesis of production, end-market consumption profiles, and primary interviews.
- Regulatory impact matrix that maps specific chemical classes and formulation constraints against jurisdictional regimes — with a decision guide for compliant reformulation or market withdrawal.
- Supply-chain stress test with scenario-based recommendations: procurement playbooks, dual-sourcing templates, and resin-substitution pathways designed to mitigate polyethylene and specialty-chemical shocks.
- Commercial playbook for premiumization: product positioning templates, certification roadmaps, and pricing frameworks that preserve margin while meeting sustainability KPIs.
- Competitive benchmarking and M&A screen: profiles of incumbent leaders, distributor models, and prospective bolt-on targets — plus a valuation sensitivity checklist for deals predicated on proprietary chemistries or regional access.
- Executive-ready 90/180/365-day implementation plan focused on supply continuity, product compliance, go-to-market, and investment prioritization.
Strategic actions for 2026 — prioritized
- Immediate (0–90 days): Audit current VCI specifications against REACH/CARB and major Asian regulatory frameworks; establish a raw-material price contingency and short-term hedges; identify single-source risks in the finished goods pipeline.
- Near-term (90–180 days): Fast-track certification for sustainable VCI offerings if applicable; negotiate guaranteed-stock programs with suppliers who can provide overnight or quick-ship logistics; pilot dual-sourcing across at least two regions for critical SKUs.
- Medium-term (180–365 days): Decide on strategic positioning — build chemistry IP (R&D + licensing) or buy market access via M&A — based on your organization’s capability profile and the report’s M&A screen. Implement lifecycle-based pricing and commercial training to capture margin on green/technical attributes.
Implications for different corporate functions
- Procurement: Shift from lowest-cost buys to total-cost-of-ownership models that include compliance risk and logistics reliability.
- R&D / Product Management: Prioritize reformulations and third-party certification to preempt regulatory delisting and to command premium segments.
- Sales & Marketing: Educate customers on the value of certified VCI films (reduced warranty claims, regulatory alignment) and use service-level guarantees as a differentiator.
- M&A & Corporate Development: Target acquisitions that either add certified chemistries, regional manufacturing capacity, or e-commerce/quick-fulfillment capabilities rather than generic capacity.
Why PW Consulting
Our VCI Film Market study blends granular supply-side intelligence with buyer interviews and regulatory mapping, yielding operational recommendations rather than abstract forecasts. We intentionally preserve sensitive segmentation tables and detailed company-level share data in the full report to ensure clients access the complete dataset behind our conclusions — this summary is designed as a strategic “trailer” to prompt the operational conversations you need for 2026.
Next steps
For procurement templates, regulatory matrices, and the complete segmentation (regional, type, application) that underpin the market forecast and competitive screens, access the full VCI Film Market report. If you would like a tailored briefing — for example, a 60-minute workshop applying the supply-chain stress test to your SKU set — PW Consulting’s industry team is available for bespoke consulting engagements in Q3 2026.
For detailed analysis of this topic, please visit the official page: VCI Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com