

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Barium Sulfate Market Poised for 5.1% CAGR Through 2032

Barium Sulfate Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our comprehensive Barium Sulfate Market study (base year 2025). This briefing synthesizes the data-driven signals most likely to shape boardroom decisions in 2026. It demonstrates the analytical depth of the full report while preserving the detailed segment-level tables and proprietary scenarios that we reserve for subscribers. Use this briefing to orient strategy, prioritize information requests, and rapidly align investment, procurement, and R&D teams ahead of the next planning cycle.
Barium Sulfate Market
Why this market matters in 2026
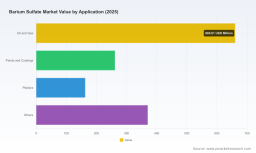
Barium sulfate sits at the intersection of traditional industrial demand (coatings, plastics, rubber, and industrial finishing) and higher-growth specialty uses (medical contrast agents, ultrafine pigments, and high-performance composites). After a period of volatility in the early 2020s, the global market reached approximately USD 1,455 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.1% through our 2026–2032 forecast window. Under our central scenario, market value approaches roughly USD 2,060 million by 2032.
Barium Sulfate Market
For executives, that trajectory signals two simultaneous imperatives: (1) protect margin in legacy, price-sensitive channels where commoditization pressures persist; and (2) accelerate moves into specialty, higher-margin applications where differentiation and technical service create defensible positions. Our full study quantifies addressable opportunities across these vectors and maps operational levers that can convert growth into profit.
Barium Sulfate Market
Market dynamics that will determine winners
- Input-cost shocks and pass-through dynamics. Raw-material and production cost inflation materially affected supplier economics through 2024–2025. The net effect has been a pronounced repricing of precipitated grades and a reconfiguration of supplier margins. In 2026, firms with integrated feedstock access or efficient precipitation technology retain superior cost flexibility—an advantage when customers contest price increases.
- Regulatory and sustainability constraints. Compliance requirements from major regulators (including recent mineral and registration guidance) are raising the bar on environmental controls—dust mitigation, process effluent management, and site remediation. Companies that pre-emptively adopt best-in-class environmental practices reduce compliance risk and open doors to sustainability-sensitive buyers.
- Trade policy and sourcing realignment. New tariff measures and trade frictions implemented in 2025 prompted a re-evaluation of sourcing strategies. Expect further reshoring, nearshoring, and multi-sourcing initiatives in 2026 as manufacturers hedge geopolitical risk and accelerate supply-chain resilience programs.
- Product and particle engineering as differentiators. Ultrafine, surface-modified, and specialty precipitated grades are becoming decisive for applications with performance-critical specifications—X-ray contrast media, high-end cosmetics, advanced coatings, and engineered plastics. Technical capability to control particle size distribution and surface chemistry is a primary barrier to entry in these niches.
Competitive landscape — positioning and strategic implications
The barium sulfate sector remains moderately fragmented, with a small number of established international players and a larger cohort of regional producers. Market concentration metrics indicate a competitive structure where top suppliers hold meaningful, but not dominant, shares—creating space for both scale plays and focused specialty strategies.
- Barium & Chemicals, Inc. (USA) — Strength: tailored high-purity compounds across industrial, medical, and specialty channels. Strategic implication: a clear platform for premiumization and custom solutions; ideal acquirer or partner for customers seeking specification-grade materials with traceability and supply assurance.
- Shaanxi Fuhua Chemical (China) — Strength: scale in precipitated and superfine grades for coatings and plastics. Strategic implication: price leadership in standard grades, but exposure to raw material swings means margin vulnerability unless complemented by specialty product lines.
- Sakai Chemical Industry (Japan) — Strength: ultrafine BARIFINE portfolio targeting pharmaceuticals, cosmetics, and engineered plastics. Strategic implication: technological differentiation that supports upstream collaboration with medical and cosmetics OEMs.
- Solvay S.A. (Belgium) — Strength: established Blanc Fixe precipitated grades and a global customer footprint. Strategic implication: ability to bundle performance attributes with global logistics capabilities—useful for multinational end-users.
- Sachtleben Chemie (Germany) — Strength: nano-fine specialty pigments and additives for high-performance coatings and personal care. Strategic implication: positioned to capture premium margins where regulatory and aesthetic performance intersect.
- Cimbar Performance Minerals (USA) — Strength: solution focus on automotive and marine coatings. Strategic implication: vertical alignment with finishing supply chains and capacity to co-develop formulations with OEMs.
Recent supplier-level actions—most notably coordinated price increases announced in early 2025 by major precipitated suppliers—illustrate how concentrated cost pressures can spark industry-wide repricing. Buyers and suppliers both need playbooks to navigate short-cycle price negotiation, contract renegotiation, and collaborative cost-reduction programs.
What our full report delivers (practical contents)
The PW Consulting study is built for operators and strategists who must act in 2026. It includes:
- Bottom-up market sizing and a seven-year forecast model (2026–2032) with scenario analysis.
- Cost-to-serve and margin benchmarks by technology pathway (precipitated vs. natural feedstocks) and by commercial model.
- Supply-chain mapping and resilience scoring, highlighting chokepoints and alternative sourcing pathways.
- Regulatory and environmental compliance playbook with investment-sizing guidance for emissions control, waste handling, and site restoration requirements.
- Detailed competitive profiles and decision matrices for M&A, JV, and alliance opportunities.
- Commercial playbooks: segmentation-driven pricing strategies, channel rationalization, and value-selling approaches for specialty grades.
- Operational improvement roadmap with CAPEX/OPEX trade-off analysis for precipitation technology, micronization, and product finishing.
Note: this preview intentionally omits the full segment-level tables, regional allocations, and docking of supplier-specific volume/price curves that comprise the proprietary core of the study. Those elements are available only in the full report and interactive model.
Strategic recommendations for 2026
- Advance product premiumization selectively. Prioritize R&D and sales focus on specialty and ultrafine grades where technical barriers create margin protection. Tie these efforts to co-development agreements with downstream customers (medical imaging, high-end coatings, cosmetics).
- Strengthen procurement resilience. Move from single-source short contracts to a layered sourcing strategy: strategic long-term agreements with a primary supplier, tactical spot coverage, and regional secondary suppliers for contingency.
- Hedge input-cost exposure. Develop pricing indexation clauses and cost-pass mechanisms in major contracts; where feasible, vertically integrate or secure feedstock alliances to stabilize raw-material access.
- Invest in environmental compliance as market entry cost. Treat dust control, effluent management, and land restoration as value-creation levers; buyers increasingly incorporate supplier sustainability scores into procurement decisions.
- Consider bolt-on M&A in specialty segments. Target acquisitions that add particle-engineering capability, registration dossiers for regulated applications, or direct customer relationships in medical and cosmetics channels.
- Deploy digital quality and traceability. Introduce batch-level QC data sharing and digital certificates to capture price premiums in regulated and quality-sensitive end markets.
Scenario thinking: three plausible 2026 pathways
- Base case (most likely). Demand growth continues at the mid-single-digit CAGR supported by specialty expansion; price normalization after 2025-led repricing; moderate consolidation among regional players.
- Upside case. Accelerated adoption of ultrafine grades in pharmaceuticals and high-performance coatings drives faster premiumization; larger players secure long-term offtakes and M&A accelerates scale advantages.
- Downside case. Prolonged raw-material inflation and new trade barriers suppress investment and lower-volume demand in commoditized applications, compressing margins across the value chain.
Closing — how to use this preview
This briefing frames the strategic questions every executive should be asking in 2026: Where should we place our bets between scale and specialization? How do we harden supply chains against policy and price shocks? What portfolio moves—organic or inorganic—deliver the best risk-adjusted returns?
For procurement leaders, the immediate priorities are contract redesign and contingency capacity mapping. For R&D and commercial leaders, the focus is on product differentiation and co-development. For corporate development teams, the opportunity set centers on bolt-on acquisitions that bring particle-engineering and regulated-market access.
To access the proprietary segmentation tables, supplier-level volume and price curves, regional demand matrices, and the interactive financial model that underpin these recommendations, please follow the link to our full report. PW Consulting’s dataset and scenario engine will enable you to stress-test specific actions and embed the findings directly into your 2026 planning processes.
For detailed analysis of this topic, please visit the official page: Barium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com