

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ship Plate Market to hit USD 266.2 Million by 2032, 3.1% CAGR

Ship Plate Market 2026: Strategic Imperatives for Materials, Supply Chains and Competitive Positioning
PW Consulting’s Ship Plate Market study (base year 2025; historical 2020–2025; forecast 2026–2032) is designed as a pragmatic decision-support tool for executives who must align materials strategy with fleet renewal, regulatory shifts, and supply-chain resilience in 2026. The market is mature and modestly expanding — our consolidated market model shows growth from the early‑2020s into 2025 and projects a steady trajectory through the forecast horizon at a compound annual growth rate of 3.1%. By 2026 the market crosses a new interim threshold on the way to our 2032 projection, reflecting a mix of cyclical shipbuilding demand, material substitution, and regulatory-driven product requirements.
Ship Plate Market
Why the Ship Plate Market Matters for 2026 Decisions
-
Strategic leverage in shipbuilding. Plate material selection drives vessel cost, weight, durability and lifecycle maintenance. Choices made today determine fuel efficiency, retrofit pathways and class approvals over decades.
Ship Plate Market -
Regulatory and decarbonization pressure. IMO rules, regional emissions programs and alternative-fuel ship designs are reshaping plate specifications — from high‑tensile steels enabling lighter hulls to specialized grades for low‑temperature or cryogenic service.
Ship Plate Market -
Supply‑chain risk and opportunity. The market is neither hyper‑concentrated nor atomistic. A moderate top‑tier share among global producers coexists with numerous regional suppliers, producing both sourcing flexibility and exposure to localized capacity shocks and trade policy shifts.
-
Commercial timing is critical. The market trajectory we model is not strictly linear; the interplay of shipyard orderbooks, raw‑material price swings and certification cycles creates inflection points where early mover advantage accrues to suppliers and integrated shipbuilders.
Data‑Driven Signals to Watch in 2026
-
Growth baseline and variability: Our base‑case projects a steady 3.1% CAGR through 2032, but year‑to‑year deviations occur as orderbooks and retrofit activity fluctuate — requiring rolling quarterly reassessments rather than static annual plans.
-
Market concentration: The top three and top five suppliers capture a meaningful but not dominant share of the market. This structure favors differentiated product plays (special grades, certified supply chains, service bundles) and targeted consolidation where scale matters.
-
Cost sensitivity: Plate value is exposed to upstream iron ore and energy costs, and to logistics bottlenecks. Procurement strategies that combine index‑linked contracts, strategic inventory and near‑term options outperform simple spot buying in stressed markets.
What PW Consulting’s Ship Plate Report Delivers (Practical Content)
-
Actionable forecasting model — scenario outputs for short, medium and long cycles with sensitivity to raw‑material costs, shipyard demand blends and regulatory shifts.
-
Decision playbooks — procurement templates (contract clauses, hedging approaches), CapEx timing guides for mill upgrades, and a supplier segmentation matrix keyed to quality, scale and proximity.
-
Supply‑chain mapping — end‑to‑end flows, choke‑point diagnostics and mitigation strategies for shipping, slabbing, finishing and certification throughput.
-
Technology and product roadmaps — evaluation of high‑tensile, quenched-and‑tempered, coated and specialty plate families, including adoption timelines tied to ship design trends and class society requirements.
-
Commercial intelligence — benchmarking scorecards for major suppliers, contract negotiation levers, and a prioritized list of partnership and M&A targets for integration or capability expansion.
-
Operational tools — total cost of ownership calculators, procurement scenario simulators, and a readiness checklist for achieving compliance across major class societies and regional authorities.
Competitive Landscape: Who Matters and Why
The ship plate industry balances global integrated steel majors with large regional producers. The major players profiled in our study illustrate distinct strategic postures that buyers and investors must map against their own needs.
-
Integrated global majors (e.g., ArcelorMittal) — advantage in breadth of grades, international logistics and technical depth (high‑tensile and quenched & tempered offerings). These players can support large, multicontinental shipbuilding programs and complex certification stacks.
-
Korean specialists (e.g., POSCO, Hyundai Steel) — proximity to high‑volume shipyards and strength in coated and high‑strength hot‑rolled plates. Their integration into regional supply networks provides lead‑time advantages on East Asian projects.
-
Japanese incumbents (e.g., Nippon Steel, JFE) — reputation for weldability, toughness and tight quality control. Their core customer base values predictable performance in demanding welding and fatigue scenarios.
-
Chinese and Taiwanese producers (e.g., Baosteel Group, China Steel Corporation) — scale and cost competitiveness, with rapid capability upgrades to meet international class approvals for export‑oriented shipyards.
-
Regional Western producers (e.g., Tata Steel’s European footprint, United States Steel) — differentiated by local approvals, integrated service offerings and responsiveness to regional regulatory regimes.
Across these company archetypes, our analysis highlights four competitive axes that determine supplier selection and negotiation strength: technical grade breadth (specialty steels), certification and class approvals, integrated logistics/service capabilities, and low‑carbon or circular steel credentials. Because the top few suppliers do not fully dominate the market, mid‑tier players retaining strong local relationships can remain highly influential — especially where lead times and on‑site support are decisive.
Strategic Recommendations for 2026 Decision‑Makers
-
Adopt a multi‑dimensional sourcing strategy. Mix long‑term offtake for core grades with flexible spot access for opportunistic buys. Lock in critical specialty‑grade volumes via multi‑year commitments with performance SLAs tied to certifications and delivery windows.
-
Prioritize certification and traceability. Ask suppliers for class‑specific approvals and digital mill certificates. Investing in traceability reduces retrofit and warranty risk while enabling premium pricing for low‑carbon product lines.
-
Use staged investment for capacity and R&D. Rather than large single‑stage capital outlays, phase investments in finishing, coating and specialty metallurgy aligned to validated shipbuilding pipeline milestones.
-
Build strategic partnerships with suppliers and shipyards. Co‑develop trial programs for lightweighting or corrosion mitigation that can be rapidly scaled if trial economics validate fleet‑level gains.
-
Stress‑test procurement against macro shocks. Incorporate raw‑material price scenarios and logistic disruption scenarios into 12–36 month purchasing plans; maintain strategic buffer inventory where justified by orderbook visibility.
-
Capitalize on sustainability differentiation. Suppliers investing in scrap usage, hydrogen‑based reduction trials, or certified low‑carbon steel will attract long‑term demand as charterers and financiers apply decarbonization screens.
Tactical 90‑Day Playbook (Priority Actions)
-
Validate existing contracts against our risk checklist: delivery clauses, indexation, force majeure and quality KPIs.
-
Initiate supplier scorecard pilots for three strategic grades — measure lead time, certification completeness and traceability.
-
Run a scenario sweep of your 2026 procurement budget using +/- 20% raw‑material swings to identify exposure and optimal hedge levels.
-
Engage two shortlisted suppliers in co‑development pilots focused on weight reduction or improved weldability tied to one upcoming hull design.
What We Deliberately Hold Back Here (and Why)
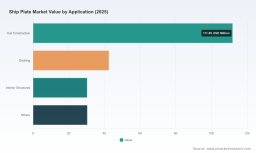
To respect the “trailer” principle — demonstrating depth while steering readers to the full research product — this overview omits granular region‑by‑region and application‑by‑application revenue splits, supplier revenue shares and detailed pricing curves. Those core segmentation datasets, along with downloadable models and supplier scorecards, are contained in the full PW Consulting Ship Plate Market report and interactive dashboards, where clients can run bespoke scenarios tied to their orderbooks and procurement constraints.
Conclusion — Positioning for Advantage in 2026
In 2026, the ship plate market presents an environment of managed growth, technical evolution and opportunity for differentiated suppliers and astute buyers. Success will come to organizations that combine disciplined procurement, targeted product development, and a strategic approach to partnerships and certification. PW Consulting’s Ship Plate Market study equips decision‑makers with the forecasting rigor, operational playbooks and competitive intelligence needed to capture that advantage — while our proprietary datasets and modeling tools enable the tactical specificity executives require to act with confidence.
For access to the full dataset, supplier revenue breakdowns, regional and application segmentation, and customizable scenario models that underpin these recommendations, download the complete report and accompanying toolset from the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Ship Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com