

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Inner Tubes Market Poised for 5.66% CAGR Through 2032

Inner Tubes Market: Strategic Imperatives for 2026 — Executive Introduction
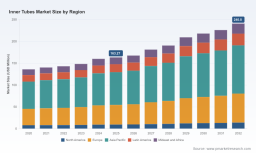
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present this executive introduction to our Inner Tubes Market study. Built on a 2025 base year and a detailed historical series covering 2020–2025, the report provides a forward-looking forecast through 2032. The market grew from approximately USD 136.0 Million in 2020 to USD 163.27 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.66% across the 2026–2032 forecast window, reaching an estimated USD 240.8 Million by 2032. All values in this summary are expressed in USD Million.
Inner Tubes Market
This introduction follows a “trailer” principle: it reveals the directional, strategic, and tactical insights necessary to inform 2026 corporate decisions while intentionally withholding the granular segment-level data that our full report provides. Think of this as the strategic map; the full dataset contains the coordinates.
Inner Tubes Market
Why this study matters for 2026 decision-makers
-
Timing decisions under secular change: The inner tubes market is neither static nor marginal. With a mid-single-digit CAGR projected to 2032, decisions made in 2026 about capacity, sourcing, and product mix will materially affect P&L and market positioning over the next development cycle.
Inner Tubes Market -
Balancing protection and growth: New product formats (e.g., TPU-based lightweight tubes) and an ongoing shift toward tubeless systems in some vehicle classes create both downside risk for commodity inner tubes and a premiumization opportunity for differentiated offerings.
-
Supply-chain sensitivity: Butyl rubber remains the primary raw material; producers and procurers must manage exposure to petrochemical price volatility and changing supplier geographies to protect margins and delivery reliability.
-
Regulatory and compliance risk: Automotive quality standards and localized enforcement actions mean that product traceability and testing are non-negotiable for businesses wishing to avoid recalls and reputational cost.
Key market dynamics shaping 2026
-
Raw material linkage to energy markets. Butyl rubber is the anchor feedstock for most inner tubes; its pricing and availability are tightly coupled to oil and natural gas market dynamics. Procurement strategies that incorporate price collars, diversification of suppliers across feedstock types, and back-to-back hedges will materially reduce margin volatility.
-
Standards and enforcement. ISO 2941 and other automotive collapse-strength testing protocols remain central to acceptance in automotive and commercial applications. Several markets have recently stepped up enforcement and returns for non-compliant motorcycle inner tubes — increasing the cost of quality failures and incentivizing early investment in test certification.
-
Labor and manufacturing continuity. Worker agreements and union activity in rubber and plastics facilities can re-shape near-term capacity availability. Recent multi-year contracts in North American production highlight the need for scenario planning around labor-led constraints.
-
Product technology divergence. Two parallel trends are in play: the ongoing introduction of tubeless systems in certain segments (notably passenger and some commercial applications) and the emergence of TPU and multi-layer performance inner tubes for premium cycling categories. The result is a bifurcation of demand into commodity replacement volumes and a smaller but faster-growing, higher-margin performance segment.
-
Channel and aftermarket dynamics. Aftermarket replacement remains an important revenue stream, but distribution models are evolving: e-commerce, aftermarket remanufacturing channels, and fleet management procurement for commercial vehicles all require customized go-to-market playbooks.
Segmentation and growth pockets — a selective preview
The market’s structural segmentation by product type, application, and region reveals divergent growth vectors. Butyl-based tubes continue to anchor global volumes due to their balance of performance and cost. Natural rubber plays a meaningful role where legacy vehicle fleets and specific regional preferences sustain demand. Separately, specialty polymers (e.g., TPU) are carving out performance niches in cycling and premium automotive restoration.
On applications, replacement demand across passenger and commercial vehicles remains foundational, while two-wheeler and bicycle markets show differentiated dynamics driven by urban mobility trends, electrification of light vehicles, and recreational cycling growth. Geographically, demand momentum is not uniform: some regions present higher baseline volumes and faster fleet expansion, while others prioritize premium, certified products—creating distinct strategic plays for manufacturers and distributors.
We intentionally restrict detailed segment and regional percentages in this introduction. The full report contains the granular splits, multi-scenario forecasts, and indexable demand curves you will need to construct region- and application-specific business cases.
Competitive landscape — who moves the market
The competitive field blends legacy global tire and tube specialists, regional low-cost producers, and technology-led premium entrants. The market structure is fragmented: the leading global players together represent roughly a quarter of market volume, which leaves substantial room for regional champions and vertical specialists.
-
Bridgestone America’s Tube Business (USA/Canada): The sole inner tube manufacturer in North America, focusing on premium natural rubber and diversified industrial and trailer applications. Its presence underlines the strategic value of a domestic manufacturing footprint for buyers prioritizing supply resilience and certification.
-
Nexen Tire (South Korea): A large-scale inner tube producer with strengths in large-vehicle applications (buses, heavy trucks, tractors) and deep export channels. Its scale and feedstock integration provide lessons for firms targeting heavy-duty and fleet OEM segments.
-
Qingdao Dayangzhou Rubber & Plastic (China): Representative of the cost-competitive OEM supply base—competitive on price, flexible on OEM terms, and relevant for private-label strategies in mature aftermarket channels.
-
Shanxi Huajun Tire (China): A full-range producer active in global trade shows, signaling an export ambition and rapid product breadth expansion. Recent trade show participation (April 2026 Canton Fair) is a sign of go-to-market push beyond domestic channels.
-
Continental AG & Michelin: These premium technology players are advancing alternative inner tube concepts—lightweight TPU variants and airtight Airstop solutions—illustrating how innovation can command price premiums and lock in high-spec OEM partnerships.
-
Kenda Tire: A focused supplier to bicycle and e-bike channels where tailor-made tubes and aftermarket service propositions matter more than commodity price.
Strategic playbook for 2026 — what to prioritize now
-
Secure raw materials through layered procurement: mix long-term supply agreements for butyl feedstock with shorter-term hedges tied to energy indices. Consider selective vertical integration or strategic JV with petrochemical suppliers if scale economics permit.
-
Invest in compliance and traceability: certify to ISO 2941 and local standards, and embed batch-level traceability to reduce recall risk and enable premium OEM certifications.
-
Differentiate by application: pursue a two-track product strategy—maintain cost leadership in replacement volumes while selectively investing in TPU and specialized inner tubes for premium bicycle, MTB, and classic vehicle markets.
-
Rethink footprint and logistics: for markets with enforcement risk and speed-to-market requirements, consider regional production or localized contract manufacturing to reduce lead times and compliance complexity.
-
Prioritize aftermarket digitization: invest in e-commerce channels, parts-finder tools, and fleet-services platforms to capture recurring replacement revenue and data for aftermarket forecasting.
-
Evaluate M&A as capability play, not just scale: targets should add product technology, regional channel access, or raw-material linkages. Given market fragmentation, bolt-on acquisitions can accelerate entry into higher-margin or better-protected segments.
What PW Consulting’s full report delivers (practical, implementable modules)
-
Complete historic and forecast demand model (2020–2032) with interactive scenario toggles for macro variables and raw-material price shock sensitivity.
-
Segmented forecasts by product type, application, and region with indexable growth drivers and conversion curves suitable for business planning and CapEx modeling.
-
Supplier and competitor dossiers: capability maps, pricing posture, certification status, and channel coverage for the major manufacturers and 50+ regional players.
-
Regulatory and standards playbook: pre-built checklists for ISO 2941 and common market enforcement mechanisms, plus a recall-risk mitigation framework.
-
Procurement and hedging tactics: recommended contract language, sample cost-variance clauses, and sourcing scorecards.
-
Go-to-market & pricing playbooks for OEM, fleet, and aftermarket channels plus a prioritized investment roadmap for R&D and product development.
-
Shortlisted M&A candidates and partnership archetypes tailored to five strategic outcomes (capacity, tech, channel, vertical integration, geographic access).
Everything above is calibrated to equip executives, heads of product, procurement leads, and corporate development teams to make defensible 2026 decisions. The full PW Consulting Inner Tubes Market report contains the granular segmentation tables, regional shares, application-level growth curves, and unit economics necessary to run internal investment cases and negotiate supplier contracts.
To move from strategic intent to executable plans, access the complete dataset and model. Our analysts are available to run custom scenarios calibrated to your cost structure, target regions, and product strategy.
For detailed analysis of this topic, please visit the official page: Inner Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com