

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mercaptoacetic Acid Market to Reach USD 344.8M by 2032 at 5.5% CAGR

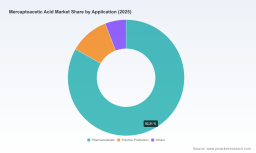
Mercaptoacetic Acid (Thioglycolic Acid): A 2026 Strategic Preview for Executive Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present an executive preview of our Mercaptoacetic Acid market research — a synthesis designed to inform capital allocation, commercial strategy, and risk mitigation choices through 2026 and beyond. This preview highlights the macro trajectory, competitive texture, and operational levers that will matter most for manufacturers, buyers, and investors during the coming planning cycle. For confidentiality and to preserve commercial value, detailed regional and application-level splits, the full price decks, and granular supplier financials are reserved for the complete report.
Mercaptoacetic Acid Market
Why this study matters for 2026
- Actionable growth context: The market has expanded steadily from 2020 to 2025 (from an industry base in the low‑hundreds of USD Million) and, with a mid‑single digit CAGR of roughly 5.5% across 2026–2032, is expected to reach the mid‑hundreds by the end of our forecast period. That trajectory shifts the calculus for capacity investments, margin expectations, and product prioritization.
- Fragmented supplier landscape: Concentration metrics show the sector is not tightly consolidated; the top-three and top-five supplier shares are modest, implying that supply competition, contract leverage, and local niche players will remain influential.
- Regulation and product risk: Emerging regulatory constraints and cosmetics governance are already shaping permissible formulations and route‑to‑market strategies, raising compliance costs for certain downstream product forms.
- Procurement and supply risk: Feedstock exposure (derived from petrochemical streams) creates cost volatility; purchasing and hedging strategies for 2026 must be more sophisticated than spot purchasing alone.
Market dynamics that will determine winners in 2026
- Demand drivers: High‑purity applications (cosmetics, pharmaceutical intermediates, professional salon products) continue to drive value growth even as bulk industrial uses sustain base volumes. This creates a two‑track market where premiumization and compliance differentiate margin pools.
- Upstream feedstock volatility: Key synthesis inputs are linked to broader petroleum cycles. That linkage means short‑term margins are sensitive to feedstock swings and that integrated players or those with flexible sourcing strategies will enjoy an edge.
- Regulatory tightening: Authorities in multiple jurisdictions have increased scrutiny of thioglycolic acid derivatives and esters; enforcement patterns and concentration limits in cosmetic regulation are shifting formulation thresholds and product labelling obligations. Manufacturers with robust regulatory affairs functions and reformulation capabilities will convert this pressure into competitive advantage.
- Logistics and packaging: Improvements in industrial packaging and transportation — a relatively low‑visibility optimization — can materially lower total delivered cost and open export opportunities for mid‑sized producers.
Competitive landscape — strategic read on key players
The market mix is composed of global specialty chemical houses, regional specialists, and a set of cost‑competitive Asian producers. Our engagement identified several archetypes and recent strategic moves:
Mercaptoacetic Acid Market
- Global specialty leaders (e.g., Arkema): Investing in capacity expansion for high‑margin cosmetic and healthcare grades. Their strategy centers on brand credibility, regulatory compliance, and integrated specialty portfolios to capture premium pricing.
- European niche specialists (e.g., Bruno Bock): Upgrading purification and quality control to serve pharmaceutical and high‑end cosmetic segments. These players compete on technical differentiation and certification rather than scale.
- Japanese incumbents (e.g., Daicel): Leveraging process IP and formulation expertise to win professional salon and pharmaceutical channels by emphasising worker safety and product performance.
- Regional cost players (e.g., select Chinese manufacturers): Focused on competitive pricing and supply responsiveness to capture industrial and mass‑market cosmetic demand in Asia and export markets.
- North American suppliers (e.g., Swan Chemical): Strong local logistics and service models that make them preferred partners for leather treatment and regional manufacturing supply chains.
Recent corporate moves we tracked — capacity expansions, purification upgrades, formulation launches, and packaging/transport improvements — are consistent with a market shifting toward higher quality, more regulated end‑uses. Buyers and investors should interpret these signals as a re‑rating of premium, compliant capacity versus commodity production.
Mercaptoacetic Acid Market
What the full PW Consulting report delivers (practical, operational components)
- Robust market model: Historical base (2020–2025), 2026 baseline scenario, and three alternate scenarios through 2032. Includes sensitivity runs for feedstock price shocks, regulatory tightening, and accelerated premiumization.
- Commercial playbooks: Go‑to‑market templates for high‑purity vs industrial grades, recommended distributor agreements, sample quality & testing specifications, and margin improvement levers.
- Procurement toolkit: Supplier scorecards, RFP templates, contract clauses for price adjustment and force majeure, and guidance on hedging strategies for upstream precursors.
- Capex and capacity planning tools: Decision trees for greenfield vs tolling, ROI calculators under multiple price regimes, and a list of operational KPIs to monitor post‑investment.
- Regulatory impact matrix: Jurisdictional compliance requirements, reformulation thresholds, labelling implications, and recommended product portfolio adjustments to mitigate market access risk.
- Competitive profiles and M&A signal set: Executive profiles of incumbent suppliers, strategic positioning maps, and a prioritised shortlist of acquisition and partnership targets with rationale (financials and contactable diligence leads provided in the full dossier).
- Risk register and mitigation playbook: From raw materials and logistics to reputational risks tied to cosmetic safety incidents — with contingency plans and insurance considerations.
How to interpret the withheld details (the “trailer” principle)
This preview deliberately surfaces strategic conclusions and the decision‑relevant implications of the data without publishing detailed regional or application splits, price decks, or supplier financial minutiae. Those components retain the highest transactional value and are available in the full report and modelling pack. If you are evaluating investment, procurement renegotiation, product line rationalization, or M&A activity in 2026, the granular tables and scenario models in the full report will materially shorten your decision cycle and reduce execution risk.
Concrete recommendations for 2026 planning
- Prioritise high‑purity capability where you can certify supply: Given the steady migration of demand toward regulated, higher‑value end uses, plant upgrades or JV arrangements to secure validated, pharma/cosmetics‑grade production will pay off in margin resilience.
- Shift procurement from spot to hybrid contracts: Combine indexed short‑term purchases with longer term fixed‑volume agreements and optionality to manage feedstock volatility tied to petrochemical cycles.
- Invest in regulatory engineering: Move reformulation and safety testing upstream in the product development cycle to avoid costly post‑launch withdrawals and to accelerate time‑to‑market in regulated geographies.
- Pursue tactical partnerships and tolling: If capex budgets are constrained, secure capacity via tolling agreements with regional players who have packaging/logistics advantages and can deliver local market access.
- Monitor niche consolidation opportunities: With concentration metrics indicating a fragmented market, there are selective bolt‑on targets that can be acquired to rapidly add compliant capacity or expand geographic reach at attractive multiples.
Closing perspective
For executives making 2026 plans, mercaptoacetic acid is no longer a simple commodity story. Premiumisation, regulatory pressure, and feedstock-linked volatility are reshaping the economics. Our analysis — grounded in a transparent base year (2025), five‑year historical context, and a 2026‑2032 forecast horizon — provides the strategic context and the practical tools you need to act. To move from insight to execution, access to the full dataset, supplier dossiers, price decks, and the operational playbooks contained in PW Consulting’s full market report will be indispensable.
Contact PW Consulting to obtain the complete Mercaptoacetic Acid Market Report and the accompanying modelling pack to support procurement negotiations, capex approval, or M&A diligence in 2026.
For detailed analysis of this topic, please visit the official page: Mercaptoacetic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com