

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electrically Conductive Textiles Set to Expand at 10.5% CAGR to 2032 — PW Consulting Insight

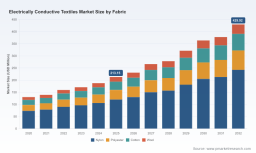
Electrically Conductive Textiles Market — Strategic Outlook for 2026
As companies position for growth in 2026, PW Consulting’s Electrically Conductive Textiles Market research provides a timely, decision-ready intelligence package. Anchored to a 2025 base year and projecting across 2026–2032, the study traces an industry that has more than doubled in scale since 2020 and is forecast to continue robust expansion at a compound annual growth rate (CAGR) of 10.5%. Measured in USD Million, the market rose from approximately 130.5 in 2020 to 213.15 in 2025 and is expected to approach 430 by 2032 — a trajectory that signals both opportunity and disruptive risk for material suppliers, textile integrators, OEMs, and end-market investors.
Electrically Conductive Textiles Market
Why this research matters for 2026 decision-makers
-
Timing and scale: The 10.5% CAGR and the 2020–2032 time series give leaders a quantitative frame for capital allocation, product roadmaps, and M&A horizons. The growth path is material enough to justify dedicated business units and R&D investment for many incumbent textile and materials companies.
Electrically Conductive Textiles Market -
Application diversity: Electrically conductive textiles are moving beyond niche ESD and EMI shielding uses toward integrated sensing, wearable health, defense systems, and consumer electronics interfaces. That broadening demand base requires firms to adopt modular product strategies and multi-channel commercial models.
Electrically Conductive Textiles Market -
Supply-chain and raw-material volatility: The market’s economics are increasingly sensitive to precious- and base-metal dynamics. In 2025, silver prices rose sharply and production value saw a significant uplift versus 2024; contemporaneously, copper was formally designated a critical mineral. These resource shifts materially impact costing, supplier selection, and strategic hedging policies for conductive coatings and metallized yarns.
-
Regulatory and testing inflection points: New standards and regulatory expectations — including a 2025 EN IEC test procedure that measures sheet resistance after abrasion — raise the bar for product qualification. Parallel requirements under REACH, RoHS and other compliance regimes, and emerging EU rules demanding low‑carbon coatings and energy‑efficient synthesis, change both product design and capital expenditure decisions.
What the PW Consulting report delivers (practical, actionable components)
-
Dynamic market model: A downloadable, user-configurable market sizing and forecast model (2020–2032) with sensitivity toggles for commodity cost shocks, adoption curves by application archetype, and alternative technology diffusion scenarios.
-
Segmentation and use-case playbooks: Product-by-product and fabric-by-fabric decision guides that translate technical attributes into go-to-market tactics for defense, healthcare, sports/fitness, and consumer electronics customers. (Note: granular regional and subsegment figures are available in the full report.)
-
Supply‑chain risk matrix: Raw material exposure dashboards, supplier concentration heat maps, and recommended forward‑buy/hedge strategies to mitigate silver, copper, and specialty polymer price swings.
-
Regulatory compliance checklist: Cross-referenced requirements (REACH, RoHS, ISO family) plus interpretation of EN IEC 63203‑201‑4:2025 and its commercial implications for abrasion performance testing and warranty structures.
-
Technology and cost benchmarking: Comparative CAPEX/OPEX profiles for metallization, conductive coatings, and conductive-fiber spinning routes, paired with unit-cost breakouts and scale-up thresholds.
-
Commercial playbooks: Pricing corridors, channel design, OEM procurement templates, and sample contract language for performance and sustainability warranties.
-
M&A and partnership roadmap: Targets and valuation heuristics based on product capability, scale, and strategic fit — optimized for buyers seeking rapid vertical integration or complementary tech licenses.
-
Scenario planning: Three alternative industry pathways through 2032 (baseline growth, commodity-shock inflation, accelerated substitution to non‑precious conductive chemistries) with decision triggers for each.
Competitive landscape — strategic profiles and implications
The competitive field blends specialized fabric metallizers, polymer coating innovators, traditional textile manufacturers, and diversified materials players. Market concentration is modest (the top-three and top-five players together hold a minority share), which creates runway for both consolidation and regional champions.
-
Eeonyx Corporation — A U.S.-based industrial producer of conductive polymer coatings. Strengths: scalable coating capability for nonwovens and staple fibers, rapid formulation cycles. Strategic implication: Attractive partner for firms seeking to replace metal-based chemistries and to reduce exposure to precious-metal price swings.
-
Laird Performance Materials — Provider of metallized and conductive fabrics for EMI shielding and smart textiles. Strengths: deep electronics industry relationships and metallization know‑how. Strategic implication: Best positioned to capture OEMs requiring integrated EMI and thermal management solutions; potential acquirer for textile specialists targeting electronics sectors.
-
Herculite Products Inc. — Niche ESD and healthcare fabrics. Strengths: regulatory approvals and healthcare channel access. Strategic implication: A credible supplier to hospitals and medical device OEMs where traceability and compliance matter.
-
Swift Textile Metalizing — Longstanding metallizer with aerospace and defense pedigree. Strengths: mission‑critical certifications and metallization process control. Strategic implication: Defense-focused suppliers should evaluate Swift for co-development of hardened EMI solutions.
-
Seiren Co., Toray, Bekaert, Statex — Established international players offering woven/non‑woven conductive substrates and metallic yarns. Strengths: broad manufacturing footprints, R&D pipelines, and channel breadth. Strategic implication: These firms will be key to global scale-up, enabling customers to source compliant, low-carbon options across regions.
-
Parker Hannifin, Holland Shielding, V Technical Textiles — Systems integrators and specialty fabricators focusing on gaskets, tapes, and engineered shielding solutions. Strengths: systems-level design and aftermarket support. Strategic implication: Incremental revenue opportunities exist in post-sale services and integrated product suites.
Key dynamics that will shape competitive advantage in 2026
-
Raw‑material strategy: Firms that proactively diversify conductive chemistries (e.g., carbon-based coatings, stainless‑steel fibers) and secure supply contracts for key metals will preserve margin and continuity in the face of metal-price volatility.
-
Testing and durability: The adoption of abrasion-resistance sheet-resistance testing (EN IEC 63203‑201‑4:2025) will shift buyer preference toward products that can demonstrate sustained electrical performance under lifecycle stress — creating a technical moat for manufacturers with validated abrasion-resistant coatings and reinforced constructions.
-
Sustainability and regulation: EU demands for low-carbon coatings and more energy‑efficient synthesis are set to reprice product portfolios. Early movers that optimize process energy intensity and disclose lifecycle emissions will gain preferential access to large OEMs and public tenders.
-
Fragmentation and consolidation: With a modest concentration profile, strategic M&A or alliance plays can rapidly scale capabilities and geographic reach. Buyers should prioritize targets that add either unique chemistries or regulated‑channel access (e.g., medical, defense).
Recommended executive actions for 2026
-
Execute a raw‑material hedging and substitution strategy: Establish multi-supplier contracts for silver and copper exposures, and accelerate R&D proofs for precious‑metal reduction or replacement where feasible.
-
Invest in abrasion- and lifecycle-testing facilities: Bring EN IEC 63203‑201‑4:2025–aligned test capability in-house or secure certified partners to shorten qualification timelines with OEMs.
-
Pursue selective vertical integration: Consider acquisition or JV with coating formulators or metallizing capacity to control unit costs and guarantee supply for key customers.
-
Embed sustainability into product specs: Re-engineer formulations and process energy use in anticipation of EU low‑carbon coating rules; use lifecycle claims as a commercial differentiator.
-
Adopt scenario-based commercial plans: Prepare three GTM variants — premium regulated markets (defense, medical), high-volume consumer channels, and industrial/shielding — each with tailored pricing, warranty, and service models.
How to use this research
PW Consulting’s report is a practical toolkit for corporate strategy, product management, investor due diligence, and M&A teams. Use the included market model to stress-test capital investments, the regulatory map to prioritize certification spend, and the supplier-risk matrix to inform procurement strategy. For those preparing board materials, the report’s scenario outputs translate market growth and commodity risk into actionable capital and partnership timelines.
Next steps — get the complete intelligence
This briefing surfaces the strategic contours of a market growing at a 10.5% CAGR from a 2025 base and projecting to substantive scale by 2032. For granular, source-level segmentation (regional splits, application and fabric-level figures), downloadable financial models, and our full set of supplier profiles and valuation heuristics, please consult the full report on our website. The complete package contains the detailed data and proprietary tools you need to convert the outlook into competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Electrically Conductive Textiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com