

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: BaaS market at USD 1,850 Million in 2025, poised for 8.25% CAGR

Mobile Backend as a Service (BaaS) 2026: Strategic Imperatives for Enterprise Leaders
As enterprises finalize technology roadmaps for 2026 and beyond, understanding the structural trajectory of Mobile Backend as a Service (BaaS) is no longer optional. PW Consulting’s new market study—rooted in a 2020–2025 historical baseline and a 2026–2032 forecast horizon—shows the global BaaS market at USD 1,850 Million in the 2025 base year, growing at a compound annual growth rate (CAGR) of 8.25%. By the end of our forecast window, the market is projected to be materially larger. This research is designed to translate those macro trends into practical decisions for CTOs, product leaders, and procurement heads who must balance speed-to-market, regulatory resilience, and total cost of ownership (TCO).
Mobile Backend As A Service (BaaS) Market
Why 2026 Is a Pivotal Year
Three forces converge to make 2026 a tipping point for BaaS adoption: ubiquitous mobile-first application demand, rapid IoT monetization imperatives, and a renewal of vendor product innovation (both from hyperscalers and open-source challengers). These dynamics are visible in the underlying numbers: after steady expansion through the first half of the decade, the market acceleration we model aligns with enterprise migrations from legacy APIs to managed, scalable backends that prioritize realtime, offline-first, and event-driven capabilities. Analysts and buyers should treat 2026 as the year to move from exploratory pilots to enterprise-grade rollouts.
Mobile Backend As A Service (BaaS) Market
Report Scope and Practical Value
PW Consulting’s study is structured to be immediately actionable. It blends quantitative market sizing and forecast modelling with qualitative playbooks and procurement-ready artifacts. Key deliverables include:
Mobile Backend As A Service (BaaS) Market
- Market sizing and long-form trend narratives covering historical (2020–2025) and forecast (2026–2032) periods, with scenario-based sensitivity analysis for macroeconomic and regulatory variance.
- Competitive vendor mapping and strengths/weaknesses analysis for leading providers across managed and open-source BaaS models.
- Use-case ROI calculators and migration TCO models for greenfield mobile apps, IoT platforms, and real-time consumer services.
- Enterprise architecture blueprints showing recommended hybrid and multi-provider topologies to reduce vendor lock-in while preserving developer velocity.
- Vendor selection matrices, procurement negotiation playbooks, and legal/compliance checklists targeting data sovereignty, security posture, and SLA enforcement.
Market Structure and Concentration
Our benchmarking indicates a market with meaningful leader influence but substantial room for mid-market and open-source propositions. Measured concentration metrics show that the top three vendors account for a significant minority of the market, while the top five capture a clear majority — a structure that supports both consolidation and opportunities for specialist players who offer differentiated functionality (e.g., realtime, edge sync, developer ergonomics). This competitive topology favors strategic partnerships for enterprises seeking both scale and innovation.
Competitive Dynamics: Hyperscalers vs. Open-Source and Managed Specialists
The vendor landscape is evolving into a multi-modal ecosystem. Hyperscalers bring global reach, deep platform integrations, and mature compliance tooling. Open-source projects and managed specialists compete on developer experience, portability, and pricing transparency. Notable incumbents and challengers profiled in our study include established hyperscalers and rapidly maturing open-source options:
- Google (Firebase) — a full-featured, mobile-optimized managed stack emphasizing realtime databases, authentication, cloud functions, and integrated analytics.
- Amazon Web Services (Amplify) — full-stack tools integrating authentication, storage, APIs, and hosting for web and mobile workloads across AWS infrastructure.
- Microsoft Azure Mobile Apps — enterprise-focused mobile backend services with native integration to Microsoft’s broader cloud and identity offerings.
- Oracle — positioning BaaS features inside a broader enterprise integration and data management portfolio.
- Supabase, Appwrite, Back4app — open-source and managed players emphasizing developer ergonomics, Postgres foundations, realtime primitives, and lower-cost migration pathways.
Recent product announcements underscore the intensity of innovation. For example, open-source vendors have introduced developer-centric features such as Git deployment triggers and realtime presence APIs, while other projects are integrating with large language model platforms and exploring novel Postgres operating-system concepts. These product moves materially change vendor differentiation and should influence shortlists for proof-of-concept (PoC) evaluations this year.
Industry and Regulatory Noise That Matters
Although ostensibly outside the BaaS category, regulatory and infrastructure developments in adjacent sectors have strategic implications for BaaS suppliers and buyers. Grid market reforms, renewable integration, and region-specific energy policy changes are driving demand for resilient IoT telemetry platforms and low-latency edge processing—both of which map directly to BaaS requirements for state synchronization, offline-first resilience, and predictable SLAs. Enterprises building energy, logistics, or industrial IoT solutions must therefore account for cross-domain regulatory signals when sizing backend resilience and data residency capabilities.
How Enterprises Should Respond in 2026
We recommend a three-horizon approach for enterprise leaders:
- Immediate (0–6 months): Run targeted PoCs against 2–3 vendors representing different categories (hyperscaler, open-source managed, specialist). Use standardized test harnesses included in our report to quantify latency, cold-start behavior, and developer onboarding time.
- Near-term (6–18 months): Define an enterprise BaaS policy: acceptable vendor categories, data residency requirements, encryption-in-flight/at-rest standards, and service-level thresholds. Leverage the procurement playbooks in the report to negotiate flexible term sheets and exit clauses that minimize migration risk.
- Strategic (18–36 months): Execute a staged migration plan for priority apps, design a hybrid topology combining hyperscaler scale with open-source portability for critical workloads, and instrument continuous cost-performance monitoring to capture value as traffic scales.
Risk Considerations
Three categories of risk warrant executive attention:
- Vendor Lock-in and Data Portability: Rapid developer productivity can obscure long-term costs of migration. We provide a technical checklist and API abstraction patterns to reduce switching friction.
- Regulatory and Geopolitical Constraints: Data residency and cross-border data transfer rules continue to evolve and can affect architecture decisions for global deployments.
- Operational Resilience: The increasing use of realtime features and edge processing raises requirements for distributed consistency models and incident response playbooks.
What’s in the Full PW Consulting Report
To preserve the strategic value of our research while providing immediately useful guidance, the full report offers:
- Complete market model spreadsheets with historical series (2020–2025) and annual forecasts (2026–2032), sensitivity scenarios, and an assumptions workbook for financial modeling.
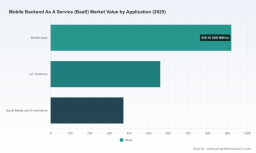
- Detailed segmentation analysis across services, applications, and regions, including revenue estimates and growth drivers for each segment (note: segmentation tables are available in the full report).
- Vendor scorecards that combine product feature sets, go-to-market positioning, partner ecosystems, and pricing signals; an appendix includes vendor contact mappings and integration guides.
- Practical artifacts: migration runbooks, cost estimation templates (TCO), security and compliance checklists, and a suggested RFP template tailored for enterprise BaaS procurements.
Takeaway: Position for Velocity and Resilience
The BaaS market is no longer a niche developer convenience — it is a foundational platform decision with direct business impact on time-to-market, operating cost, and cross-border compliance. With a 2025 market size of USD 1,850 Million and a steady CAGR of 8.25% through our forecast window, enterprises that move decisively in 2026 will capture outsized advantages: faster product cycles, lower incremental costs for scale, and better ability to monetize real-time and IoT-driven services.
PW Consulting’s market study provides the empirical foundation and playbooks to convert that strategic imperative into executable programs. For procurement-ready templates, full segmentation breakdowns, and vendor scorecards, access the complete report and dataset on our website.
For detailed analysis of this topic, please visit the official page: Mobile Backend As A Service (BaaS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com