

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Auto Dealer Software Market to Reach USD 309.2M by 2032 at 7.8% CAGR

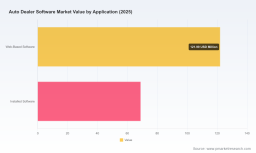
Auto Dealer Software Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest industry briefing frames the Auto Dealer Software market as a maturing yet dynamic arena where software economics, AI-enabled automation, and regulatory pressure converge to reshape dealer operations and vendor economics. Anchored on a robust macro model (historical 2020–2025, base year 2025; forecast period 2026–2032), our analysis shows the total market expanding from USD 143.5 million in 2020 to USD 190.8 million in 2025 and projecting to reach USD 309.2 million by 2032 — an implied compound annual growth rate (CAGR) of 7.8% across the forecast window. For executives planning resource allocation, M&A, or product-roadmap pivots in 2026, this report translates those headline numbers into concrete strategic choices.
Auto Dealer Software Market
Why this briefing matters for 2026 strategy
- Time-sensitive decisions: 2026 will be the first full planning cycle after several major platform and regulatory shifts; the window to secure advantageous partnerships, lock-in EV/connected car integrations, and optimize pricing models is limited.
- Macro tailwinds with concentrated competitive dynamics: growth is steady and predictable, yet market share remains meaningfully concentrated among a handful of legacy and cloud-native providers — a structure that raises both competitive risk and consolidation opportunity.
- Operational impact: the productivity uplift from modern DMS and AI can reduce specialized labor needs and materially change dealership cost profiles — a direct lever for vendor positioning and dealer ROI messaging.
Market trajectory: what the numbers conceal (and reveal)
The headline CAGR and top-line forecasts underscore two simultaneous realities: first, sustained adoption of dealer-focused software remains the dominant vector driving revenue growth; second, the nature of that growth is shifting — from pure DMS seat licensing toward cloud services, data platforms, AI-enabled workflows, and integration monetization. In practical terms, vendors that convert transactional revenue into recurring services and platform fees capture higher lifetime value and command premium multiples.
Auto Dealer Software Market
However, beneath the aggregate expansion are lifecycle and margin pressures: rapid R&D investments for AI, higher cybersecurity and compliance expenditures, and rising API licensing costs from lenders and OEMs compress near-term profitability for providers that fail to scale integrations efficiently. Our modeling shows that vendors who front-load investments into secure, multi-tenant cloud architectures while preserving low-friction migration incentives for legacy customers realize the best trade-off between growth and margin over the 2026–2032 horizon.
Auto Dealer Software Market
Competitive landscape — strategic implications for buyers and investors
The ecosystem today is anchored by established DMS incumbents and several agile cloud-native challengers. Leading vendors have recently accelerated product and platform moves: one global DMS provider launched a unified Customer Data Platform in January 2026 and followed with a Foundations Suite offering to simplify migration for renewing customers; another operator expanded AI-powered fraud detection and driver’s license validation capabilities in early 2026; and important regional players continue to refresh leadership and go-to-market strategies. These developments are not isolated — they reflect a broader industry pivot towards data unification, digital retailing, and automated F&I workflow optimization.
For buyers, that means vendor selection is no longer only about core feature parity. The critical evaluation axes in 2026 should include:
- Data architecture maturity — ability to unify CRM, transaction, and third-party data in real time while minimizing exposure from legacy ETL chains.
- Security and compliance posture — demonstrable SOC 2 (or equivalent) controls, breach recovery playbooks, and insurance/third-party attestations following sector-wide incidents.
- Integration economics — transparent API licensing, partner certification programs, and predictable roadmap commitments for OEM and lender integrations.
- Automation ROI — empirically validated reductions in manual F&I and data-entry time, and achievable productivity thresholds for dealer staff.
Consolidation, concentration and what it means
The market remains concentrated; the top-tier players control a meaningful share of industry revenue, which creates both defensive advantages for incumbents and entry opportunities for well-capitalized challengers. Acquirers should be systematic: bolt-on targets that add vertical data assets (e.g., valuation engines, digital contracting flows) or expand recurring monetizable services deliver faster payback than platform-only tuck-ins. Conversely, strategic buyers should plan integration budgets aggressively — the economics of harmonizing data, licensing, and multi-vendor contracts can erode expected synergies if underestimated.
Regulatory and risk landscape — 2026 priorities
Regulation and cybersecurity have moved from back-office compliance items to front-page risk factors. The sector’s reaction to a high-profile ransomware event in mid-2024 accelerated adoption of SOC 2-compliant hosting and pushed AI-driven fraud controls into standard feature sets. As a result:
- Vendors and dealer groups must treat cybersecurity and data privacy as a strategic capability, not a checkbox. Expect higher annual compliance expenditures across the provider base and higher insurance and legal costs for non-compliant players.
- Cloud-native platforms still need continuous investment to keep pace with data-protection mandates across different jurisdictions; this dynamic favors vendors with centralized security practices and scalable incident response teams.
- API licensing and third-party connector economics have become a material line item. Organizations must model licensing impacts in three- to five-year TCO analyses rather than assuming one-time integration costs.
Operational levers — how dealers and vendors win
Operational winners in 2026 will be those who translate product capabilities into measurable dealer outcomes. Key levers include:
- Automation of F&I and service workflows to reduce manual touchpoints and shrink time-to-close.
- Adoption of unified customer data platforms to increase lead conversion through real-time personalization and lifecycle marketing.
- Flexible migration paths and commercial incentives to move legacy installed bases to cloud platforms without high churn risk.
- Service delivery and support excellence — demonstrated by predictable upgrade paths, low-friction integrations, and strong NPS among dealers.
Strategic recommendations for 2026
- For dealers: prioritize vendors that can demonstrate secure multi-source data unification and automation-driven labor savings; factor in recurring API and connector costs into multi-year budgets.
- For vendors: invest in composable platform architectures and public, well-documented APIs; establish clear migration offers to capture renewals and reduce churn; and quantify automation ROI in dealer terms.
- For investors and M&A teams: focus on targets with sticky recurring revenue and data assets that enable monetization beyond core DMS functionality (e.g., digital contracting, valuations, inventory analytics).
- For CIOs and procurement: enforce security and compliance gating in vendor RFPs and require third-party attestations as part of contracting to reduce latent breach risk.
What the PW Consulting report delivers (practical, hands-on contents)
This market study is designed to be operationally useful to executives making 2026 decisions. Highlights include:
- A calibrated market model (historical 2020–2025, base year 2025; forecast 2026–2032) with scenario analysis and sensitivity to API licensing, migration velocity, and security investments.
- A competitive playbook profiling the principal vendors — technology strengths, differentiation vectors, recent strategic moves, and acquisition appetites — with practical vendor selection scorecards tailored to buyer archetypes.
- Case-based ROI models showing typical dealer-level productivity gains and payback periods under differing adoption scenarios for AI automation and cloud migration.
- Risk matrices evaluating cybersecurity, data privacy, and regulatory exposure, paired with recommended mitigation actions and estimated cost implications.
- Go-to-market and partnership templates for vendors seeking accelerated OEM, lender, and fintech integrations while managing API licensing exposure.
Competitive snapshot — names to watch
Our qualitative and quantitative assessments focus on vendors with demonstrable product breadth and strategic momentum: established DMS platforms expanding into unified customer data and AI, cloud-native players optimizing for ease of migration and service, and integrators that bundle complementary analytics or digital retailing capabilities. Recent notable moves include platform unification launches, foundation-suite migration incentives, AI fraud-control rollouts, and leadership changes that signal growth ambitions. These actions are reshaping buyer expectations and raising the bar for security and integration economics.
Next steps — how to use this intelligence
Use the briefing to align your 2026 priorities: update procurement scorecards to include security and API economics, recalibrate product roadmaps to emphasize data unification and automation, and revisit M&A screens to prefer targets with recurring services and unique data assets. For teams that need the full analytical depth — detailed segment matrices, vendor scorecards, price benchmarking, and downloadable financial models — the complete PW Consulting Auto Dealer Software Market report contains the proprietary tables and appendices that support board-level decisions and transaction due diligence.
To access the full report and supporting datasets, including the granular segmentation models and vendor benchmarking tools used to generate these conclusions, please visit PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: Auto Dealer Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com