

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Laminated Tubes Market to Reach USD 2,800 Million by 2032

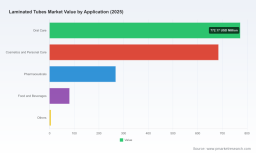
Laminated Tubes Market — Strategic Imperatives for 2026
As global manufacturers, CPG brand owners, and private-equity backers plan capital allocation and product roadmaps for 2026, laminated tubes present a classic “active innovation + regulatory pressure” play. PW Consulting’s laminated tubes market study (base year 2025; historical 2020–2025; forecast 2026–2032) maps a clear growth trajectory: the global market is projected to grow from a 2025 base of USD 1,810 Million to roughly USD 2,800 Million by 2032 at a 6.5% CAGR. This briefing synthesizes the strategic takeaways from that analysis — demonstrating the practical value of the full report for 2026 decision-making while deliberately withholding core segment-level minutiae to encourage direct access to the source intelligence.
Laminated Tubes Market
Executive snapshot: why this matters in 2026
-
Market momentum is durable. Mid-single-digit compound growth backed by ongoing demand from oral care, cosmetics, pharmaceuticals and niche food applications creates a stable growth envelope that supports both capacity investments and product premiumization strategies.
Laminated Tubes Market -
Regulation is the accelerant. Recent and upcoming EU measures on recyclability and single-use plastics are already reshaping product and packaging design requirements—creating near-term winners (companies that can rapidly deliver mono-material and recyclable high-barrier solutions) and losers (those heavily invested in legacy multi-layer laminates without transition roadmaps).
Laminated Tubes Market -
Fragmented supply landscape. Competitive concentration is modest, reflecting substantial regional players and a broad base of smaller specialists. That structure creates opportunities for consolidation, technology-led differentiation, and regional reshoring strategies that can materially affect margins and service performance.
Market trajectory and implications
The report’s topline trajectory—USD 1,810 Million in 2025 growing at a 6.5% CAGR to an estimated USD 2,800 Million by 2032—defines the investment horizon for 2026. For corporate strategy teams this implies:
-
Capacity planning should be calibrated for sustained, not explosive, expansion. Greenfield and retrofit investments must be stress-tested across multiple demand scenarios and regulatory pathways.
-
R&D and packaging innovation budgets should be prioritized over undifferentiated volume plays. High-margin, compliance-ready portfolio options (recyclable mono-materials, paper-based bio-barriers, and advanced anti-counterfeiting laminates) will see outsized strategic value.
-
M&A and alliance strategies are time-sensitive. With modest top-line concentration and accelerating technological differentiation, acquisitive buyers can buy strategic capabilities and scale more efficiently than organic build-outs in many cases.
Competitive landscape — where advantage is forming
The competitive field is populated by global integrators, regional specialists, and technology-focused boutiques. The market’s moderate concentration—where the top three and top five players capture a relatively small portion of global revenue—keeps pricing dynamics competitive and service differentiation central to commercial success.
-
Essel Propack Limited (Mumbai, India) — A high-volume global manufacturer with a broad facility footprint. Its near-term investments in automated production lines underscore a dual focus on scale and productivity gains for core oral-care and personal-care platforms.
-
Albea S.A. (Nanterre, France) — Positioning itself as a sustainability leader with recyclable laminate platforms. Recent product launches focus on closing the loop for cosmetics and oral-care clients that face strict regional recyclability rules.
-
Amcor Limited (Melbourne, Australia) — Emphasizes ultra-lightweight and PCR-containing laminates and circular business models. Their European market initiatives illustrate how packaging suppliers can leverage regulatory compliance as a commercial differentiator.
-
Huhtamaki Oyj (Espoo, Finland) — Advancing paper-based bio-barrier tubes and certifications that resonate with sustainability-minded brands; their direction signals a material-substitution pathway for premium personal-care segments.
-
Berry Global Group, Inc. (USA) — Focused on hybrid technologies and premium graphics capabilities, aiming to capture higher-margin opportunities in cosmetics and pharmaceuticals with patented process advantages.
-
Hoffmann Neopac AG (Germany) — Mono-material recyclable solutions and GMP-compliant production make them a natural partner for pharma and premium cosmetics—segments where regulatory and quality standards are non-negotiable.
-
Other regional and specialist players — A broad set of Asian, North American, and European suppliers supplies tailored ABL and PBL offerings, specialized printing (full-color offset) and service models optimized for local OEMs and co-packers.
Recent developments across these firms—new recyclable platforms, capacity expansions, investments in premium printing technologies, and integrated anti-counterfeiting layers—show the market bifurcating between scale-plays and technology/sustainability-specialists. Each strategic posture has different implications for partners, channel strategy, and margin pools.
Regulation, cost dynamics and material risk
-
Regulatory regime changes (notably EU packaging laws and single-use plastics enforcement timelines) are tightening recyclability standards and pushing toward mono-material designs and tethered closures. By 2026, manufacturers without clear compliance routes risk losing access to key European tenders and face growing specification risk from multinational brands.
-
Raw-material volatility remains a structural margin risk. Laminated tubes incur higher production cost structures than simple polyethylene tubes due to multilayer films, adhesives, and barrier layers; multi-year resin price shocks demonstrated between 2021 and 2023 materially affected producer economics. Hedging, supplier diversification, and process efficiencies are therefore central to margin protection.
-
Recyclability is technology + systems problem. Delivering a recyclable tube is necessary but not sufficient—suppliers must align with collection and recycling streams, secure certifications, and often re-engineer supply chains to ensure recyclate uptake and credible marketing claims.
2026 playbook — prioritized actions for executives
-
Audit product portfolios against imminent regulatory thresholds. Identify “at-risk” SKUs and create a two-track remediation plan: quick-win packaging swaps and medium-term platform redesigns.
-
Accelerate qualification of mono-material and bio-barrier technologies with pilot customers. Use 2026 to convert early pilots into validated SKU families ready for scale in 2027–2028.
-
De-risk supply through regional sourcing and flexible capacity. Consider third-party manufacturing partnerships in strategic geographies to reduce lead-times and buffer raw-material shocks.
-
Monetize premium capabilities. Premium printing, integrated anti-counterfeiting measures, and high-barrier recyclable laminates are differentiators that can sustain price premiums in cosmetics and pharma segments.
-
Pursue bolt-on M&A selectively. Look for technology enablers (coatings, adhesives, recyclability IP) and regional converters that offer commercial footholds without protracted build times.
-
Invest in sustainability claims infrastructure. Certifications, mass-balance accounting, and transparent supply-chain storylines are prerequisites for brand partnerships and procurement approvals in 2026.
-
Embed scenario planning in CAPEX approval. Use demand, price, and regulatory scenarios to size lines and automation investments—favor modular and upgradeable manufacturing modules where possible.
What PW Consulting’s full report delivers
PW Consulting’s laminated tubes market study goes beyond this executive briefing to provide the operational intelligence executives need for 2026 execution. The full report includes:
-
Detailed historical and forecast market sizing (2020–2032) segmented by material type, application, and region with scenario-driven projections.
-
Product- and process-level technology mapping that highlights which laminate architectures are compatible with current recycling systems and which require system changes.
-
Unit-cost and margin benchmarking under multiple resin-price scenarios, allowing CFOs to stress-test profitability by SKU families and plant networks.
-
Commercial playbooks for buyer-supplier negotiations, tender positioning, and value-based pricing for premium features such as anti-counterfeiting and high-resolution graphics.
-
Competitor dossiers with capability matrices, recent investments, and M&A activity — enabling rapid competitor response planning.
-
Implementation roadmaps and KPI templates for sustainability transitions, pilot rollouts, and regulatory compliance tracking.
In keeping with the “trailer” principle, this briefing demonstrates the report’s analytical depth and actionable orientation without publishing the full set of granular regional and application splits. That detailed segmentation — critical for plant-siting, product prioritization, and commercial targets — is contained in the report and interactive model.
How to use this intelligence in 90/180/365 day cycles
-
90 days: Complete a portfolio compliance audit and launch priority pilots for recyclable or mono-material tube designs with one or two anchor customers.
-
180 days: Finalize supplier agreements for critical barrier resins and adhesives, initiate capacity adjustments (retrofits or lease options), and align marketing claims with certification timetables.
-
365 days: Execute on scaled production for validated SKUs, evaluate selective M&A targets identified in the report, and lock in market access strategies for regulated regions.
Conclusion — the strategic choice for 2026
Laminated tubes sit at an inflection point where regulatory shifts and material innovations will reallocate value across the supply chain. The market’s growth profile supports both expansion and selective premiumization, but success in 2026 will favor organizations that combine technical agility (barrier and mono-material solutions), commercial creativity (value-based pricing and premium features), and regulatory foresight (certifications and systems alignment). PW Consulting’s full laminated tubes study gives leaders the concrete data, scenario models, and implementation playbooks to convert these imperatives into board-level decisions and 12–36 month execution programs. For the detailed segmented forecasts, competitor benchmarking matrices, and the interactive financial model that underpin these recommendations, access the full report.
For detailed analysis of this topic, please visit the official page: Laminated Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com