

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VCI Packaging Market to Reach USD 805M by 2032 at 5.2% CAGR

Volatile Corrosion Inhibitors (VCI) Packaging Materials: Strategic Outlook for 2026 Decision-Makers
Executive snapshot
VCI packaging is no longer a niche technical choice reserved for specialty supply chains; it is a strategic lever for manufacturers, OEMs, and supply-chain operators confronting simultaneous pressures from regulation, sustainability expectations, and volatile raw-material markets. Our PW Consulting market model (base year 2025) shows the global VCI packaging market expanding from roughly USD 565 million in 2025 toward an expected USD 805 million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 5.2% across the 2026–2032 forecast window. That headline growth hides important inflection points—regulatory-driven reformulation, the rise of circular programs, and regionally uneven supply-chain dislocations—that will determine winners and losers in 2026 and beyond.
Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Why this research matters for 2026 strategies
Senior executives who must make near-term investment, sourcing, and M&A decisions need more than trend headlines. They need a decision-grade view of: 1) where demand pockets are strengthening or softening; 2) the sensitivity of product economics to petrochemical and specialty-chemical swings; 3) which regulatory shifts force product reformulation or market exclusion; and 4) how competitive positioning will change as sustainability certification and closed-loop programs become commercial differentiators.
Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Our market study delivers an integrated evidence base that converts those needs into actionable options. It merges an empirically calibrated demand model (historical 2020–2025), a granular supplier landscape, financial scenarios, and a regulatory-impact matrix to guide procurement, R&D prioritization, pricing strategy, and M&A screening for calendar 2026.
Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Market trajectory — what the numbers tell you
The VCI packaging market has shown steady expansion through the early 2020s: our historical model captures growth from the low hundreds of millions in 2020 to a base of approximately USD 565 million in 2025. From that base, our forecast projects continued expansion to about USD 598 million in 2026 and onward to roughly USD 805 million by 2032 under a central case (5.2% CAGR). Importantly, the growth path is not uniformly smooth: macro shocks to petrochemical inputs, episodic regulatory shifts, and the commercial rollout of biodegradable and closed-loop solutions all introduce non-linearities into demand and price realization.
For corporate planners, two implications follow. First, steady aggregate growth masks pockets of accelerated uptake—particularly where sustainability certification or regulatory compliance becomes a buyer requirement. Second, modest overall concentration (with the top players holding a mid-single-digit tens share) implies a fragmented competitive field in which technical differentiation and supply-chain control materially influence margin capture.
Competitive landscape: incumbents, specialists and the sustainability wave
The competitive picture combines established specialty-materials manufacturers with regional converters and vertically integrated players. Key firms profiled in our analysis include long-standing VCI specialists and converters that have invested in polymer compounding, bio-resin blends, and closed-loop recycling programs. Recent corporate moves underscore three strategic themes:
- Product reformulation and eco-design as market entry tickets — manufacturers are launching PFAS-free, nitrite-free, and biodegradable VCI films to align with REACH/RoHS thresholds and end-customer sustainability targets.
- Vertical integration and localized compounding — investments in regional compounding capacity are being used to mitigate tariff and raw-material volatility while accelerating time-to-market for reformulated products.
- Circularity and certification as commercial differentiators — closed-loop recycling programs and third-party regulatory certification are shifting from “nice-to-have” to procurement prerequisites in many industrial supply chains.
Examples we track in the market: strategic product launches of biodegradable VCI films, certification of post-consumer resin formulations that meet tightened chemical thresholds, the introduction of branded closed-loop recycling programs, and new compounding facilities oriented toward bio-resins and polymer blends. These moves are not scattered: they reflect a coordinated industry response to regulatory and customer pressures that will amplify in 2026.
Regulatory, tariff and raw-material dynamics shaping 2026
The regulatory environment is an accelerant for change. Recent and impending restrictions under REACH and RoHS increasingly constrain certain amine-based VCI chemistries and phthalate-based plasticizers. At the same time, market-facing innovations—PFAS-free and nitrite-free formulations—have already achieved regulatory acceptance in important markets, creating first-mover advantages for compliant product lines.
Trade and supply-chain policy add another layer. A material tariff shock implemented in 2025 has raised the landed cost of some imported chemicals and packaging components, prompting firms to reconsider sourcing geographies and to accelerate localization strategies. Meanwhile, export restrictions and tariff volatility for petrochemical feedstocks elevate the strategic value of compounding and alternative raw-material sourcing—drivers that are explicitly captured in our cost-sensitivity scenarios.
For procurement and product teams, this translates into concrete actions: prioritize dual-sourcing for critical inputs, fast-track qualification of compliant formulations, and build regulatory surveillance into product roadmaps to avoid reactive reformulation costs.
Practical strategic playbook for 2026
Based on our modeling and competitive analysis, we recommend the following priority actions for companies active in or evaluating entry into the VCI packaging market:
- Scenario-based planning: adopt at least three demand-cost-regulation scenarios (conservative, central, aggressive) and stress-test EBITDA under each to guide capital allocation.
- Portfolio reshaping toward compliant and circular products: accelerate development or licensing of PFAS-free, biodegradable, and PCR-capable VCI films; treat certification as a go-to-market enabler.
- Localized compounding and manufacturing: evaluate greenfield or JV compounding facilities in tariff-affected regions to shorten lead times and reduce exposure to raw-material transport risk.
- Commercial differentiation via circular programs: pilot closed-loop recycling or take-back schemes in key accounts to secure long-term supply contracts and premium pricing.
- Sourcing and supplier risk management: expand supplier scorecards to include regulatory compliance, circular-capability, and traceability metrics; implement inventory buffers for critical additives.
- M&A and partnership screen: prioritize bolt-on acquisitions that add bio-resin expertise, PCR handling, or regional compounding capacity rather than broad-spectrum roll-ups.
- R&D and product validation: invest in accelerated testing and third-party certification to minimize time-to-market for new chemistries and to de-risk procurement bids.
What the full PW Consulting study provides you
Our full report is designed to be immediately operational for commercial, procurement, and M&A teams. Deliverables include:
- A calibrated demand model (historical 2020–2025 and forecast 2026–2032) with scenario toggles for input-cost shocks and regulatory timelines.
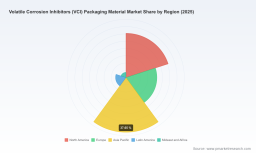
- Granular market-sizing by region, product type, and end-use application (available in the full dataset) plus price and margin decks for typical VCI film, bag and paper constructions.
- Supplier dossiers and capability heat maps, including compounding footprint, sustainability credentials, and commercial-strength indicators.
- Regulatory-impact matrices and an action checklist to prepare for REACH/RoHS-like restrictions and certification requirements in major markets.
- Commercial playbooks: procurement scorecards, negotiation levers, and a short-list of M&A targets aligned to strategic themes.
- An Excel-based financial model you can download, adapt and use for M&A valuation, NPV of manufacturing investments, or pricing sensitivity analysis.
Because the most commercially valuable elements are the granular splits and supplier-level models, these are intentionally reserved for the full report and accompanying data pack—exactly the content teams will need to move from strategy to execution.
How to use the insight in 90 days
- Month 1 — Diagnostic: Map your product portfolio against the regulatory-impact matrix and identify one to two “at-risk” SKUs that require reformulation or certification.
- Month 2 — Supplier strategy and pilots: Launch supplier qualification for alternative compounding partners and pilot a PCR or biodegradable VCI film in one key account.
- Month 3 — Commercialization & contract protection: Negotiate longer-term offtake or recycling agreements with early-adopter customers, using certification and circularity as negotiation levers.
Conclusion — from insight to advantage
The VCI packaging market presents a classic strategic opportunity: predictable aggregate growth coupled with disruptive pockets of change driven by regulation, sustainability, and supply-chain politics. Firms that integrate regulatory foresight, localized manufacturing, and circular commercial models will capture disproportionate value. Our PW Consulting study furnishes the quantitative backbone and the decision playbooks needed to convert market intelligence into 2026 actions.
To access the full dataset, supplier scorecards, and the downloadable financial model that underpins these conclusions, consult the complete report and data pack on our website. The strategic path you choose now will determine whether your organization secures premium margins and durable contracts—or gets priced into commodity trading as the market evolves.
For detailed analysis of this topic, please visit the official page: Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com