

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gas Purifier Market to Grow at 6.2% CAGR to USD 244M by 2032

Gas Purifier Market — Strategic Preview for 2026 Decision Makers
As PW Consulting’s senior industry analyst, I present a focused strategic preview of the global Gas Purifier market to anchor executive decision-making in 2026. This article synthesizes the market’s recent trajectory, near-term outlook, competitive structure, and the actionable strategic levers executives should prioritize. It deliberately highlights the macro figures and directional trends that matter for portfolio, investment, and commercial choices while withholding granular segment-level data that you will find in the full report.
Gas Purifier Market
Why this preview matters for 2026 strategy
2026 will be a pivotal year for companies operating in gas purification: capital planning cycles, multi-year technology roadmaps, and regulatory shifts converge to create windows of accelerated value or risk. Our research indicates a steady market expansion with a base year of 2025 and a mid-single-digit compound annual growth rate over the 2026–2032 forecast horizon. That trajectory creates clear implications for capacity investment, R&D prioritization, and go-to-market choices—especially for firms aiming to scale or defend margin in maturing geographies.
Gas Purifier Market
Market trajectory at a glance
-
The market evolved from a modest base in the early 2020s and reached a material scale by the 2025 base year, reflecting demand resilience across industrial processing, refining, and high-purity manufacturing.
Gas Purifier Market -
Looking forward from 2026 through 2032, the sector is projected to expand at a compound annual growth rate of approximately 6.2%, with the total market value increasing consistently year-on-year under our central scenario.
-
This steady growth masks important inflection points—particularly where technology substitution, environmental regulation, and decarbonization initiatives intersect with industrial gas demand.
What is driving growth—and where the constraints are
-
Demand-side drivers: Continued industrialization in selective geographies, the scale-up of high-purity applications (notably in advanced manufacturing), and the early commercial rollouts of hydrogen value chains are lifting long-term demand for gas purification. Additionally, greater emphasis on product quality and consistency by end-users has increased willingness to pay for higher-performance purification solutions.
-
Technology and cost drivers: Performance gains in sorbents and membrane materials, combined with improvements in system integration and remote monitoring, are lowering lifecycle cost-of-ownership for advanced purifiers—favoring vendors who can bundle hardware, consumables, and analytics.
-
Regulatory and ESG pressures: Tighter emissions and safety standards are prompting retrofits and new equipment spend, while energy efficiency mandates are reshaping procurement criteria for large industrial buyers.
-
Constraints: Supply-chain volatility for specialty materials, long lead times for critical components during peak cycles, and uneven capital availability across regions temper upside and raise execution risk for aggressive capacity expansion strategies.
Technology and segmentation themes (directional)
The market continues to be organized around three technology archetypes—adsorption-based systems, membrane-based systems, and cryogenic solutions. Each has a distinct value proposition and lifecycle economics: adsorption solutions remain the most prevalent in applications where versatility and cost-effectiveness matter; membranes are gaining ground where footprint and modularity are prioritized; cryogenic systems are indispensable for extreme-purity or large-scale separation tasks.
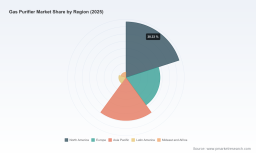
Application demand is concentrated in industrial gas processing, hydrocarbon refining, and high-purity manufacturing segments. While the full report contains detailed breakdowns by region, type, and application, this preview intentionally withholds those granular splits. What matters strategically is the directional shift: higher-value, lower-volume applications are becoming a larger part of many vendors’ portfolios, while traditional bulk-purification demand remains important for scale players.
Competitive structure and market concentration
The market exhibits a moderate level of concentration. Three leading players together account for a meaningful but not dominant share, with the top five firms controlling a larger portion—indicating room for regional specialists and technology-focused challengers. This structure produces several strategic implications:
-
Scale matters for project economics in large industrial and cryogenic applications, favoring incumbents for turnkey contracts.
-
There is strategic space for niche innovators—particularly those offering differentiated materials, digital services, or lower-capex modular solutions targeting decentralized or specialty applications.
-
M&A can be an effective route to accelerate capability build-out, especially where inorganic deals close technology gaps or add geographic reach. However, integration risk and margin compression must be underwritten by clear synergies in consumables, services, or aftermarket revenue.
Strategic priorities for 2026 decision makers
Below are the key actionable priorities that executives should embed in 2026 plans. Each is accompanied by tactical considerations to translate insight into decisions.
-
Recalibrate capacity and capex with scenario lenses. Central-case growth is strong but not explosive. Use a two-track capex approach: secure flexible, modular capacity to capture near-term demand while staging large, irreversible investments until clear regional signals (policy, offtake) materialize.
-
Prioritize product-service bundles. The value pool is migrating from pure hardware sales to recurring revenue streams—consumables, maintenance contracts, and analytics. Make near-term investments in aftermarket capabilities and digital monitoring to lock in lifetime customer relationships.
-
Differentiate through materials and IP. Improvements in sorbents and membrane materials shift total cost of ownership. Accelerate targeted R&D or bolt-on acquisitions that shorten time-to-market for higher-performance media. Protect and commercialize intellectual property through licensing models where appropriate.
-
Develop targeted regional plays. Not all regions are the same—regulatory trajectories, infrastructure build-out, and buyer sophistication differ. Prioritize markets where demand, margin profile, and execution capabilities align. Use local partnerships to mitigate entry risk and accelerate service coverage.
-
Design M&A with integration-first logic. Deal value is created only if integration preserves cross-sell channels and reduces cost-to-serve. Favor acquisitions that immediately strengthen consumables, aftermarket services, or digital capabilities—areas with faster payback.
-
Hedge supply-chain and strategic material risk. Establish dual sourcing for specialty materials, longer-term supply contracts for critical inputs, and localized inventory strategies. Consider strategic equity partnerships with upstream material suppliers for tighter alignment.
-
Embed sustainability into product roadmaps. Energy efficiency, lower lifecycle emissions, and recyclable materials are rising procurement criteria. Incorporate lifecycle assessments into product design and communicate quantified ESG benefits to buyers and investors.
How PW Consulting’s report helps executives act in 2026
Our full Gas Purifier Market report provides the operational and analytical foundation you will need to execute the priorities above. Highlights include:
-
Scenario-based market sizing and forecast to 2032 built from the 2025 base year, informing capital allocation and revenue planning under multiple demand cases.
-
Commercial playbooks mapped to buyer archetypes—identifying which product bundles and commercial models win in industrial, refining, and high-purity segments.
-
Profitability and margin waterfall analysis by technology archetype to guide pricing, cost-to-serve, and product portfolio decisions.
-
A disciplined M&A framework—target screening criteria, valuation guidance, and integration scorecards that reduce deal execution risk.
-
Operational checklists for supply-chain resilience, manufacturing footprint optimization, and aftermarket scaling.
-
Regulatory and policy trackers that highlight where compliance-driven replacement or retrofit cycles will create near-term demand surges.
Using this preview: recommended next steps for leadership teams
-
Board and C-suite: Incorporate the central 6.2% CAGR and the growth path embedded in the 2025–2032 forecast into strategic planning workshops. Stress-test major capex proposals against downside and upside scenarios.
-
Business unit leaders: Translate the technology and application themes into a 12–24 month product and service roadmap—with explicit milestones for modular capacity, digital services launch, and consumable commercialization.
-
Corporate development teams: Use the competitive concentration context to prioritize targets that strengthen consumables and aftermarket services, and prepare integration playbooks that capture synergies within 12 months post-close.
-
R&D and operations: Align materials strategy and supplier relationships to the projected demand curve, and accelerate pilots of lower-energy purification technologies that improve lifecycle economics.
Closing: the strategic inflection is now—act with data and optionality
The Gas Purifier market is expanding at a pace that rewards deliberate, data-driven decisions. The macro picture—anchored to our 2025 base-year assessment and a 6.2% CAGR outlook—creates clear opportunities for revenue growth, margin expansion, and market share shifts. Yet execution risk and regional variability mean that optionality, partnership strategies, and service-led differentiation will determine winners in 2026 and beyond.
This preview is designed to ensure your leadership team asks the right strategic questions this budget and planning cycle. For the full segmentation, regional breakdowns, and the granular datasets that underpin our recommendations—including the detailed split by region, purifier type, and application—request the complete PW Consulting Gas Purifier Market report and the accompanying decision-ready toolkits.
For detailed analysis of this topic, please visit the official page: Gas Purifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com