

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EAS System Market at USD 1,325M in 2025 — Insights & Forecast

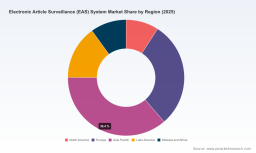
Electronic Article Surveillance (EAS) System Market — 2026 Strategic Preview
Executive summary
The global Electronic Article Surveillance (EAS) market is entering 2026 from a position of steady expansion and tactical transformation. Our base-year analysis (2025) shows the market has grown from roughly USD 1.08 billion in 2020 to USD 1.325 billion in 2025, and is projected to continue expanding through our forecast horizon (2026–2032) at a compound annual growth rate (CAGR) of 4.66%, reaching approximately USD 1.82 billion by 2032 (figures in USD Million). Market concentration is meaningful but not prohibitive: the top three suppliers account for a material share (CR3 ~48%), while the top five take the market to a modestly higher level (CR5 ~54%).
Electronic Article Surveillance (EAS) System Market
For corporate leaders, security heads, retail CIOs and investors, the headline is clear: the EAS market is no longer a purely hardware play driven by loss-prevention budgets. It is becoming an integrated data and source-tagging layer of modern retail and supply chain architectures. That evolution changes how capital should be allocated in 2026 — from siloed fence-and-tag investments toward hybrid, software-enabled, and upstream-tagging strategies that deliver measurable inventory visibility, shrink analytics and operational efficiencies.
Electronic Article Surveillance (EAS) System Market
Why this research matters for 2026 decision-makers
- Capital prioritization under tighter margins: Retailers face elevated shrink and labor pressures. Our sector analysis indicates a material rise in shoplifting incidents compared to pre-pandemic levels, forcing security spend to compete with customer-experience and fulfillment investments. Boards need scenario-tested cases that show where EAS investments produce measurable ROI versus alternative allocations.
- Regulatory and procurement shifts: Recent regulatory movements (notably region-wide product-tagging expectations and retailer mandates to embed tags at source) are shifting costs and control upstream. Procurement and supplier-relations teams must redesign contracts, acceptance testing and certification pathways to accommodate source-tagging obligations while avoiding supply-chain friction.
- Technology convergence and vendor selection: The market is evolving from single-technology deployments (RF or AM) to multi-technology stacks combining RFID, RF/AM sensors, and edge-AI analytics. Decision-makers require vendor scorecards and interoperability playbooks to select providers that minimize integration risk and future-proof capital.
- Operationalization of data: EAS installations are now expected to deliver more than alarm/no-alarm outcomes. Edge-AI, cloud analytics and item-level telemetry are turning EAS into a source of shrink diagnostics, inventory validation and in-store behavioural signals—necessitating new data governance, connectivity and personnel capabilities.
What the full report delivers — practical, deployable outputs
- Clear, model-backed market sizing (historical 2020–2025; forecast 2026–2032) expressed in USD Million with sensitivity ranges and scenario variants (base, accelerated adoption, and constrained funding).
- Vendor benchmarking and decision matrices: technology fit-by-use-case, total cost of ownership (TCO) templates, and integration-risk scoring for legacy POS, WMS and cloud analytics ecosystems.
- Step-by-step implementation playbooks for three priority archetypes — enterprise grocery/supermarket chains, apparel & fashion retailers, and healthcare/pharmaceutical environments — including pilot design, KPIs and escalation paths.
- Procurement templates: RFP language, acceptance test plans, supplier SLAs tied to certification and post-installation analytics performance thresholds.
- Financial tools: ROI calculators, payback models and capex/opex comparators that include tag sourcing strategies (in-store vs. source-tagging) and labor-offset sensitivities.
- Risk and compliance mapping for regulation-driven tagging requirements, interoperability standards and certification pathways.
- Data and analytics architecture guidance for integrating EAS feeds with inventory management, loss-prevention suites and retail BI platforms.
Market dynamics shaping vendor and buyer strategy
The EAS landscape in 2026 is being reshaped by five converging dynamics:
Electronic Article Surveillance (EAS) System Market
- Upstream tagging mandates: Large retail customers are compelling suppliers to embed source tags, shifting operational responsibility and cost upstream. This materially affects category sourcing strategies and supplier contracts.
- Standards and interoperability: Industry-wide encoding and interoperability efforts mean buyers must prioritize vendors aligned to global guidelines to avoid lock-in and re-tagging costs.
- Edge-AI and false-alarm reduction: Deployments of edge-AI smart antennas have demonstrated substantial reductions in false alarms (our sector analysis notes reductions in the order of mid-30s percent in early adopters), which translates into better staff allocation and improved customer experience.
- Regulatory tailwinds: Digital product passport initiatives and region-specific tagging regulations create a compliance imperative and opportunity for solution providers offering traceability extensions to classic EAS functionalities.
- Economic pressure on shrink control: With reported increases in shoplifting incidents compared to pre-pandemic levels, EAS is re-evaluated as part of an omnichannel loss-prevention strategy, not simply a gate-and-tag expense.
Competitive landscape — who to watch and what they bring
The competitive set blends traditional EAS specialists with RFID manufacturers, systems integrators and certification players. Buyers should evaluate vendors not just on tag and sensor performance but on software ecosystems, cloud analytics, and upstream sourcing relationships.
- Sensormatic Solutions (Neuenhausen, Switzerland) — A leader in precision-calibrated acousto-magnetic (AM) systems that is layering AI-powered shrink analytics onto installed bases. Recent product introductions demonstrate a push to monetize existing field infrastructure via analytics subscriptions.
- Nedap (Groenlo, Netherlands) — A front-runner in RFID-based, item-level detection with cloud software that supports open-entrance layouts. Strategic large-store rollouts and multi-hundred-store contracts signal scalability for grocery and apparel chains.
- Avery Dennison (Mentor, Ohio, United States) — A major supplier of RFID-enabled inlays and labels focused on miniaturization and sterilization-compatible products for healthcare — a critical enabler for source-tagging in sensitive categories.
- Checkpoint Systems, Tyco Retail Solutions, Gunnebo Gateway AB — These vendors combine multi-technology portfolios and broad retail footprints; evaluate them for enterprise-scale installations and long-term service contracts.
- Specialists and integrators (ALL-TAG, Universal Surveillance Systems, Sentry Technology, Everon, Controltek, AIDC Technologies) — Often provide competitive pricing, niche products (hard-tags, deactivators, library systems) and focused regional services; strong candidates for targeted pilots.
- SGS — Plays a critical role as the independent testing and certification partner as source-tagging and regulatory scrutiny increase.
Recent vendor activity underscores the shift to hybrid solutions and scaling pilots into rollouts: product launches enhancing inlay miniaturization and RFID compatibility, large multi-store deployments, and analytics productizations announced through 2025–2026. These moves validate the market’s trajectory from discrete security appliances to data-driven operational platforms.
Strategic implications and a 90–180 day playbook for 2026
- Audit installed base and tag sourcing: Map current EAS technologies, tag types and supplier terms. Identify categories most affected by supplier mandates and plan re-specification timelines.
- Run targeted pilots: Deploy hybrid RFID + EAS pilots in anchor stores to measure shrink delta, false-alarm rates, and inventory reconciliation uplift. Incorporate edge-AI antennas where store density supports compute-at-edge economics.
- Revise supplier contracts: Insert clauses for source-tagging compliance, interoperability, and tag-encoding standards to avoid future rework costs.
- Choose integration-first vendors: Prioritize partners offering robust APIs, cloud analytics and certification support rather than lowest-cost hardware.
- Governance and data strategy: Establish data ownership, retention, and privacy rules for item-level telemetry, and align KPIs across loss-prevention, supply chain and customer-experience teams.
- M&A and partnership screening: For investors and strategic buyers, target companies that control tag supply, cloud analytics, or hold long-term retail contracts — these assets accelerate platform adoption.
Methodology and how to use this preview
This Executive Preview synthesizes our full market study, which uses a mixed-methods approach: primary interviews with retail and supplier executives, technology benchmarking, company financials and press disclosures, and bottom-up revenue modeling reconciled to macro demand drivers. The dataset is expressed in USD Million, with historical years 2020–2025 and a forecast window 2026–2032. The modeled CAGR for the forecast window is 4.66%.
To preserve strategic signal while protecting tactical insights, this preview intentionally omits granular regional, type and application splits that purchasers of the full report will receive. The full report contains detailed segmentation tables, regional demand curves, product-level price decks, competitive product feature matrices, downloadable raw datasets and customizable ROI models designed for board-level decision-making.
Next steps
If your 2026 planning cycle includes shrink-control investments, supplier-sourcing changes or retail-technology modernization, PW Consulting’s full Electronic Article Surveillance (EAS) System Market Report provides the data, vendor playbooks and procurement tools to move from pilots to scaled, measurable outcomes. For access to the full segment-level data, vendor scorecards and the downloadable financial models that underpin this preview, please visit our report page or contact our industry team for a tailored briefing.
— PW Consulting, Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: Electronic Article Surveillance (EAS) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com