

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrohydraulic Actuator Market to hit USD 392M by 2032, 6.8% CAGR

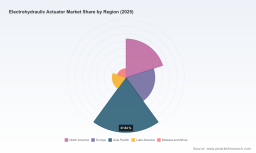
Electrohydraulic Actuator Market: Strategic Outlook for 2026 — PW Consulting Spotlight
Executive preview
Between 2020 and 2025 the global electrohydraulic actuator market expanded from approximately USD 180 million to USD 247 million, reflecting steady investment in electrified motion systems across heavy industry, energy and automation. PW Consulting’s baseline projects continue that momentum: a compound annual growth rate (CAGR) of roughly 6.8% through the 2026–2032 forecast window, bringing the market toward the high hundreds of millions by 2032 under the base case. For corporate leaders setting 2026 priorities, that trajectory creates a narrow window to shape product roadmaps, partnerships, and go-to-market models before the next wave of consolidation and technology adoption crystallizes.
Electrohydraulic Actuator Market
Why this report matters to 2026 decision-making
-
Time-sensitive CapEx allocation: Procurement and capital planning cycles in utilities, oil & gas, and heavy industry must align with multi-year lead times for electrohydraulic systems. Our analysis translates market growth and technology adoption curves into recommended procurement horizons and budget phasing.
Electrohydraulic Actuator Market -
Product and platform choices: Manufacturers face trade-offs between high-force, high-precision servo EHAs and modular, serviceable designs optimized for uptime. The report helps executives prioritize platform investments that maximize mid-decade returns.
Electrohydraulic Actuator Market -
M&A and partnership targeting: With a moderate level of market concentration (the top three players account for roughly one-third of revenue and the top five for about forty percent), 2026 is potentially a peak window for bolt-on acquisitions and strategic alliances that rapidly expand technical capability or service footprint.
-
Regulatory and safety compliance: New functional safety and energy-efficiency requirements are already shaping procurement specifications. The study connects regulation-driven demand signals to product certification and testing roadmaps.
-
Aftermarket and service economics: As customers shift from capex-heavy to uptime-oriented contracts, companies that can offer repairable, upgradeable actuators and predictable lifecycle costs will capture a disproportionate share of long-term margin.
What’s inside the PW Consulting market brief (practical content you can act on)
-
Market sizing and forecasts (base year 2025): A transparent reconciled topline that traces historical trends (2020–2025) and projects out to 2032 under alternative scenarios. The published base scenario reflects the 6.8% CAGR referenced above.
-
Segment-level dynamics: Deep qualitative and quantitative assessment by actuator architecture (e.g., linear vs. rotary), by end-use domain (energy, industrial automation, automotive-adjacent systems and others), and by geography — structured to reveal where unit-level demand and value per installation diverge. Note: the preview intentionally omits granular segment allocations; the full dataset and downloadable tables are available in the full report.
-
Supply-chain and raw-material sensitivity: Line-item risk maps for components (sensors, high-voltage insulation, welded actuator housings, power electronics) with recommended mitigation actions and alternative sourcing strategies.
-
Competitive playbooks and supplier scorecards: Comparative capability matrices across product performance (force, stroke, response time), industrial protection (IP ratings, welding and fabrication practices), certification readiness (functional safety levels), and serviceability (repairability and part commonality).
-
Commercial models and pricing anchors: Bundled service propositions, outcome-based contracting templates, and guidance on margin capture as systems shift from CAPEX to integrated service revenue streams.
-
Strategic roadmaps: Recommended three- to five-year R&D and go-to-market trajectories tailored to market entrants, incumbent OEMs, and aftermarket service providers.
Competitive landscape: players that matter in 2026
Our benchmarking emphasizes technical differentiation, certification posture, and service model design rather than simple size ranking — enabling actionable comparisons for corporate development and procurement teams.
-
Dabeb-Elram (Daleside, Meyerton, South Africa) — Known for rugged, highly serviceable electrohydraulic actuators designed for power stations, refineries and mining. Their emphasis on fully replaceable parts and welded steel casings speaks directly to customers that prioritize maintainability and low lifecycle total cost in harsh environments.
-
Rotontek (China) — Focused on integrated electric-hydraulic linear actuators built for extreme environments (including underwater applications). Compact, IP68-class designs and multi-function packaging make them a candidate partner for OEMs seeking sealed, high-reliability modules.
-
Cowan Dynamics (United States) — Markets E2H-series actuators with both on/off and modulating control and has invested in high assurance functional safety. Their SIL 3 design orientation positions them favorably in safety-critical valve control and pipeline infrastructure.
-
Artimus Robotics (Boulder, Colorado) — Developing novel HASEL electrohydraulic soft actuators for robotics and dexterous manipulation. Their recent product launches (February 2026) deliver substantial mechanical performance gains and encapsulation advances, expanding the addressable market into higher-output automation applications.
-
Moog Inc. (Elma, New York) — A premium provider of servo electrohydraulic actuators across aerospace, defense and industry. Their strengths lie in high-performance motion control, precision actuation, and longstanding systems integration expertise.
-
Parker Hannifin Corporation (Cleveland, Ohio) — Offers compact EHA and hybrid systems that emphasize self-contained, high-force actuation in decentralized architectures. Their platform approach targets customers pursuing compact power-dense units and retrofit-friendly solutions.
Recent market signals and engineering implications
-
Technology leaps: The February 2026 Artimus HASEL launch illustrates how materials science and packaging can rapidly alter power-to-weight and safety trade-offs. High-voltage requirements and unique control interfaces for these soft actuators create both new opportunities and integration requirements for system designers.
-
Safety and standards: Suppliers that demonstrate readiness for SIL 3/functional safety certification will be preferred for critical infrastructure projects. Procurement teams should factor certification timelines into vendor selection and schedule risk.
-
Efficiency mandates: Regulatory pressure to improve energy efficiency is accelerating replacement cycles for legacy hydraulic installations. Electrohydraulic solutions that deliver measurable efficiency improvements (and associated emissions reductions) will be advantaged in competitive bids.
-
Design for serviceability: Companies emphasizing repairable, field-replaceable subassemblies (a model exemplified by some specialized manufacturers) can both shorten downtime and create aftermarket revenue streams. This is a critical differentiator in mining, refining, and remote-industrial deployments.
How to translate insights into action in 2026
-
Run a two-track product strategy: Invest in a high-performance corridor (servo-grade systems for precision applications) while developing modular, repair-first platforms for volume industrial markets. This hedges against divergent adoption rates across end-users.
-
Prioritize certification and test beds early: Allocate resources in 2026 to secure functional safety and energy-efficiency attestations. Being certified ahead of procurement cycles shortens sales cycles and reduces bid risk.
-
Lock in critical suppliers and validate alternatives: Given component lead times and specialized fabrication techniques (e.g., continuous welded housings), create dual-sourcing plans and qualify regional fabrication partners to reduce single-source risk.
-
Design for service and outcome contracts: Build aftermarket offerings and predictive maintenance capabilities; commercial models that monetize uptime will outperform pure product sales as the installed base grows.
-
Use M&A strategically: With market concentration indicating meaningful share for top players yet ample fragmentation for challengers, targeted acquisitions of niche specialists (soft-actuators, high-voltage control electronics, or field-service networks) can accelerate capability capture.
Signal watchlist for 2026
-
Finalization of regional energy-efficiency regulations that affect hydraulic system replacement thresholds.
-
Certification milestones by suppliers (e.g., SIL 3 readiness) that alter procurement shortlists for critical infrastructure projects.
-
Commercialization pace of soft-electrohydraulic muscles and their integration standards — monitoring supplier control-interface requirements is essential for OEMs and systems integrators.
-
Supply-disruption indicators across specialty materials and power electronics that would drive near-term price or lead-time spikes.
Next steps — how to use the full PW Consulting study
This introductory analysis is designed to guide executive discussions through 2026 planning cycles. The full report delivers the underlying datasets, interactive market models, downloadable supplier scorecards, and scenario tools that quantify the trade-offs summarized above — including granular segment economics, regional demand drivers, and a prioritized list of acquisition and technology partnership targets. We intentionally withhold segment-level allocations in this preview to preserve the value of the full, actionable intelligence package.
For strategy teams preparing FY-2026 roadmaps, PW Consulting’s Electrohydraulic Actuator Market study is a practical toolkit: align R&D investment timing with certification schedules, structure service offerings to capture aftermarket economics, and execute targeted corporate development to close capability gaps before the next phase of market consolidation.
For detailed analysis of this topic, please visit the official page: Electrohydraulic Actuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com